
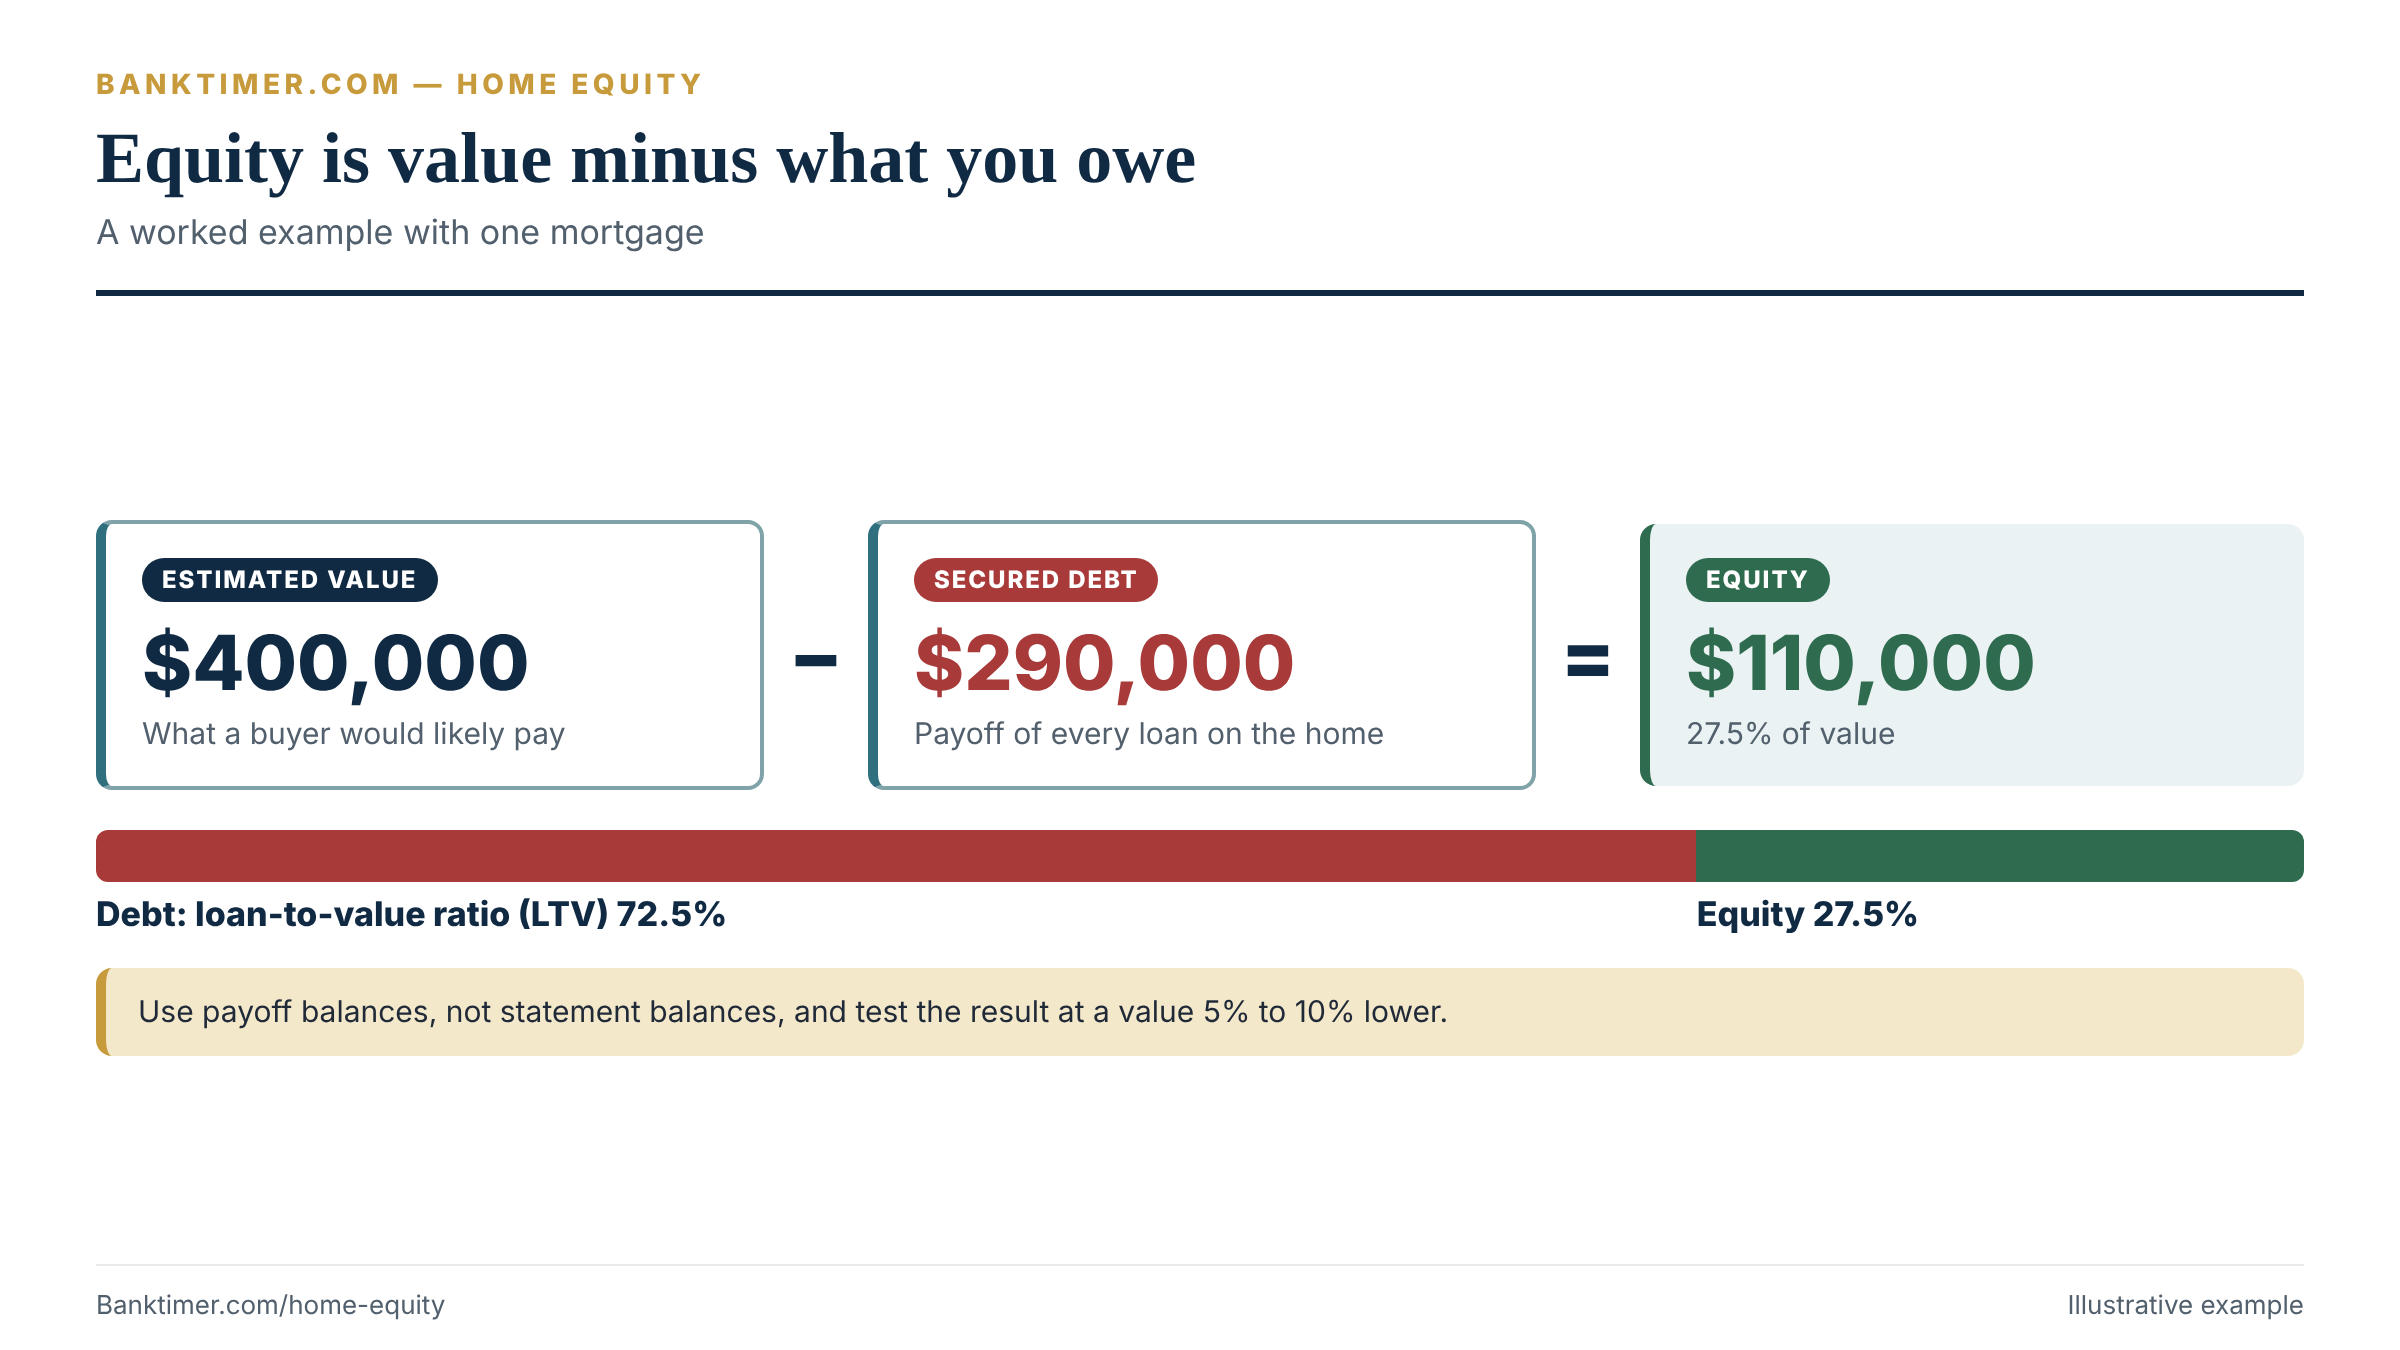
Home equity is your home’s current market value minus every loan secured by it. To calculate yours, estimate what the home would sell for, add up the payoff balances on your mortgage and any home equity loan or line, and subtract. A home worth $400,000 with $290,000 owed has $110,000 of equity, or 27.5%.
Your biggest variable is the value estimate, because a small change in value moves equity a lot. The main risk is that borrowing against equity puts your home behind the loan. Before you borrow, check how much of the equity a lender will actually lend against, which is usually well below the full amount.
The formula is simple, the inputs are not. Equity equals value minus liens. Value is an estimate until a sale or an appraisal, and payoff balances differ from statement balances.
Paper equity is not cash. Selling costs, taxes and moving expenses come out first. In our example, $110,000 of equity turns into about $78,000 at the closing table, assuming 8% selling costs.
Lenders cap what you can borrow. The 80% rule is common: total loans stay at or below 80% of value. On the example home, that leaves $30,000 of usable equity, not $110,000.
Three main tools tap equity. A home equity loan, a home equity line of credit (HELOC) and a cash-out refinance work differently, and the right one depends on your current mortgage rate.
What you do with the money matters. Federal tax rules allow the interest deduction only when the money buys, builds or substantially improves the home that secures the loan.
Every option uses your home as collateral. If you stop paying, the lender can foreclose.
What Home Equity Is and What It Is Not
Home equity is the part of your home you own outright, measured in dollars at today’s estimated value. It is not a bank balance. Nobody deposits it for you, and you cannot spend it until you sell, borrow against it, or otherwise convert it.
The equation has two sides. One side is the market value, meaning your best estimate of what a buyer would pay. The other is the total debt secured by the property, meaning your first mortgage plus any second mortgage, home equity loan, HELOC balance or other lien. Subtract the second from the first and you have equity.
Equity versus home value
People often mix up these two ideas, and the mix-up leads to bad decisions. Home value is the whole price tag. Equity is what remains after the lenders are paid. A $600,000 house with a $540,000 payoff has the same market value as a $600,000 house you own free and clear. The financial position is very different.
That is why a rising market does not make every homeowner equally wealthy. The owner with a small loan gains almost all of the increase. The owner who put little down gains the same dollars, yet the dollars are a bigger share of a thin cushion.
Equity can be negative
If the home is worth less than the debt against it, you have negative equity, often called being underwater. The same word appears in car loans, and our guide to negative equity in a car trade-in covers that version. With a house, negative equity limits your ability to refinance, borrow or sell without bringing cash to closing.
The table below defines the terms you will see on applications and appraisals. The common confusion column is where most mistakes start.
| Term | Plain-English meaning | Why it matters | Common confusion |
|---|---|---|---|
| Market value | What a willing buyer would likely pay | Sets the top half of the equity equation | An online estimate is not a sale price |
| Appraised value | A licensed appraiser’s opinion for a lender | Lenders lend against it, not your guess | It can come in below your estimate |
| Payoff balance | What you must pay to clear a loan today | Used in the subtraction | Can differ from the statement balance |
| Home equity | Value minus all secured debt | Your ownership stake in dollars | Not the same as cash on hand |
| Loan-to-value ratio (LTV) | First mortgage divided by value | Lenders price and limit loans by it | LTV falls as equity rises |
| Combined LTV (CLTV) | All secured loans divided by value | Includes second mortgages and lines | A new line raises it immediately |
| Tappable equity | Equity above the lender’s CLTV cap | The amount you can realistically borrow | Always less than total equity |
| Negative equity | Debt exceeds value | Blocks most borrowing and easy sales | Also called underwater |
Appraisal, payoff and CLTV are the three places where the lender’s numbers differ from the numbers you carry in your head. We build each one into the calculation next.
How to Calculate Home Equity Step by Step
You can run the calculation in about ten minutes with three documents. You need your latest mortgage statement, any second loan or line statement, and a realistic value estimate. The goal is a number you could defend to a lender, not a flattering one.
- Estimate the market value. Use recent sales of similar homes nearby, a lender’s estimate, or a professional appraisal. Use a conservative figure.
- List every loan secured by the home. Include the first mortgage, a second mortgage, a home equity loan, a HELOC balance, and any tax or contractor lien.
- Get the payoff balance for each. Call the servicer or log in and request a payoff quote. It includes interest accrued to a specific date.
- Subtract. Equity equals value minus the total of the payoffs.
- Convert to percentages. Equity percentage is equity divided by value. LTV is total debt divided by value. The two add to 100%.
A worked example
Take a home you estimate at $400,000. The first mortgage payoff is $290,000, and there is no second loan. Equity is $110,000. That is 27.5% of value, so the loan-to-value ratio is 72.5%.
Now change only the debt. The table compares three illustrative owners of the same $400,000 house. Home B bought with a small down payment. Home C borrowed heavily and then saw prices dip.
| Scenario (illustrative) | Value | Total owed | Equity | Equity % | LTV |
|---|---|---|---|---|---|
| Home A: moderate loan | $400,000 | $290,000 | $110,000 | 27.5% | 72.5% |
| Home B: small down payment | $400,000 | $355,000 | $45,000 | 11.25% | 88.75% |
| Home C: underwater | $400,000 | $410,000 | -$10,000 | -2.5% | 102.5% |
The decision-driving point is that identical houses can give very different borrowing power. Home A can likely borrow something. Home B probably cannot without exceeding common limits. Home C cannot borrow at all and would need cash to sell.
Why the value estimate is the shaky part
Online estimates, tax assessments and appraisals can differ by tens of thousands of dollars. Your property tax assessment is set for tax purposes and may lag the market. An online estimate is a statistical guess. A lender’s appraisal is the number that counts when you apply, and it can land well below what you hoped.
Run the numbers at three values: your estimate, 5% below it, and 10% below it. If the borrowing plan only works at the high number, the plan is fragile.
Payoff balance versus statement balance
Your statement balance is what you owed on the statement date. The payoff balance adds interest accrued since then and any fees, so it is usually a bit higher. For a first-pass estimate the difference is small. For a lender’s calculation, the payoff figure and the remaining balance on any junior lien both count.
What Moves Your Equity: Paydown, Prices and Debt
Four forces change your equity over time. They are your down payment, the principal you repay, the market’s direction, and new debt you add against the home. Only the first two are under your control, and the second one is slower than most people expect.
The down payment sets the starting point
Equity on day one equals your down payment, adjusted for any difference between the price you paid and the appraised value. Put 20% down on a $400,000 home and you start with $80,000 of equity. Put 5% down and you start with $20,000. Every dollar of starting equity is a dollar the lender cannot lose.
Principal repayment builds equity slowly at first
A standard fixed-rate mortgage is front-loaded with interest. On a $320,000 loan at 6.50% over 30 years, the monthly principal-and-interest payment is $2,022.62. In month one, $1,733.33 goes to interest and only $289.28 reduces the balance.
Over the first year you pay about $24,271 in total, and only $3,577 of it reduces the loan. The share of each payment that goes to principal grows every month, but you need years before it becomes the larger piece. The illustrative table below separates the two sources of equity.
| End of year | Loan balance | Principal repaid | Equity if price stays flat | Equity if price grows 3% a year |
|---|---|---|---|---|
| 0 | $320,000 | $0 | $80,000 | $80,000 |
| 1 | $316,423 | $3,577 | $83,577 | $95,577 |
| 5 | $299,555 | $20,445 | $100,445 | $164,155 |
| 10 | $271,284 | $48,716 | $128,716 | $266,283 |
| 15 | $232,189 | $87,811 | $167,811 | $390,998 |
| 20 | $178,129 | $141,871 | $221,871 | $544,316 |
Assumptions: $400,000 purchase price, $80,000 down payment, $320,000 loan at 6.50% fixed for 30 years. The 3% growth column is a what-if, not a forecast. Prices can fall, stall or rise faster, and they vary by market.
The contrast between the last two columns explains most of the wealth gap among owners. After 10 years, repayment alone added about $48,700. A steady 3% annual price rise would have added far more. You control the first, the market controls the second.

Price changes act like leverage
Because equity is a small slice of value, a modest price move changes it by a larger percentage. Using the Home A example ($400,000 value, $290,000 owed), a 10% drop in value cuts equity from $110,000 to $70,000, a loss of 36.4%. A 10% rise lifts it to $150,000, a gain of the same 36.4%.
A 27.5% drop in value would wipe the equity out entirely. The thinner your equity, the less drop it takes to reach zero. At Home B’s 11.25% equity, a drop of 11.25% erases it.
New debt reduces equity the day you borrow
Adding a second loan or drawing a line lowers equity immediately, even though you now hold cash. Borrow $30,000 against the example home and your equity falls from $110,000 to $80,000. The money is real, but so is the liability. The only equity you can safely spend is the equity you do not need as a cushion.
How to Build Equity Faster
Building equity quickly means either shrinking the loan faster or raising the value of the home. The first is reliable. The second is not.
Pay extra principal
Extra payments go straight to principal if you tell the servicer to apply them that way. On the $320,000 example loan, an extra $200 a month shortens the payoff from 360 months to 281, a saving of 79 months. It also cuts total interest from about $408,142 to about $302,714, a difference of $105,429. After five years you would owe roughly $14,135 less than on the standard schedule, on $12,000 of extra payments.
Before you do this, confirm the loan has no prepayment penalty. Check also that your emergency savings are in place. Money sent to principal is hard to get back without borrowing. Our emergency fund guide explains how to size that cushion first.
Choose a shorter term when you can afford it
A 15-year mortgage builds equity much faster. At an illustrative 6.00%, a $320,000 loan has a payment of about $2,700. After five years the balance is about $243,229, versus $299,555 on the 30-year example. The rate would typically differ from a 30-year loan, so treat the figures as a direction, not a quote.
The trade-off is a payment about $678 higher each month. A shorter term works well for stable incomes and badly for tight budgets. Extra payments on a 30-year loan give you the same effect with the freedom to stop.
Compare ways to build equity
| Tactic | How it builds equity | Typical cost or limit | Main trade-off |
|---|---|---|---|
| Extra monthly principal | Shrinks the loan faster | Any amount you choose | Money is locked in the house |
| One extra payment a year | Adds roughly one payment to principal | About $2,023 on the example loan | Same lock-in, easy to automate |
| Shorter loan term | Higher principal share from day one | Higher required payment | Less budget flexibility |
| Larger down payment | Higher starting equity | Cash up front | Less cash left after closing |
| Mortgage recast (if offered) | Lowers payment after a lump sum | Servicer fee, varies | Not every loan or servicer allows it |
| Home improvements | May raise value | Project cost | Cost often exceeds value added |
| Waiting for prices to rise | Market-driven gain | None | Not guaranteed and not in your control |
The row to watch is home improvements. A project that costs $30,000 does not necessarily add $30,000 of market value, and a buyer in your market may not pay for it. Treat improvements as a way to use or enjoy the home, and count any value gain as a bonus.
One extra payment a year on the example loan cuts 70 months from the schedule and about $93,073 of interest. It is a simple habit if you set it up as a standing extra amount equal to one-twelfth of the payment.
Home Equity vs What You Would Actually Net
Equity is a paper number at today’s estimated value. If you sell, a chunk of it never reaches you. Sellers typically pay a real estate agent, closing costs, transfer taxes where they apply, repairs, and moving costs. These vary by market and by deal, so the percentages here are illustrative.
Take the Home A example again: a $400,000 sale price and a $290,000 payoff, so $110,000 of paper equity.
| Selling costs (assumed) | Dollar cost | Cash left after payoff | Share of paper equity |
|---|---|---|---|
| 6% of price | $24,000 | $86,000 | 78.2% |
| 8% of price | $32,000 | $78,000 | 70.9% |
| 10% of price | $40,000 | $70,000 | 63.6% |
The practical lesson: when you plan a move, subtract selling costs before you count equity toward the next down payment. A homeowner who budgets the full $110,000 and nets $78,000 has a gap of $32,000 to fill. Our closing costs guide lists the line items buyers and sellers should expect on the settlement statement.
Taxes on a sale
Federal law lets many homeowners exclude part of the gain on the sale of a main home. The IRS says you may exclude up to $250,000 of gain, or up to $500,000 on a joint return, if you meet the ownership and use tests. Both require that you owned and lived in the home for at least 24 months of the five years before the sale (IRS Topic 701). Gain is not the same as equity, because it depends on what you paid and the improvements you made. The IRS directs readers to Publication 523 for how to compute it.
Equity and your net worth
Counting equity in your net worth is reasonable. Counting it as spendable savings is not. If your household budget depends on equity staying available, a falling market or a tightening lender can remove the option overnight. Our monthly budget guide shows how to plan cash flow without relying on borrowing.
Tappable Equity: How Much You Can Actually Borrow
Tappable equity is the amount of equity a lender will let you borrow against while you keep a required cushion. It is always smaller than total equity. The cushion is set by the lender’s maximum combined loan-to-value ratio (CLTV).
The formula has two steps:
- Multiply the home’s value by the lender’s maximum CLTV. That gives the most total debt the lender will allow.
- Subtract what you already owe. What remains is the borrowing room.
On Home A at an 80% cap: 0.80 times $400,000 is $320,000. Minus the $290,000 first mortgage leaves $30,000 of tappable equity. Your total equity is $110,000, but only about 27% of it is available to borrow.

Where the 80% figure comes from
Fannie Mae’s published eligibility matrix is dated August 5, 2026. It sets the maximum LTV, CLTV and home equity CLTV (HCLTV) at 80% for a cash-out refinance. That applies to a one-unit principal residence underwritten through its automated system. By contrast, the same matrix allows up to 97% on a fixed-rate purchase. The gap shows how much more cautious lenders are when a borrower pulls cash out.
That is a rule for loans sold to Fannie Mae. It does not bind every lender. A home equity loan or line from a bank or credit union follows that lender’s own limits. Some lenders go higher or lower depending on credit score, income and property type. Government-backed loans such as FHA and VA mortgages have their own programs. Ask each lender for its maximum CLTV in writing before you pay for an appraisal.
How different homes compare
The table applies three common caps to four illustrative homes. All have a $400,000 value.
| Home (illustrative) | Owed | Equity | Tappable at 80% | Tappable at 85% | Tappable at 90% |
|---|---|---|---|---|---|
| Home A | $290,000 | $110,000 | $30,000 | $50,000 | $70,000 |
| Home B | $355,000 | $45,000 | $0 | $0 | $5,000 |
| Home C | $410,000 | -$10,000 | $0 | $0 | $0 |
| Home D | $180,000 | $220,000 | $140,000 | $160,000 | $180,000 |
Two things stand out. Each five-point increase in the allowed CLTV adds $20,000 of borrowing room on a $400,000 home, so the lender’s cap matters as much as your equity. And a homeowner with 11% equity, like Home B, may have no room at all under a typical cap.
Why the appraisal can shrink your room
Borrowing room depends on the appraised value, not the value you assumed. Suppose Home A appraises at $370,000, which is 7.5% lower. At an 80% cap the lender allows $296,000 of total debt, so your room falls from $30,000 to $6,000. At $360,000 the cap is $288,000, which is below your current mortgage. The room is gone.
That is a 10% appraisal gap erasing a $30,000 plan. It is also why a lender can later cut a HELOC’s credit limit after a market decline, which we cover in the rules section.
National context
The Federal Reserve’s Financial Accounts were released September 11, 2026. They show households owned about $49.8 trillion of real estate at the end of the second quarter of 2026. Against that, about $14.0 trillion of one-to-four-family mortgage debt was outstanding, a figure that includes home equity loans and lines. Those totals imply a large aggregate cushion. But they average the whole country. They say nothing about whether your home, in your market, with your lender’s rules, has any room to borrow.
Credit and cost checks that apply
Applying for a loan or line usually triggers a hard credit inquiry. Our hard inquiry guide explains the score impact and how rate shopping within a short window is generally treated. The lender will also review your income and debts. Our credit underwriting guide walks through that process.
Ways to Use Home Equity: The Main Options Compared
Once you know your tappable amount, you have five broad routes to turn equity into cash. They are a home equity loan, a HELOC, a cash-out refinance, a reverse mortgage for older owners, and selling. Each has a different cost structure and a different way to go wrong. All but the last keep the debt secured by your home.
Let’s walk through each, then compare them on the same criteria.
Home equity loan
A home equity loan, sometimes called a second mortgage, is secured by your home and paid out as one lump sum. The FTC describes it as usually carrying a fixed APR with equal monthly payments over a set term (FTC consumer advice, updated December 9, 2025). It sits behind your first mortgage, which stays in place.
The structure suits a single, known expense: a roof, a medical bill, a one-time payoff. You know the payment from day one, and the rate does not change. The downside is that you pay interest on the full amount from the start, whether or not you have spent it.
Because it is a closed-end loan secured by real property, the lender must send a Loan Estimate. The deadline is three business days after it receives your application (12 CFR 1026.19). The federal ability-to-repay rules also apply: the lender must consider your income or assets, debts, credit history and the monthly payment (12 CFR 1026.43).
Home equity line of credit
A HELOC is a revolving line secured by your home, similar to a credit card. The FTC says it usually has a variable APR, with interest owed only on what you borrow. A draw period comes first, when you can borrow and repay repeatedly. A repayment period follows, when you can no longer borrow and the balance amortizes.
That structure suits uneven costs, such as a renovation paid in stages or a cushion for irregular expenses. It also creates a risk that fixed loans do not have. The payment can climb in two ways: when rates rise and when the repayment period begins.
Many lenders tie a HELOC’s rate to the prime rate plus a margin, and your agreement names the index. The Federal Reserve’s H.15 release, published October 14, 2026, listed the bank prime loan rate at 7.00% for October 13, 2026. The margin depends on the lender and your profile, so the calculations later in this guide use an illustrative margin.
Cash-out refinance
A cash-out refinance replaces your first mortgage with a larger one and pays you the difference. Fannie Mae’s matrix caps these at 80% of value for its standard loans. You get one new payment, one new rate and, usually, a new 30-year clock.
The deciding variable is your current mortgage rate. If it is far below today’s rates, a cash-out refinance reprices the whole balance upward to fund a smaller cash need. If it is higher than current rates, the same transaction can lower your cost and give you cash. Our mortgage rate lock guide covers how to protect a rate while the loan closes, and the mortgage closing timeline shows what the process looks like.
Reverse mortgage
A reverse mortgage is for homeowners aged 62 and older. The CFPB says these loans generally must be repaid when you sell or no longer live in the home. The balance grows over time rather than shrinking. Failing to pay property taxes or homeowner’s insurance, or to maintain the home, can bring the loan due sooner (CFPB).
The product is not a general-purpose answer for most owners. It fits a narrow situation: an older owner who plans to stay, has substantial equity, and needs income or a payment-free option. Talk to a HUD-approved housing counselor before considering one.
Selling or downsizing
Selling is the only route that turns equity into cash without adding debt. It also costs the most in transaction fees and may trigger taxes above the exclusion limits. It fits when your housing needs have changed, not when you want a short-term cash bridge.
Comparison Table: Same Criteria for Every Option
The table compares the options on identical criteria. No row wins in every column, which is why the choice depends on the purpose and your current mortgage.
| Option | How you receive money | Rate type | Payment pattern | Main risk | Best fit |
|---|---|---|---|---|---|
| Home equity loan | One lump sum | Usually fixed | Equal payments, set term | Home is collateral; interest on full amount | One-time, known expense |
| HELOC | Draw as needed | Usually variable | Interest-heavy draw, then repayment | Payment jumps; line can be cut | Staged or uncertain costs |
| Cash-out refinance | Lump sum at closing | Fixed or adjustable | One new first-mortgage payment | Reprices the whole mortgage; resets the term | Current mortgage rate is high |
| Reverse mortgage (62+) | Varies by product | Varies by product | Repaid when you sell or leave the home | Balance grows; taxes and insurance still due | Older owner staying long term |
| Sell or downsize | Cash at closing | Not applicable | None | Selling costs; moving; taxes | Housing needs have changed |
Notice the first three rows. All three borrowers can lose the home if they stop paying, yet they differ sharply in rate risk and in what happens to the existing mortgage. The right row depends first on your first mortgage’s rate and second on whether you need money once or over time.
What the Rules Say: Law, Lender Policy and Your Contract
Federal rules give you some protections and leave others to the contract. Keep three layers separate: federal law (Regulation Z), lender policy (what a particular lender decides), and your agreement (the terms you sign).
Right to cancel
For a loan or line secured by your main home, you generally can rescind until midnight of the third business day. The clock starts at the latest of three events: the transaction, delivery of the notice, or delivery of the material disclosures. If you do, the security interest becomes void and you owe nothing, including finance charges (12 CFR 1026.23 for loans; 12 CFR 1026.15 for lines).
The lender must return money and take steps to end the lien within 20 calendar days after receiving your notice. If required notices or disclosures were never delivered, the right can last up to three years, or until you sell or transfer your interest, whichever comes first. The FTC adds practical points: the right does not cover vacation or second homes, and you must cancel in writing, not by phone.
Exemptions matter. A purchase mortgage is exempt, and so is a same-lender refinancing, except to the extent the new amount exceeds the old balance plus refinancing costs. With a HELOC, you can rescind the opening of the plan and a credit limit increase, but not each later draw under an established limit.
Limits on what a HELOC lender can do
Regulation Z restricts changes to HELOCs. A lender may change the APR only if the change is based on a publicly available index that is outside its control. It may terminate the plan and demand the full balance only for specified reasons. Examples are fraud, failure to meet repayment terms, or action that harms its security. It may also stop further advances or reduce the credit limit. That is allowed when the home’s value declines significantly below its appraised value for the plan (12 CFR 1026.40(f)).
That last permission is what turns a market downturn into a cash-flow problem. A line you counted on can shrink when you most need it. Treat an open HELOC as a convenience, not as an emergency fund.
Fees and disclosures
Under the same section, a lender must give you the home equity brochure and disclosures when it provides the application. Nobody may impose a nonrefundable fee until three business days after you receive them. Suppose a disclosed term changes before the plan opens and you decide not to open it. The lender must then refund fees you paid in connection with the application.
High-cost mortgage protections
Regulation Z also sets a high-cost mortgage category with extra restrictions. A loan secured by your principal dwelling is covered if its APR is too far above the average prime offer rate for a comparable transaction. The gap is more than 6.5 percentage points on a first lien or 8.5 points on a subordinate lien. Points and fees above 5% of the loan amount also trigger coverage for loans of $20,000 or more. Prepayment penalties longer than 36 months, or above 2% of the amount prepaid in total, also trigger coverage (12 CFR 1026.32). The dollar threshold for smaller loans adjusts each year.
The table summarizes where each rule comes from and what you should do.
| Rule | Source | Applies when | Exception or limit | Your action |
|---|---|---|---|---|
| Three-day right to cancel | Federal (Reg Z 1026.15, 1026.23) | Loan or line secured by your main home | Purchase loans; same-lender refinances; second homes | Keep the notice; cancel in writing |
| Nonrefundable fees wait three business days | Federal (1026.40) | HELOC applications | Applies after disclosures delivered | Ask when fees are charged |
| Line freeze or limit cut | Federal permission (1026.40(f)); lender policy applies it | Value falls significantly below appraisal | Specific triggers only | Read the agreement; keep other credit |
| Ability to repay | Federal (1026.43) | Closed-end loans secured by a dwelling | HELOCs are exempt | Expect income and debt checks |
| High-cost mortgage limits | Federal (1026.32) | APR or fees over thresholds | Some programs exempt | Compare APR and fees across lenders |
| Maximum CLTV | Lender policy | Every application | Varies by lender and borrower | Ask for it in writing |
What Borrowing Costs: Four Worked Scenarios
The sticker rate rarely tells the whole story. Term length, fees, and what happens to your existing mortgage change the total. The four scenarios below use round numbers and illustrative rates. None is a quote, and none reflects a rate any lender is offering today.
Scenario 1: A $40,000 fixed-rate loan
Assume a $40,000 loan at an illustrative 8.50% fixed rate. Closing costs of $1,200 (3%) come out of your pocket. The term is the choice that moves the numbers most.
| Term | Monthly payment | Total interest | Total repaid |
|---|---|---|---|
| 10 years | $495.94 | $19,513 | $59,513 |
| 15 years | $393.90 | $30,901 | $70,901 |
| 20 years | $347.13 | $43,311 | $83,311 |
Stretching from 10 to 20 years cuts the payment by about $149 a month but adds roughly $23,800 in interest. Pay $1,200 in fees on the 15-year version and the effective cost rises to about 9.0% a year. That treats the fees as a reduction in what you actually receive. Compare lenders on APR and fees, not only on the headline rate.
Choose the shortest term whose payment your budget can carry in a bad month. A longer term feels cheaper, yet it is the expensive route.
Scenario 2: A HELOC and the payment jump
Now assume a $40,000 balance on a HELOC. Prime is 7.00% as of October 13, 2026, and we add an illustrative margin of 1.00 point, for an 8.00% rate. The line has a 10-year draw period followed by a 20-year repayment period.
During the draw period, an interest-only payment on $40,000 at 8.00% is $266.67 a month. When repayment begins, a fully amortizing payment over 20 years at the same rate is $334.58, a jump of $67.91, or 25.5%. After 10 years of interest-only payments you would have paid $32,000 and still owe the full $40,000.
Rates also move. The table shows what happens if the rate rises while the balance stays at $40,000.
| Rate on the line | Interest-only payment (draw) | Fully amortizing payment (20-year repayment) |
|---|---|---|
| 8.00% | $266.67 | $334.58 |
| 9.00% | $300.00 | $359.89 |
| 10.00% | $333.33 | $386.01 |
| 11.00% | $366.67 | $412.88 |

Three percentage points of rate increase would raise the interest-only payment by $100 a month. The repayment-period payment would end up $78.30 above the 8.00% starting level. The bigger practical risk is the combination: a balance you never paid down, a higher rate, and a repayment clock starting together. If you use a HELOC, pay some principal during the draw period when you can.
Scenario 3: Cash-out refinance versus keeping your low rate
This is the comparison that most often changes the answer. Assume you owe $290,000 at 3.25% with 25 years left, and the home is worth $400,000. You need about $23,500 in cash.
Option A, cash-out refinance: a new $320,000 loan (80% of value) at an illustrative 6.75% over 30 years, with $6,500 of closing costs rolled in. After costs, cash to you is $23,500.
Option B, keep the first mortgage and add a second: the existing loan stays. You add a $24,000 home equity loan at an illustrative 8.50% over 15 years with $500 in costs, which leaves $23,500 as well. Combined LTV is 78.5%.
| Item | A: Cash-out refinance | B: Keep first + second loan |
|---|---|---|
| Loans after closing | One loan, $320,000 | $290,000 at 3.25% plus $24,000 at 8.50% |
| Monthly payment | $2,075.51 | about $1,650 ($1,413.22 + $236.34) |
| Closing costs | $6,500 | $500 |
| Interest over first 5 years | $104,933 | $53,194 |
| Balance after 5 years | $300,402 | $268,220 |
| Five-year cost gap | About $57,740 higher (interest plus costs) | Baseline |
Option B is cheaper by about $426 a month and about $57,740 over five years in interest and costs. The reason is simple: the refinance reprices $290,000 from 3.25% to 6.75% to fund a $23,500 need. The blended rate on Option B is about 3.65%.
The logic reverses if your current mortgage rate is high. A cash-out refinance can then lower the cost of the old debt and fund the cash need in one move. Run both options with real quotes before you decide.
Scenario 4: Paying off credit cards
Suppose you owe $20,000 on cards at an illustrative 24% APR. Interest runs about $4,800 a year, or $400 a month. Borrowing the same amount against your home at 8% costs about $1,600 a year in interest, so year-one interest falls by roughly $3,200.
That is attractive on paper. It comes with two catches. First, you convert unsecured debt into debt secured by your home, which raises the stakes of a missed payment. Second, the savings disappear if the cards fill up again.
If you take a 10-year fixed loan at 8%, the payment is $242.66 and the total interest is $9,119. Note that $242.66 is less than the $400 of monthly interest the cards would charge, which shows how much the rate difference matters. Our guides to credit card debt and the debt consolidation loan cover unsecured alternatives.
Taxes: When Interest Is Deductible
Many borrowers assume home equity interest is always deductible. It is not. The IRS states in Publication 936 (2025) that interest on home equity loans and lines is deductible only in one case. The borrowed funds must be used to buy, build or substantially improve the home that secures the loan. The rule applies no matter when the debt was incurred. The deduction also requires that you file Form 1040 or 1040-SR and itemize on Schedule A (IRS Publication 936).
The same publication caps the qualifying debt at $750,000 ($375,000 if married filing separately) for debt taken out after December 15, 2017. Older debt has higher limits.
Here is what that means in dollars. On the $40,000 loan at 8.50% over 15 years from Scenario 1, first-year interest is about $3,347. In the 22% federal bracket, the best case is a tax saving near $736, and only if you itemize and your itemized total beats the standard deduction. Spend the same money on a vacation or a card payoff and the interest is not deductible at all.
Confirm the current rules with a tax professional before you rely on a deduction. Our guide to financial and tax forms lists the forms involved.
A Decision Framework: Should You Tap Your Equity?
Borrowing against your home is a secured, long-lived commitment. A five-step test keeps the decision honest. Work through it in order and stop at the first step that fails.
- Name the purpose and the amount. A one-time cost points to a lump sum. An uneven or uncertain cost points to a line. If you cannot name the amount, you are not ready.
- Measure tappable equity conservatively. Use your value estimate minus 10%, then apply the lender’s CLTV cap. If the plan only works at the high number, shrink it.
- Compare your first mortgage rate with today’s rates. A rate far below the market argues for leaving the first mortgage alone and adding a second loan or line. A rate above the market makes a cash-out refinance worth pricing.
- Stress-test the payment. Raise the HELOC rate by three points, include the start of repayment, and cut household income by 10%. If the payment still fits, continue.
- Check the alternatives and the exit. Compare savings, a personal loan, a smaller project or selling. Ask what happens if you must move in two years.

The unsecured alternatives are worth a look because they put no lien on the house. Our guides on personal loan rates and the broader types of loans show where they fit. Our guide to when to take out a loan walks through the decision from the other side.
What you plan to spend it on
Purpose affects both risk and taxes. The table uses the federal rule from Publication 936 for the interest question.
| Purpose | Interest deductible under home mortgage rules? | Main risk | Better question to ask |
|---|---|---|---|
| Major repair or remodel of this home | Possibly, if you itemize and stay within limits | Cost overruns; value gain may be small | Is the work needed, and are bids fixed? |
| Paying off credit cards | No | Cards refill; debt becomes secured | What changes so the balance does not return? |
| Medical or emergency bill | No | Borrowing against the home for a one-time cost | Can the provider offer a payment plan first? |
| Vacation, wedding, or a car | No | Long debt for a short benefit | Can I save for it instead? |
| Down payment on another property | No for the borrowed funds | Two mortgages; rescission rights may not apply | How would I pay both if one income fell? |
The last row deserves emphasis. Lenders on the second purchase count your new payment, and the FTC notes the right to cancel does not extend to vacation or second homes.
Private Mortgage Insurance and Equity
If you bought with less than 20% down, you may pay private mortgage insurance (PMI), and your equity is what ends it. Under federal rules, you can ask your servicer to cancel PMI when the balance is scheduled to reach 80% of the home’s original value. Servicers must end it automatically when the balance is scheduled to reach 78%, if you are current (CFPB).
“Original value” is the lower of the contract price or the appraised value at purchase. A rising market does not change that on its own, though some lenders allow cancellation on a new appraisal under their own rules. Ask your servicer.
For a $360,000 loan on a $400,000 home at 6.50%, the 80% mark ($320,000) arrives in month 95, about 7.9 years in. The 78% mark ($312,000) arrives in month 109, about 9.1 years in. Extra principal payments pull both dates earlier.
Borrowing can get in the way
The CFPB lists conditions for a borrower-requested cancellation. You need a written request, a good payment history, no junior liens, and proof that the value has not fallen below the original. A new home equity loan or line is a junior lien. Taking one out before your PMI ends can complicate the request. Sequence matters, so cancel the PMI first when you can.
Risks, Mistakes and Red Flags
The biggest risk is simple. Every option except selling puts a lien on your home. The FTC is blunt that if you do not repay as agreed, the lender can foreclose. Beyond that, a handful of specific mistakes show up repeatedly.
Common mistakes
- Borrowing the maximum. The cap is a ceiling set for the lender’s protection, not a target for you.
- Treating a HELOC as an emergency fund. The lender can freeze or cut the line after a significant drop in value.
- Ignoring the repayment-period payment. The payment you pay today is not the payment you will pay later.
- Using a high-priced value. A generous estimate can leave you with a smaller loan than planned after the appraisal.
- Refinancing a low-rate first mortgage for a small cash need. Scenario 3 showed the cost.
- Skipping the fees. Origination, appraisal, annual and early-closure fees change the true cost.
- Forgetting the house itself. A bigger loan raises what is at stake if the home is damaged, so review your coverage and your deductible. Our homeowners insurance deductible guide covers that side.
Red flags to look for
| Red flag | Why it matters | What to ask | Safer next step |
|---|---|---|---|
| Quote shows a payment but no APR, index or margin | You cannot compare lenders | Which index, what margin, and what is the APR? | Request a written disclosure from each lender |
| Pressure to borrow the full limit | Larger debt and payment | What does the payment look like at a lower amount? | Borrow what the project needs |
| A nonrefundable fee requested before you receive disclosures | Federal rules bar it for HELOCs until three business days after you get them | When is each fee charged and is it refundable? | Wait for disclosures before paying |
| Request to waive the three-day cancellation period | You lose a protection | Is there a genuine emergency? | Do not waive unless needed; the FTC says waiver takes a signed, dated statement |
| Prepayment penalty or early-closure fee | Limits your ability to refinance or sell | How long, how much, and how is it calculated? | Choose a product without one or price it in |
| Closing instructions changed by email | Wire-fraud pattern the FTC warns about | Can I confirm by phone? | Call a number you already know before wiring |
| Interest-only or balloon structure | Payment shock later | What is the payment after the draw period? | Model it before signing |
Edge Cases and Exceptions
A few situations change the usual rules.
Second homes and investment properties. The right to cancel covers loans secured by your principal dwelling. Lender limits for other properties are usually tighter, so ask for property-specific terms.
Joint owners. Each person whose ownership interest is subject to the lien may have rescission rights. Expect the lender to want every owner on title involved, and talk it through before you apply.
Recently purchased homes. Lenders often want some time between purchase and a cash-out loan, and many look at how recently a first mortgage was originated. Ask about any waiting period.
Falling markets. If values drop after you open a line, the lender can restrict or reduce it. A smaller line plus a separate cash reserve gives you more room than a maxed-out one.
Paying off a loan early. After you pay off a home equity loan or line, make sure the lender releases the lien and gives you proof. An unreleased lien can surface at your next sale.
Documents and Questions to Bring
Gather these before you apply. The same file protects you later.
| Document | Why it matters | Where to get it | How long to keep |
|---|---|---|---|
| Mortgage payoff statement | Feeds the equity calculation | Your servicer | Until the loan is paid and the lien released |
| Appraisal or valuation report | Shows the value the lender used | The lender | Through the life of the loan |
| Loan Estimate or HELOC disclosures | Lets you compare terms and fees | The lender | Through the life of the loan |
| Signed agreement and right-to-cancel notice | Proves the dates and terms | Closing | Through the life of the loan, plus any dispute |
| Receipts for home improvements | Supports tax treatment and basis | Contractors and suppliers | Ask a tax professional |
| Lien release after payoff | Proves the debt is cleared | The lender | Keep indefinitely with title records |
- ☐ What is your maximum combined loan-to-value ratio, and do you count the full credit limit or only the drawn balance?
- ☐ What is the APR, and which fees are included in it?
- ☐ Is the rate fixed or variable, and if variable, what are the index, margin, caps and floor?
- ☐ What is the payment during the draw period and the repayment period?
- ☐ When does the repayment period begin, and can I pay principal early?
- ☐ Which fees are charged at application, closing, annually and at closing the line, and which are refundable?
- ☐ Is there a prepayment penalty or early-termination fee, and for how long?
- ☐ Under what conditions can you freeze or reduce the line?
- ☐ Will you send the disclosures before I pay any nonrefundable fee?
- ☐ How and when will you release the lien after I pay it off?
Frequently Asked Questions
How do I calculate my equity quickly?
Subtract your total payoff balances from your best estimate of the home’s market value. A $400,000 home with a $290,000 mortgage has $110,000 of equity. Divide that by value to get 27.5%. Use payoff figures from your servicer, include every lien, and test the result at a value 5% to 10% lower. A lender’s appraisal, not your estimate, decides what you can borrow.
Is home equity the same as home value?
No. Value is the full price a buyer might pay. Equity is what remains after secured loans are subtracted. Two houses worth $500,000 can have equity of $350,000 and $50,000. The first owner has far more flexibility to borrow, sell or absorb a price drop. Only equity, not value, measures your ownership stake.
How much of my equity can I borrow?
It depends on the lender’s maximum combined loan-to-value ratio, and it is usually less than your full equity. At an 80% cap on a $400,000 home with $290,000 owed, you could borrow about $30,000. Fannie Mae’s August 5, 2026 matrix uses 80% for standard cash-out refinances. Banks and credit unions set their own limits, so ask for yours in writing.
How fast does equity build?
Slowly at first. On a $320,000 loan at 6.50% over 30 years, only $289.28 of the first $2,022.62 payment reduces the balance. About $3,577 of principal is repaid in year one. Price changes can add or subtract far more. Extra principal payments and a larger down payment speed things up, while a price decline can reverse years of progress.
Does building equity remove private mortgage insurance?
It can, but not automatically on rising prices. Under federal rules, you can ask to cancel PMI when your balance is scheduled to reach 80% of the original value. The servicer must end it at 78% if you are current. A junior lien, such as a new home equity loan, can complicate a request. Ask your servicer how it handles new appraisals.
Is the interest on a home equity loan or line tax deductible?
Only in limited cases. The IRS says interest on home equity loans and lines is deductible only in one case. You must use the money to buy, build or substantially improve the home that secures the loan. You also must itemize. Interest on money used for cards, tuition or a vacation is not deductible under these rules. Check current rules with a tax professional.
Will borrowing against my equity hurt my credit score?
It can, modestly and in different ways. Applying usually produces a hard inquiry, and a new loan or line adds debt and a new account. Missed payments hurt much more than the inquiry. Our hard inquiry guide explains the effect, and the credit score guide covers how scores respond to new accounts.
Can I cancel after I sign?
Often yes, for a few days. If the loan or line is secured by your main home, you generally have until midnight of the third business day to cancel in writing. The right does not cover vacation or second homes, and purchase loans are exempt. If required disclosures were not delivered, it can last up to three years. Keep the notice and send your cancellation in writing.
What happens to my equity if home prices fall?
It shrinks dollar for dollar, and faster as a percentage. With $110,000 of equity on a $400,000 home, a 10% price drop leaves $70,000, a 36.4% loss of equity. A lender can also freeze or reduce a HELOC if the value falls significantly below the appraised value. Falling prices therefore hurt twice: your net worth and your borrowing room.
Which is cheaper, a HELOC or a home equity loan?
Neither always wins. A fixed-rate loan costs more at the start if you only need money in pieces, because you pay interest on the full amount. A HELOC can cost less early but carries rate risk and a repayment-period jump. Compare the APR, fees, and the payment after the draw period for the amount you will actually use.
What can I do if I have little or no equity?
You still have options. Build equity with extra principal, wait for the market, or use unsecured credit, which puts no lien on your home. Check programs through a HUD-approved housing counselor if payments are a struggle. Avoid borrowing against a thin cushion for non-essential spending, and keep an emergency fund so a bill does not push you to borrow.
Calculate your equity today: get a payoff quote for every loan against the home, estimate value at 90% of your high number, and apply an 80% cap. If the room that remains does not cover your plan, change the plan before you apply.
The variable that decides your outcome is the appraised value measured against your total secured debt. It sets your equity, your combined loan-to-value ratio, and how much room a lender will give you, which is usually far less than the full equity number. Calculate it conservatively, then match the tool to the need. Use a fixed loan for a known cost, a line for uneven costs, and a cash-out refinance mainly when your current mortgage rate is not already low. Stress-test the payment, read the fees, and keep the three-day cancellation window if it applies. Equity does not guarantee approval, does not protect you from foreclosure if payments stop, and does not make a line of credit an emergency fund. Confirm current terms with the lender and, for the interest deduction, with a tax professional.
Methodology
We built this guide from primary and official sources and checked each dated figure on October 15, 2026. Federal rules come from Regulation Z as published in the eCFR text mirrored by Cornell Law School. Consumer explanations come from the FTC and the CFPB. Tax rules come from IRS Publication 936 (2025) and Topic 701. The 80% cash-out limit comes from Fannie Mae’s Eligibility Matrix dated August 5, 2026. The 7.00% prime rate (October 13, 2026) comes from the Federal Reserve’s H.15 release, and aggregate household figures come from the Federal Reserve’s Z.1 release of September 11, 2026.
Every home value, loan balance, interest rate, margin, fee, selling cost and card rate in the examples is an illustrative assumption, not a quote or a live offer. We ran the calculations in a script and rechecked them. Lender caps, fees, rates and state rules vary by lender, borrower, property and date. We did not test any lender, product or tool.
Sources
- Home equity loans and home equity lines of credit, FTC consumer advice, December 9, 2025
- 12 CFR 1026.40, Requirements for home equity plans, Cornell Law School
- 12 CFR 1026.15, Right of rescission (open-end), Cornell Law School
- 12 CFR 1026.23, Right of rescission (closed-end), Cornell Law School
- 12 CFR 1026.32, Requirements for high-cost mortgages, Cornell Law School
- 12 CFR 1026.43, Minimum standards for transactions secured by a dwelling, Cornell Law School
- 12 CFR 1026.19, Certain mortgage and variable-rate transactions, Cornell Law School
- When can I remove PMI from my loan, CFPB
- Reverse mortgages, CFPB
- Publication 936, Home Mortgage Interest Deduction (2025), IRS
- Topic no. 701, Sale of your home, IRS
- Eligibility Matrix, Fannie Mae, August 5, 2026
- Financial Accounts of the United States, Z.1, table S1M.b, Federal Reserve, September 11, 2026
- Selected Interest Rates, H.15, Federal Reserve, October 14, 2026
By the Banktimer Editorial Team · Published
Banktimer is an independent U.S. consumer-finance publication. Our editors draw on primary and official sources first, such as the CFPB, FDIC, Federal Reserve, and FTC, along with statutes, regulations, and providers’ own agreements and fee schedules. Then we add worked examples and decision tools. Our goal is the most useful, best-supported explanation the sources available to us at the time of writing allow.
This article is general information, not legal, tax, investment, insurance, or financial advice, and reading it does not create a professional relationship with Banktimer. Rates, fees, limits, and rules change, and they vary by state, provider, and contract, so confirm current terms with your bank, lender, insurer, or the agency named in the article before you act. Examples are illustrative unless labeled otherwise. Banktimer is not a bank, lender, insurer, or financial advisor, and we are not responsible for decisions or losses that result from relying on this content. For advice about your own situation, talk to a licensed professional.