By the Banktimer Editorial Team · Published
Banktimer is an independent U.S. consumer-finance publication. Our editors draw on primary and official sources first, such as the CFPB, FDIC, Federal Reserve, and FTC, along with statutes, regulations, and providers’ own agreements and fee schedules. Then we add worked examples and decision tools. Our goal is the most useful, best-supported explanation the sources available to us at the time of writing allow.
This article is general information, not legal, tax, investment, insurance, or financial advice, and reading it does not create a professional relationship with Banktimer. Rates, fees, limits, and rules change, and they vary by state, provider, and contract, so confirm current terms with your bank, lender, insurer, or the agency named in the article before you act. Examples are illustrative unless labeled otherwise. Banktimer is not a bank, lender, insurer, or financial advisor, and we are not responsible for decisions or losses that result from relying on this content. For advice about your own situation, talk to a licensed professional.
Mobile check deposit lets you photograph a paper check in your bank’s app and send the image in for credit. The service usually costs nothing. The risk is timing. Your balance may rise in seconds, but your bank decides when you can spend the money, and the check can still come back after that. Cutoff times, account age, deposit size and check type all change the schedule. Plan around your bank’s written availability policy, not the pending balance.
Deposited is not available. A posted deposit can still be on hold. Check the available balance and any hold notice before you spend.
Your agreement sets the schedule. Federal rules give useful benchmarks, but a mobile check deposit agreement is a contract with its own terms.
The app is rarely the expense. Delays, returned-item fees and overdrafts cost more than the free service does.
Available is not final. A fake or altered check can bounce weeks later, and the bank can take the money back.
The paper check is your evidence. Keep it until the deposit posts and your bank’s window ends, then destroy it.
The Numbers That Shape Every Mobile Check Deposit
Regulation CC benchmarks worth knowing
Federal funds-availability rules live in Regulation CC (12 CFR Part 229), issued by the Federal Reserve Board. They set outer limits on how long a bank can hold deposited funds. Congress ordered inflation adjustments every five years, and the latest amounts took effect on July 1, 2025.
The table separates the dollar thresholds from the timing rules, because readers often mix them up. The $275 figure is how much of an ordinary check must be available the next business day. The $6,725 figure is where extra holds become easier for the bank to justify.
| Benchmark | Figure | What it controls | Source |
|---|---|---|---|
| Next-business-day amount | $275 | Portion of ordinary checks available the next business day | 12 CFR 229.10(c)(1)(vii) |
| Standard check schedule | Second business day | Outer limit for most check deposits under the normal schedule | 12 CFR 229.12(b) |
| Large-deposit threshold | $6,725 per banking day | Amounts above it can be held longer | 12 CFR 229.13(b) |
| New-account limit | $6,725 per banking day, first 30 days | Caps next-day treatment of cashier’s and similar checks; ordinary checks fall outside the schedule | 12 CFR 229.13(a) |
| Repeated-overdraft trigger | 6+ negative days in 6 months | Longer holds for six months after the last overdraft | 12 CFR 229.13(d) |
| Earliest branch cutoff | 2 p.m. (noon for ATMs) | Latest a bank may start the day’s cutoff | 12 CFR 229.19(a) |
| Stale-dated check | Six months | Bank need not pay older checks (state law) | UCC 4-404 |
| Next threshold reset | July 1, 2030 | Dollar amounts re-indexed every five years | 89 FR 43737 |
A “new account” means one in its first 30 calendar days, with a carve-out for existing customers explained in the holds section.
Why your bank’s agreement matters more than the regulation
Here is the catch. Regulation CC’s schedule was written around deposits made at branches and ATMs. Lawyers have long debated whether a photo sent through an app counts as that kind of deposit. A January 2026 America’s Credit Unions compliance article still says remote deposit “does not seem to fit within the strict reading” of the rule’s definition of a check deposit. That leaves contracts and state law to fill the gap.
Banks answer the question differently. Capital One’s mobile deposit agreement says eligible items “are not subject to the funds availability requirements of Regulation CC.” The CFPB’s consumer page says only that your bank “may have a different timetable” for phone deposits.
So treat the table above as benchmarks, not promises. Many banks promise something close to the regulation, and some promise faster. Your deposit agreement and funds availability disclosure decide your schedule.
Three Clocks Start When You Tap Deposit
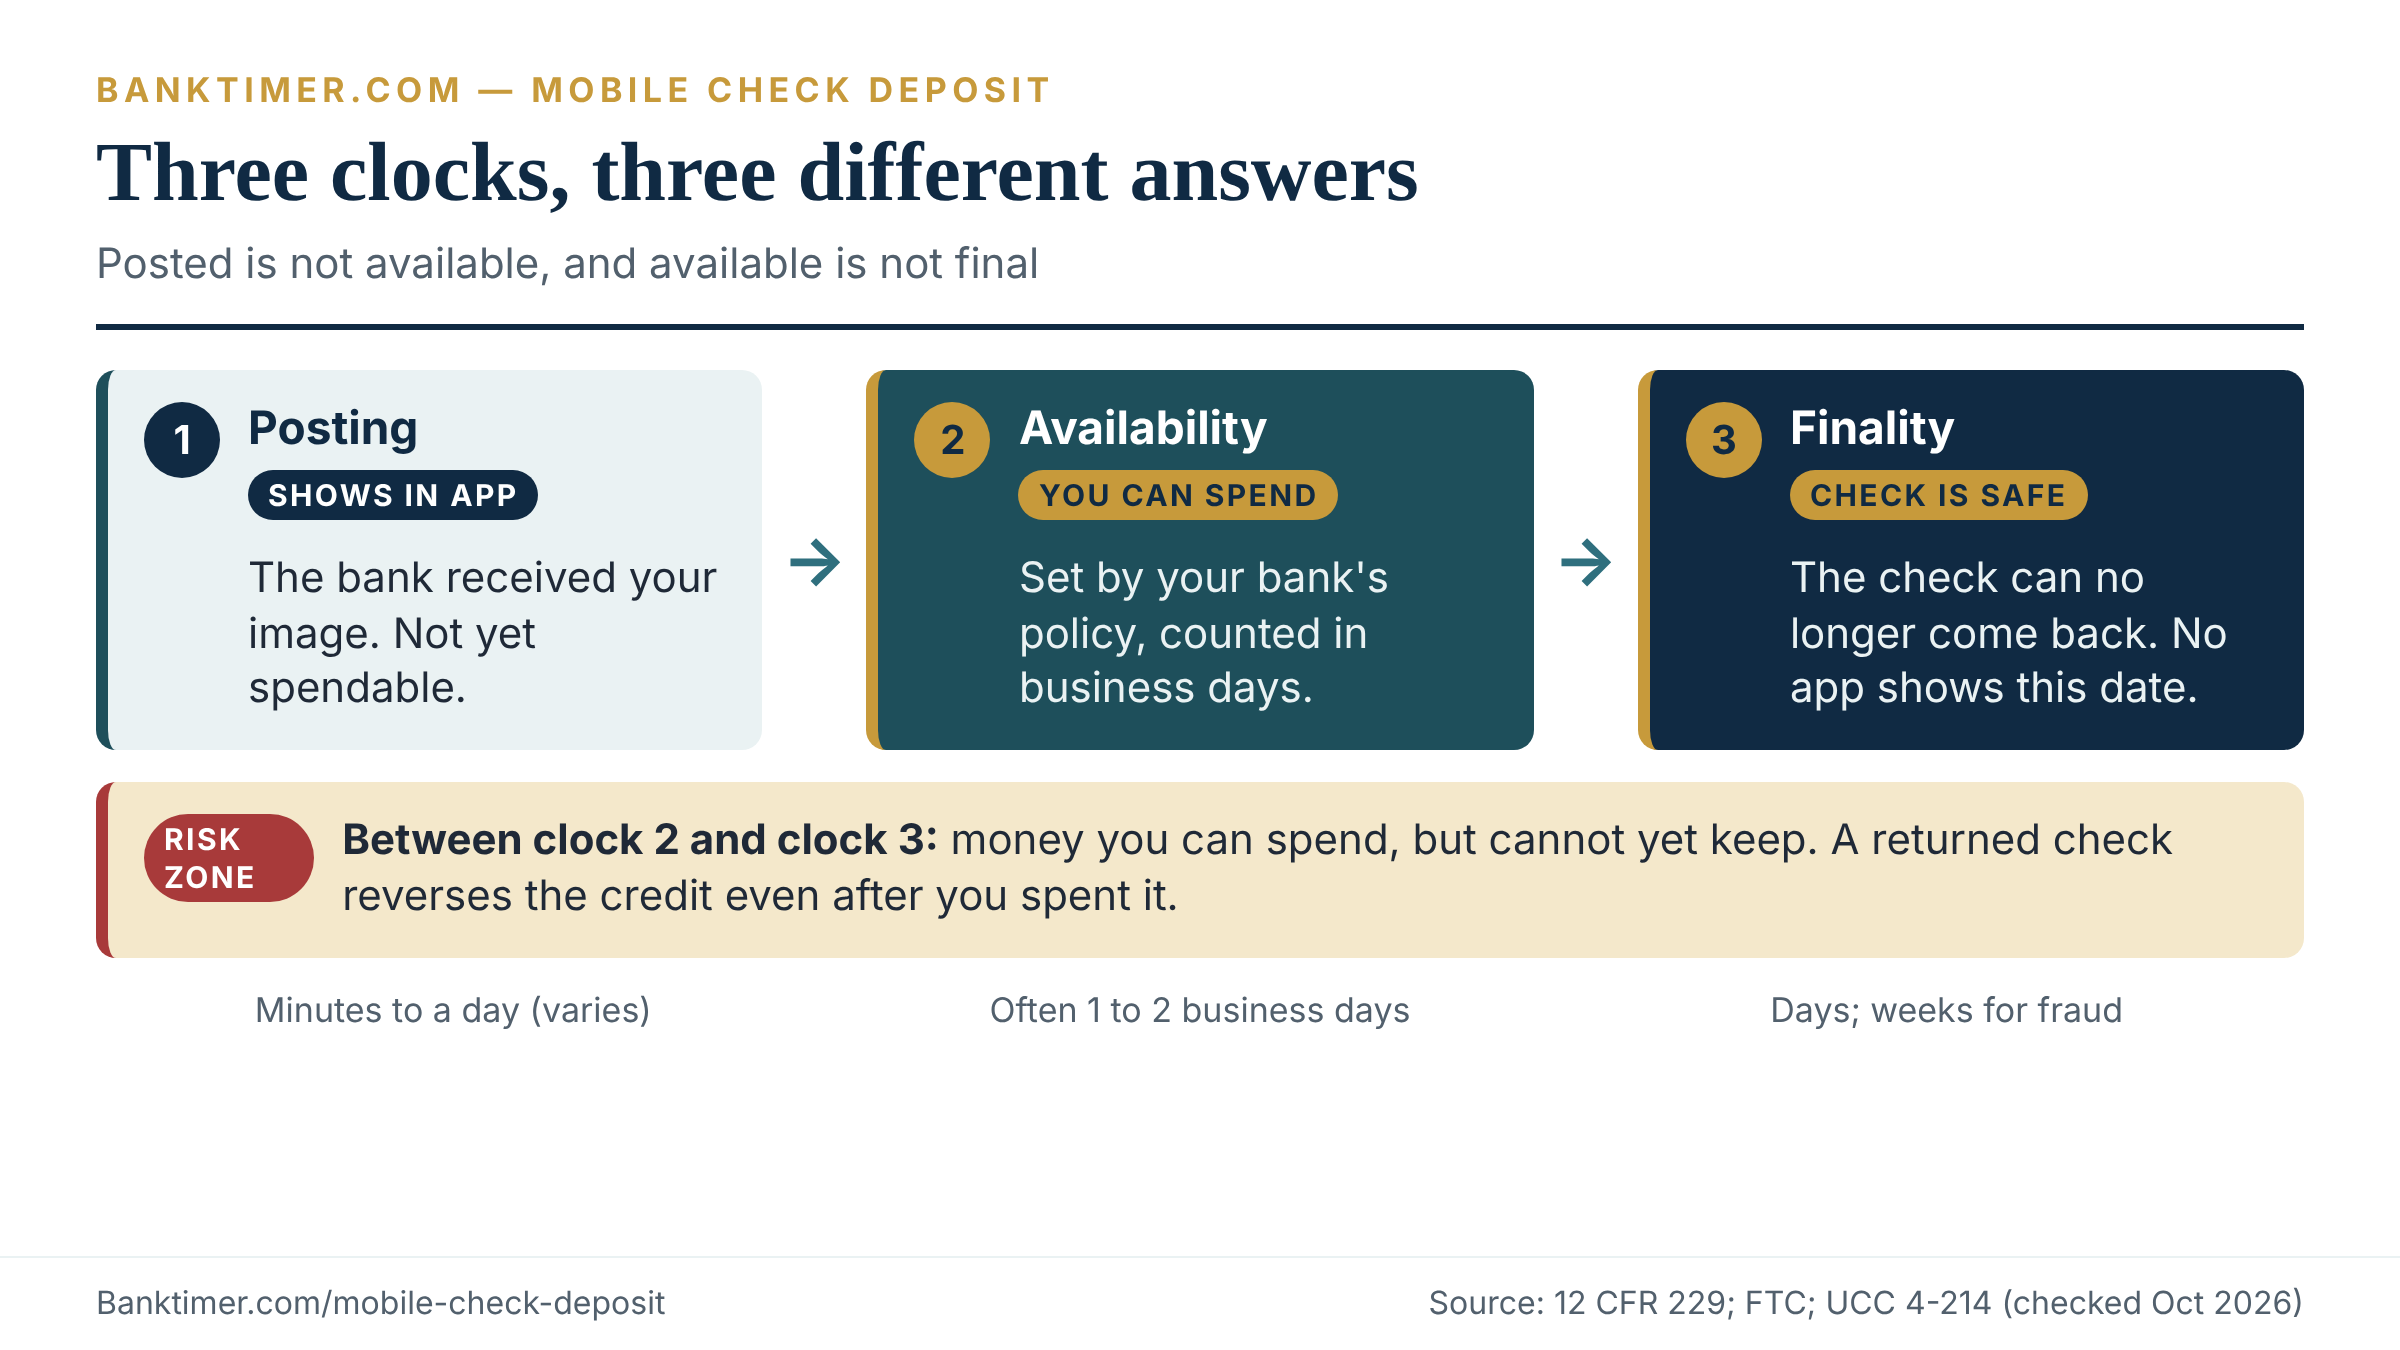
Every mobile check deposit runs three clocks at once. Most confusion comes from reading one clock as if it were another.
Clock one: posting
Posting is when your app shows the deposit. Many banks show it as pending within minutes. Others wait for an overnight review.
Pending means the bank received your image. It does not mean the bank accepted the check or released the funds. Your ledger balance may include the deposit while your available balance does not. Only the available balance tells you what you can safely spend.
Clock two: availability
Availability is when the money becomes yours to use. Your bank’s funds availability policy sets it, and the policy counts business days, not calendar days.
Banks that mirror Regulation CC often release the first $275 the next business day and the rest by the second. Some release faster. Wells Fargo’s Everyday Checking fee schedule, effective July 28, 2026, says up to $400 of a day’s check deposits may be available the day the bank receives them if you use the mobile app. Other banks hold longer, especially on new accounts and large checks.
Clock three: finality
Finality is when the check can no longer come back. It is the slowest clock, and no app displays it.
A bounced check can return within days. A forged, altered or counterfeit item can surface weeks later. The FTC warns that fake checks “can take weeks to be discovered and untangled.” Until then, your credit is provisional. Under the Uniform Commercial Code, which is state law, a bank’s right to charge back a returned item “is not affected by previous use of a credit given for the item.” In plain English: spending the money does not protect you.
Reading the three clocks together
The dangerous stretch sits between clock two and clock three. Money you can spend is not money you can keep. The table shows who controls each clock and what you can do about it.
| Clock | What it tells you | Timing | Who controls it | Your move |
|---|---|---|---|---|
| Posting | The bank received your image | Same day to next business day at many banks; varies | App and bank systems | Save the confirmation and verify the amount |
| Availability | How much you can spend, and when | Often the first or second business day; longer with holds | Bank policy, using Regulation CC as a benchmark | Spend only the available balance |
| Exception hold | Why part of the deposit is delayed | Days beyond the standard schedule | Bank, within its contract and the law | Ask for the reason and release date |
| Finality | The check will not come back in the ordinary course | Days for most returns; weeks in fraud cases | Paying bank and legal return deadlines | Keep the check; do not send money out against it |
Why a pending deposit does not protect your balance
Banks approve debit card purchases, ATM withdrawals and many electronic payments against your available balance. A pending deposit does not count. If a bill payment posts overnight while your funds are still on hold, the bank may decline it, return it or pay it into overdraft, depending on your account settings. Fees may follow.
The practical rule is to line up due dates with the availability date, not the posting date. The overdraft protection guide explains how opt-in programs work.
How Mobile Check Deposit Works Behind the Screen
What the app actually captures
When you photograph a check, the app captures more than a picture. It reads the MICR line, the magnetic-ink numbers along the bottom that hold the routing number, account number and check number. It reads the written and numeric amounts and compares them. It tests image quality for focus, glare, skew and cropped corners.
It also looks at the back for your endorsement. If any piece fails, the app asks for a new photo. A pass means only that the image is usable. It does not mean the check is good.
Remote deposit capture and the Check 21 Act
Banks call this technology remote deposit capture, or RDC. Congress cleared the way with the Check Clearing for the 21st Century Act, known as Check 21, which took effect on October 28, 2004.
Check 21 did two things. It let banks move electronic images instead of paper. And it created the substitute check, a paper copy that is the legal equivalent of the original when it carries the statement “This is a legal copy of your check.” The Federal Reserve notes that the law does not require banks to accept checks in electronic form. Mobile deposit is therefore a product each bank chooses to offer, on its own terms. Industry histories date the first smartphone deposit apps to 2009.
From your phone to the paying bank
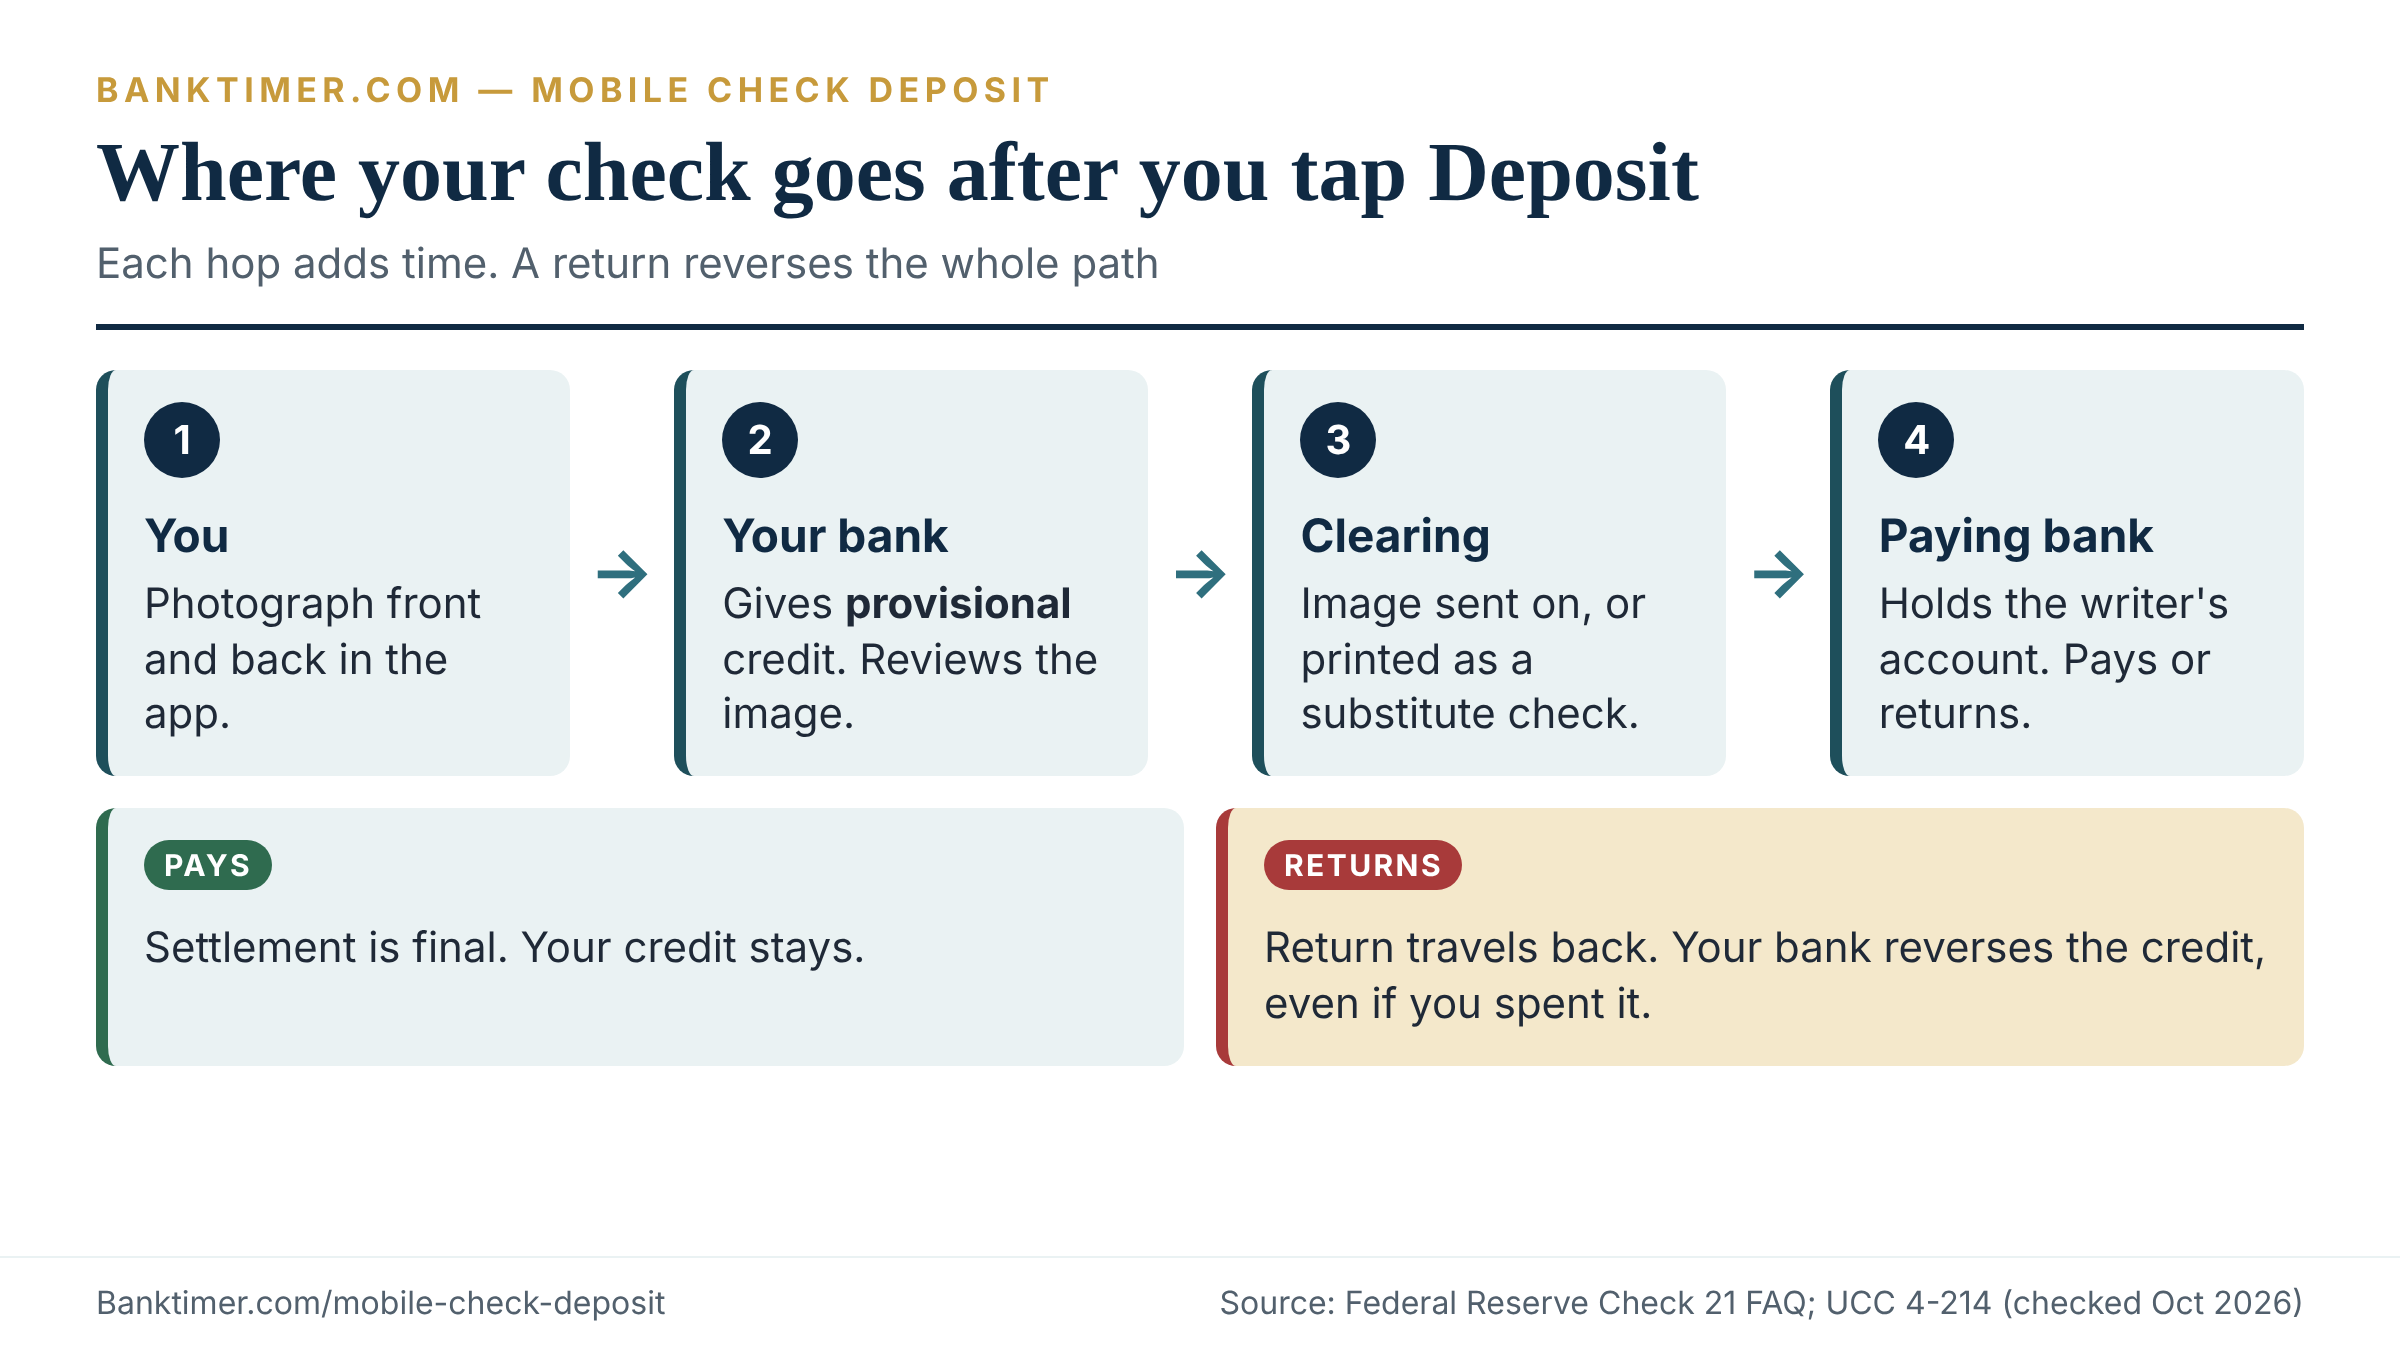
After you tap Deposit, your bank (the depositary bank) credits your account provisionally. It sends the image onward as an electronic check or, if the next bank still wants paper, as a printed substitute check. Regulation CC defines an electronic check as an image plus data derived from the paper check, sent under an agreement and meeting an industry standard.
The bank that holds the writer’s account, the paying bank, decides whether to pay. If it pays, settlement becomes final. If it returns the check, the return travels back and your bank takes the provisional credit away. Each hop adds time, which is why availability and finality run on different clocks.
Business accounts follow the same path with different contracts
Businesses use similar technology, often with desktop scanners and a separate remote deposit agreement. Those agreements tend to add higher limits, stricter controls, audit rights and sometimes fees. Wells Fargo’s help page notes that some customers with analyzed business accounts may be charged a transaction fee.
This article focuses on consumer accounts. If you run a business, ask for the full agreement and read the retention, fee and liability sections before you rely on it.
The Federal Reserve Payments Study, released July 1, 2026, counted 9.2 billion checks paid in 2024, worth $24.45 trillion. That is down from 11.0 billion in 2021. Checks now make up 4% of noncash payments by number but 17% by value. The average check was $2,653, up from $945 in 2000. Fewer checks, but bigger ones, which is exactly why a hold or a reversal can hurt.
Who Can Deposit, How Much, and Which Checks Get Rejected
Eligibility starts with the account, not the app
Most banks offer mobile check deposit on checking and savings accounts that have been open a while and show normal activity. A brand-new checking account may face lower limits or longer holds. You may also need to enroll, accept a separate mobile deposit agreement and use a supported phone. The feature is one piece of broader online banking, and the same login protections apply.
Online-only banks have no branches, so phone and mailed deposits often become the main way to add check money. The trade-offs are covered in our guide to the online bank account. Whatever you use, ask whether your account tier has a lower limit and whether the bank reviews new deposits by hand.
Limits vary more than most people expect
Limits come from your bank’s risk model, not from a federal rule. They can differ by account type, account age and deposit history. Many banks display your personal limit inside the app at the moment you deposit.
Wells Fargo says limits appear for each eligible account on the Enter Amount screen. Bank of America says a monthly limit shows when you pick the account. Capital One describes daily and monthly limits without publishing amounts. Ally publishes numbers: $50,000 per business day and $250,000 per 30 days for its eCheck Deposit service.
The table below pulls dated examples from four providers’ own pages. None describes your account. Together they show how far the rules can drift, and why your own agreement is the only document that counts.
| Provider (source, checked Oct 2026) | Cutoff cited | Limit disclosure | Keep the paper check | Fee for the service |
|---|---|---|---|---|
| Wells Fargo (mobile deposit FAQ) | 9 p.m. PT on business days | Shown per account in the app; no amounts on the page | 5 days, then destroy | None for most customers; some analyzed business accounts may pay |
| Capital One (mobile deposit disclosure) | 9 p.m. Eastern, as written | Daily and monthly limits; no amounts on the page | Until it appears in your transactions, then shred or cut up | No additional charge; carrier data rates may apply |
| Ally Bank (eCheck FAQ dated Jan 20, 2026) | 7 p.m. ET | $50,000 per business day; $250,000 per 30 days | Page does not say | Described as free |
| Bank of America (mobile deposit info page) | Cutoff time not stated on the page | Monthly limit shown in the app | Page does not say | No additional fee; carrier fees may apply |
Read across the rows and the pattern is clear. Cutoffs span at least two hours and different time zones. Retention advice ranges from five days to “until it posts.” Two of the four pages say nothing about how long to keep the check.
How banks set and change your limit
Banks start cautious. The FDIC’s remote deposit capture primer calls customer screening the single most effective risk-control technique, and limits are how a bank puts screening into practice. A new customer with no history often gets a lower ceiling than a ten-year customer with steady payroll deposits.
Limits tend to move with your behavior. Regular deposits, healthy balances and few returned items build trust. A returned check, an overdraft or a burst of unusually large deposits can lower the ceiling. If your limit blocks a legitimate check, ask about a temporary increase. Otherwise use a branch.
Checks banks commonly refuse
Even a perfect photo can fail on the check itself. Some items are rejected on the spot. Others are accepted and reversed later. Provider lists overlap heavily but are not identical, so confirm yours.
| Item | Why banks restrict it | Example from provider documents | Better route |
|---|---|---|---|
| Money orders and traveler’s checks | Security features are hard to verify from an image | Listed as ineligible by Wells Fargo, Bank of America and Capital One | ATM or branch deposit |
| Foreign (non-U.S.) checks | Slower collection and currency issues | Listed by Wells Fargo and Bank of America; Capital One excludes non-U.S. institutions | Branch, where staff can explain collection terms |
| Third-party checks | Endorsement chain and fraud risk | Listed by Bank of America and Capital One | Branch with ID, or have the payee deposit it |
| Checks older than six months | State law lets a bank refuse stale checks | Capital One: older than 6 months; Ally: older than 180 days | Ask the writer for a new check |
| Postdated or altered items | Not yet payable, or authenticity in doubt | Capital One lists both | Wait for the date; request a replacement |
| Remotely created and convenience checks | Different signature and risk profile | Wells Fargo lists both; Ally lists remotely created checks | Branch deposit |
| Previously deposited items | Duplicate presentment | Wells Fargo and Ally | Never redeposit |
The six-month rule comes from the Uniform Commercial Code, which says a bank “is under no obligation” to pay most checks presented more than six months after their date. States adopt the code individually, so wording can vary slightly.
Endorsement: the words on the back matter
A signature alone is not enough at many banks. They want a restrictive endorsement, a phrase that limits the check to mobile deposit at that bank. Wells Fargo asks for “For Mobile Deposit at Wells Fargo Only” below your signature. Capital One asks for “for Capital One mobile deposit.” Ally asks for “For Mobile Deposit Only,” plus your account number on its eCheck page.
The phrase has a job. It makes a second deposit of the same check at an ATM, a branch or another app easier to catch. If a check lists two payees, Ally says each payee must sign. Use your bank’s exact wording, because a missing or incorrect endorsement can get the deposit rejected.
Checks with two payees or a name mismatch
A check made out to two people may need both signatures. Ally’s page says each payee must sign. Banks often read “and” between two names as requiring both endorsements and “or” as requiring one, but your agreement controls, so ask.
Name mismatches trip deposits too. A check payable to a person, deposited into an account titled for that person’s business, can be rejected. Take it to a branch, where staff can ask for ID or business documents. Do not try to repair it with a creative endorsement.
Old checks, expiration legends and combined deposits
Some checks print their own limit, such as “void after 90 days.” A paying bank may return a check presented after a printed limit, so read the face before you deposit. Separately, the six-month stale-date rule in the Uniform Commercial Code lets banks refuse older checks.
If you deposit several checks, your daily and monthly limits count the total. On an illustrative $5,000 daily limit, a $3,000 check and a $4,000 check cannot both go through the same day. Split them across days only when you trust both payers.
Cutoff Times, Weekends and Holidays Change Your Date
How a cutoff works
A cutoff is the time after which your bank treats a deposit as received on the next business day. Regulation CC sets floors for branches and ATMs: no earlier than 2 p.m. at a branch and no earlier than noon at ATMs and other off-premises locations.
Mobile cutoffs come from your agreement. The examples above run from 7 p.m. to 9 p.m. Watch the time zone. A 9 p.m. Pacific cutoff passes at midnight for a customer in New York.
Weekends and federal holidays
Regulation CC defines a banking day as a day the bank is open for substantially all banking functions. A deposit made on a non-banking day counts as received on the next banking day. A business day excludes Saturdays, Sundays and federal holidays.
So a Friday-night deposit after cutoff is received Monday, and the “next business day” begins Tuesday. A Monday holiday pushes everything back another day. The table applies one set of assumptions to six deposit moments.
| Deposit made | Treated as received | First $275 available | Remainder available |
|---|---|---|---|
| Tuesday, 3 p.m. | Tuesday | Wednesday | Thursday |
| Tuesday, 10 p.m. | Wednesday | Thursday | Friday |
| Friday, 3 p.m. | Friday | Monday | Tuesday |
| Friday, 10 p.m. | Monday | Tuesday | Wednesday |
| Saturday, noon | Monday | Tuesday | Wednesday |
| Friday, 3 p.m., Monday is a federal holiday | Friday | Tuesday | Wednesday |
Assumptions for the table: illustrative only. The bank uses a 9 p.m. local cutoff, follows the Regulation CC benchmark schedule, applies no holds and counts only business days. A bank that releases the full amount the next business day would shorten the last column.
Phone versus ATM: why the rules and cutoffs differ
Regulation CC speaks directly to ATM deposits. A deposit at your own bank’s ATM counts as made when the machine receives it. A deposit at a nonproprietary ATM, one your bank does not own or operate, can wait until the fifth business day under 12 CFR 229.12(f). The regulation also sets a cutoff floor of noon for ATMs, compared with 2 p.m. at a branch.
A mobile check deposit has no comparable text to lean on, so cutoffs come from your agreement. At the four banks cited here they run from 7 p.m. to 9 p.m., well after the branch floor. Some products treat the channels alike. Wells Fargo’s schedule offers up to $400 of same-day availability for teller, ATM and mobile app deposits.
Illustrative example: the Thursday-night deposit
Assumptions: Rent of $1,800 is due Friday. The landlord charges a $50 late fee starting Saturday (illustrative). You hold an $1,800 check from a client. Your bank’s mobile cutoff is 9 p.m., and it releases funds the next business day after receipt, with no hold.
- Deposit Thursday at 7 p.m.: received Thursday, available Friday. Rent is on time.
- Deposit Thursday at 10 p.m.: received Friday, available Monday. You miss Friday, and the $50 fee lands.
A check-cashing service charging 2% (illustrative; real fees vary) would cost $36 and pay out right away. On these numbers the cashing fee beats the late fee by $14. If your lease allows a three-day grace period, the free deposit wins and the fee is wasted. Run the math with your actual lease terms.
Holds: Why the Money Shows Up but You Cannot Spend It
Standard availability and exception holds
A routine delay under your bank’s normal schedule is not a hold in the legal sense. It is just the schedule. An exception hold is different. The bank stretches the schedule because the account or the deposit looks riskier than usual.
Regulation CC lists the allowed exceptions. Banks often borrow those categories for phone deposits too, even when the regulation’s reach is debatable. The CFPB also lists emergencies such as system outages as a reason for delay. The table shows the main triggers and their outer limits.
| Exception | Trigger | Outer limit under Regulation CC | Source |
|---|---|---|---|
| New account | First 30 calendar days of an account | Excess over $6,725 of cashier’s-type checks due by the ninth business day; ordinary checks outside the schedule | 12 CFR 229.13(a) |
| Large deposit | More than $6,725 across one banking day | Reasonable extension, up to five more business days for second-day checks | 12 CFR 229.13(b), (h) |
| Repeated overdrafts | 6+ negative days in six months, or 2+ days negative by $6,725 or more | Applies for six months after the last overdraft | 12 CFR 229.13(d) |
| Reasonable cause to doubt collectibility | Facts creating a “well-grounded belief” the check will not be paid | Reasonable period; bank must send notice | 12 CFR 229.13(e), (g) |
| Redeposited check | Check was already returned unpaid | Normal schedule need not apply | 12 CFR 229.13(c) |
The “reasonable cause” standard matters most to phone depositors. The regulation requires facts that would convince a reasonable person. A bank’s hunch is not enough, and the notice has to say why.
New accounts: the 30-day rule
Regulation CC treats an account as new for its first 30 calendar days. A carve-out helps existing customers. An account is not considered new if every customer on it held another account at the same bank for at least 30 calendar days within the 30 days before opening. If you already bank there, a second account may start without the new-account label. Our guide to opening a bank account online covers the setup steps.
For brand-new customers, the rules shift in an odd way. Next-day treatment of cashier’s, certified and similar checks is capped at the first $6,725 per banking day, and the excess is due by the ninth business day. Ordinary checks fall outside the regulation’s schedule entirely during those 30 days. That leaves the timing to your bank’s disclosure. Expect a longer wait on your first mobile check deposit, and do not plan a rent payment around it.
The hold notice: what to look for
A bank that invokes an exception generally must give you written notice. It should identify the account, the deposit date, the amount delayed, the reason and the date the money will be available. When the notice arrives depends on how you deposited and when the bank learned the relevant facts.
With a phone deposit, many banks deliver the notice inside the app or by email. Check both, plus your mailed notices. If you cannot find one, ask for it in writing and note the date you asked.
Reading your funds availability disclosure
Regulation CC requires banks to give new account holders a written funds availability policy. Most people never read it. Open it before your first large deposit and look for six things.
- Business days: which days count, and whether Saturdays do.
- The standard schedule: and whether phone deposits follow it.
- The mobile cutoff: the time and the time zone.
- Exception-hold language: including any case-by-case discretion.
- Other banks’ ATMs: how the bank treats deposits made there.
- Chargeback and returned-item terms: usually in the deposit agreement, not the disclosure.
Two documents matter. The disclosure explains timing. The deposit agreement and the separate mobile check deposit terms explain liability. Read both, and save a copy of the terms you accept inside the app.
Why holds feel more common on phone deposits
Banks see less when you deposit by phone. No teller handles the paper. The FDIC’s remote deposit capture primer lists duplicate presentment, alteration, counterfeiting, poor image quality and weak customer authentication among the main operational risks. Banks answer with limits, automated reviews and holds.
Your agreement may also let the bank delay funds at its own discretion. Capital One’s disclosure, for example, says extended holds may apply under its availability schedule. Signals that tend to draw review include a new account, an unusual amount, an unfamiliar payer and a blurry image.
Illustrative example: a $9,000 check
Assumptions: The bank mirrors the Regulation CC benchmark schedule. Your account is well past 30 days with no overdraft history. You deposit a $9,000 insurance check by phone, before cutoff, on a Tuesday.
- Normal-schedule portion: the first $6,725. Of that, $275 is available the next business day and the remaining $6,450 by the second.
- Excess: $2,275 sits above the threshold and can be held longer. With five extra business days, the outer limit is the seventh business day.
- Check: $275 + $6,450 + $2,275 = $9,000.
Do not schedule a $9,000 payment until the seventh business day unless your bank confirms an earlier release in writing.
What Mobile Check Deposit Costs
The service itself is usually free
Wells Fargo says most customers pay no fee to use mobile deposit. Capital One says the service comes at no additional charge. Bank of America says there is no additional fee but suggests asking your wireless carrier about data charges.
So the headline cost is zero. The expense shows up when something goes wrong or when you try to skip the wait. The table sorts the costs by trigger.
| Cost item | Trigger | Typical basis | Example | Avoidable? |
|---|---|---|---|---|
| Standard mobile deposit | Using the app | Usually no charge | Wells Fargo, Capital One and Bank of America report no added fee | Nothing to avoid |
| Carrier data | Your phone plan | Varies by plan | Bank of America suggests checking with your carrier | Often |
| Returned deposited item | Check comes back unpaid | Flat per item; varies, $0 at some banks | 2023 snapshot of ten large banks: $10 to $19; Wells Fargo page effective Sept 11, 2026: no fee | Partly: vet the payer |
| Overdraft after a reversal | You spent funds, then the credit reversed | Flat per item at some banks, plus the reversed amount | Wells Fargo Everyday Checking lists $35 per overdraft item (effective 7/28/2026) | Yes: wait for finality |
| Expedited cash or check cashing | Paying to skip a hold | Percentage or flat fee; varies by provider | Illustrative 2% fee: $36 on $1,800 | Often |
| Cost of waiting | A hold covers a due date | Late fees, interest | $50 late fee in the Thursday example | Plan ahead |
Paper is expensive to move. Every check that a teller handles, sorts and ships costs the bank money, and an image captured on your phone shifts that work onto your device. That is Banktimer’s reading of why banks promote the feature and rarely charge for it. They still price the risk. Limits, reviews and holds are how the bank charges you in time instead of dollars.
Where the money actually leaks
Returned-item fees are shrinking at some banks. A September 2023 MyBankTracker snapshot found fees from $10 to $19 among the ten largest banks, averaging $12.85 for domestic items. Wells Fargo’s current fee page, effective September 11, 2026, says it does not charge a fee when a deposited item is returned. Fee schedules change often, so read yours.
The fee is the smaller problem. A reversal can leave your account negative. Overdraft fees, if your bank charges them, stack on top. Our overdraft protection guide explains how those programs work.
Check cashing apps and stores: paying for speed
Some apps and retailers will turn a check into cash or an app balance for a fee. Fee structures vary by provider, amount and check type. Read the current fee schedule before you commit.
A fee buys speed, not safety. If the check turns out to be fake, you may still owe the money. Ask four questions first: what is the fee, what ID do you need, is the payout final, and what happens if the check bounces? Compare the answer with the cost of simply waiting.
How a Deposited Check Comes Back
Why a bank can reverse a deposit you already spent
A bank that credits your account for a check is treated as giving provisional credit. The credit becomes permanent only when the check is paid. If the check is returned, the bank may charge back the credit.
Under Uniform Commercial Code section 4-214, the bank generally must act by its midnight deadline or within a longer reasonable time after it learns the facts. The same section says the right to charge back “is not affected by previous use of a credit given for the item.” That is state law, and states adopt the code individually. Your deposit agreement usually adds its own chargeback clause. Capital One’s agreement, for instance, reserves the right to charge back any item returned or rejected for any reason.
Common reasons for a returned deposit
Returns have a handful of causes. Knowing them helps you judge which deposits deserve extra caution.
- Insufficient funds: the writer’s account lacks the money.
- Stop payment or closed account: the writer canceled the check or shut the account.
- Signature or authenticity problems: the paying bank questions the signature or the item.
- Alteration or counterfeit: the amount or payee was changed, or the check is fake.
- Stale or postdated: the date makes the check unpayable.
- Image or endorsement defects: the bank cannot process what you sent.
- Duplicate presentment: the check reached the paying bank twice.
Routine returns, such as insufficient funds, tend to surface sooner than fraud findings. No rule tells you exactly how soon. That is why the paper check and the payer’s reliability matter after the money appears.
Duplicate deposits: the mistake banks watch hardest
Depositing the same check twice creates duplicate presentment. It can happen when an app times out and you try again, or when you deposit by phone and then drop the check in an ATM. Both images reach the paying bank. One will be returned, and your bank reverses the matching credit.
Capital One’s agreement says it can charge back an item rejected for any reason, including a belief that the item was previously submitted or deposited. Your agreement likely makes you responsible for losses from breaking its terms. Before you retry, look at your pending transactions. Keep the check. Redeposit only if the bank tells you the first attempt failed.
What to Do When a Mobile Check Deposit Is Held, Rejected or Reversed
Start with facts, then escalate in order. Most problems end at step two. Raise issues early, because the reporting windows in your account agreement can be short.
| Step | What to do | Who to contact | What to keep |
|---|---|---|---|
| 1. Confirm the facts | Compare the available balance, pending items and any hold notice | Your bank’s app or online banking | Dated screenshots |
| 2. Ask the bank | Ask for the reason, the release date and the rule the bank relies on | The number on your card, or the secure message center | Date, time, representative’s name and reference number |
| 3. Put it in writing | Request the hold notice or an explanation of the reversal | Secure message or mailed letter | A copy and proof of sending |
| 4. Escalate inside the bank | Ask for a supervisor or the complaint department | The bank’s complaint channel | The ticket number |
| 5. File an outside complaint | Submit a complaint with the regulator | CFPB at consumerfinance.gov/complaint or (855) 411-2372; your state banking regulator; the NCUA for federal credit unions | Your full paper trail |
If the app rejects the deposit
Rejections are the easy case. Read the reason on the screen. Retake the photo on a darker surface, fix the endorsement, or try the amount again. If it fails twice, use a branch or ATM and keep the check. Do not deposit it anywhere else until the bank confirms the first attempt did not post.
If the deposit was reversed and your balance went negative
A reversal that exceeds your balance leaves you owing the bank. Ask for the amount, the reason and the deadline in writing. Ask whether the bank will accept a payment plan. Do not ignore the balance, because an overdrawn account can be closed. If the check was fake, add a report to the FTC and tell the bank’s fraud team.
Security: The App Is Rarely the Weak Point
The phone app is usually the safest link in the chain when you protect it. The paper check and the person who wrote it carry more of the risk. Three areas deserve attention: your device, the mail, and the check itself.
Locking down the phone and the account
Use a screen lock and the app’s biometric login. Install updates. Download the app only through your bank’s official link. Turn on every alert the bank offers, including deposit alerts. They tell you quickly if someone else touches your account.
Where your bank offers two-factor authentication, use it. The two-factor authentication guide explains the options. Our mobile banking security guide covers device hygiene in more depth.
One habit often gets missed. A check photo shows your routing and account numbers. Delete the image from your camera roll after the deposit posts, especially if your photos sync to the cloud.
Mail theft and check washing
The weak point is often paper. FinCEN’s alert of February 27, 2023 reported that banks filed more than 350,000 suspicious activity reports on check fraud in 2021 and more than 680,000 in 2022, nearly double. It describes check washing as using chemicals to remove the original ink so a thief can replace the payee and often the amount.
A later FinCEN trend analysis counted 15,417 reports of mail-theft check fraud between February 27 and August 31, 2023. They involved more than $688 million in transactions, roughly $44,600 per report. FinCEN wrote that “Deposits at ATMs or via RDC were the preferred method of deposit,” and noted that many perpetrators favor methods that avoid human contact.
That does not make mobile check deposit unsafe for you. It explains why banks scrutinize new accounts and unusual deposits. It also means a check you mail can be altered and deposited by a stranger. Review your bank statement for checks you did not write, and report them at once. Your account agreement sets the reporting deadlines.
Fake checks and overpayment scams
The most common trap targets the person receiving the check. A stranger sends a check for more than they owe. They ask you to deposit it and send the difference back by wire, gift card or crypto. The FTC puts it bluntly: “Even if you see the funds in your account, that doesn’t mean it’s a good check.”
The FTC adds that fake checks “can take weeks to be discovered and untangled.” If the check is fake, you owe the bank. The money you sent is usually gone. Recognize the pattern: an unexpected check, a payer you cannot verify, a request to send money back and pressure to act fast.
If you suspect a fake, stop. Do not send anything. Call your bank using the number on your card. Report the scheme to the FTC at ReportFraud.ftc.gov. Related patterns are covered in the bank impersonation scam guide.
Illustrative example: the $2,400 “overpayment”
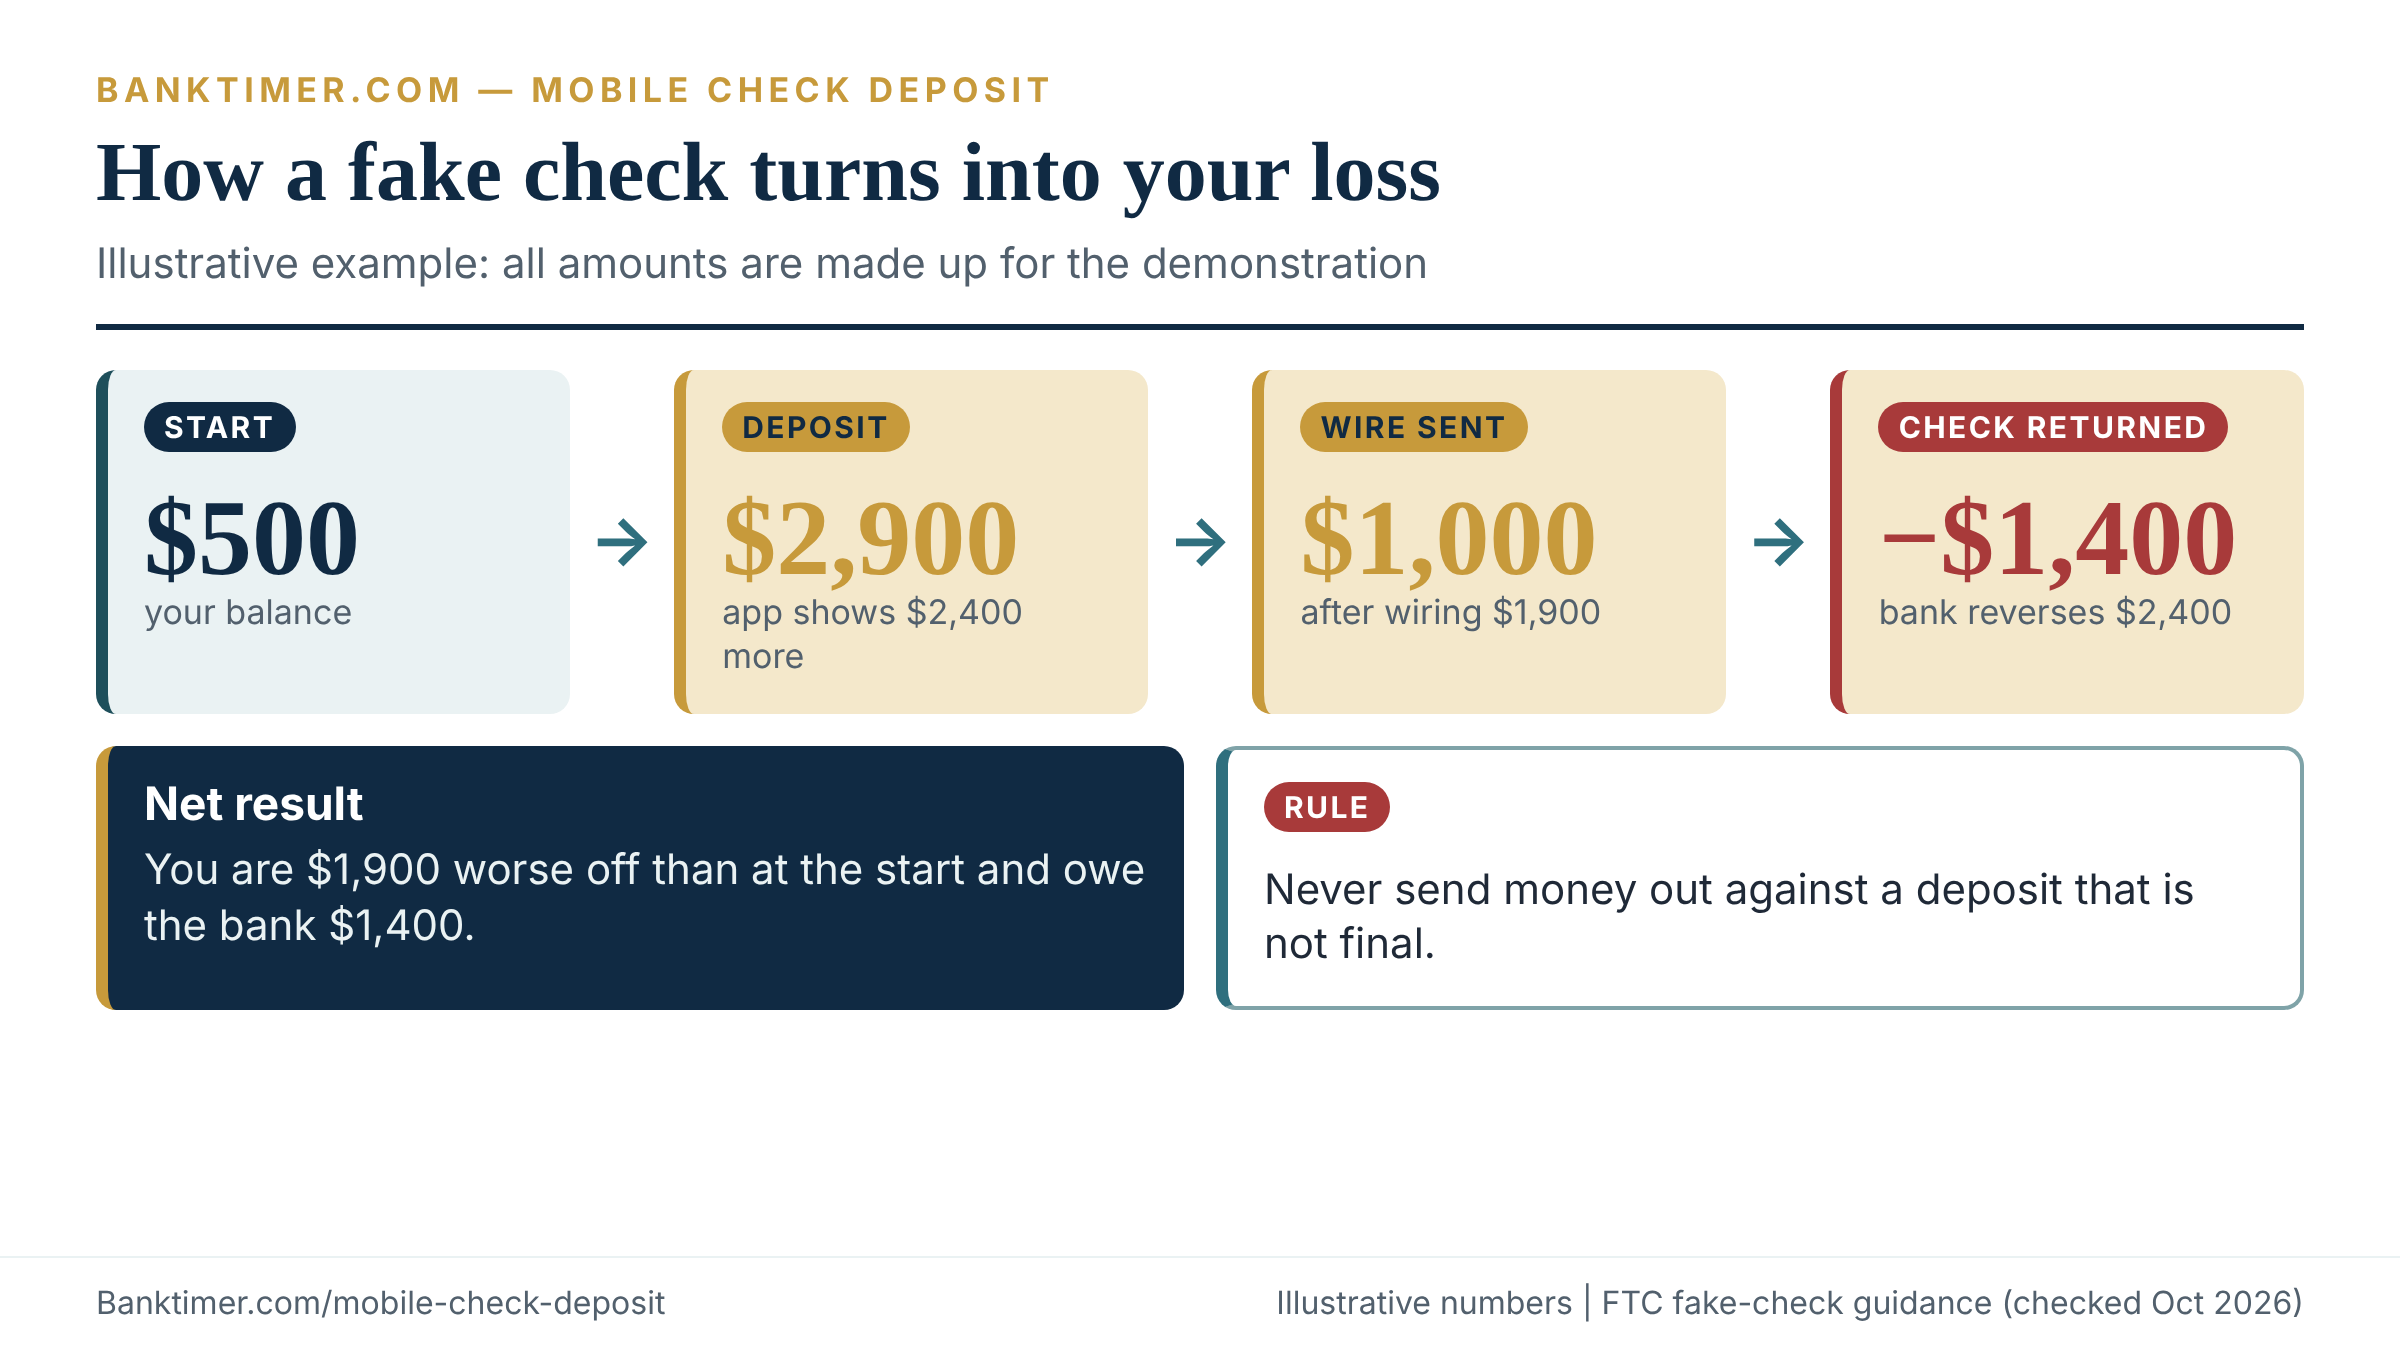
Assumptions: Your balance is $500. A “buyer” sends a $2,400 check for a $500 item and asks you to wire back $1,900. You deposit by phone, the app shows the funds and you wire the $1,900.
- After the deposit: $500 + $2,400 = $2,900 (provisional).
- After the wire: $2,900 − $1,900 = $1,000.
- Nine days later the check is returned, and the bank reverses $2,400: $1,000 − $2,400 = −$1,400.
You are $1,900 worse off than when you started and owe the bank $1,400. A wire transfer is hard to recall once sent, so the loss usually lands on you.
Red flags to check before you trust a check
The next table turns the pattern into questions. Any one flag deserves a pause. Two or more deserve a call to your bank before you spend or send anything.
| Red flag | Why it matters | What to ask | Safer next step |
|---|---|---|---|
| Check for more than you are owed | Classic overpayment pattern | Why is the amount larger? | Return it uncashed and ask for the correct amount |
| Payer you cannot verify | You cannot judge whether the account is real | Who is paying, and can I confirm that independently? | Verify through contact details you find yourself |
| Request to send money back | Moves the loss to you | Why can’t the payer fix this? | Refuse; never send money against an unsettled check |
| Pressure to act today | Scams rely on speed | What happens if I wait for finality? | Slow down and wait |
| Unexpected cashier’s check | Counterfeits exist | Is the issuing bank real? | Call the issuing bank at a number you find independently |
| Faded writing under darker writing | FinCEN lists this as a sign of washing | Was this check altered? | Do not deposit; ask the payer for a replacement |
If anyone asks you to send money, buy gift cards or return an “overpayment” after you deposit a check, treat it as a scam until proven otherwise. A posted balance is not proof of a good check.
When you are the one writing the check
Mobile check deposit changes life for the sender too. A payee who deposits by phone starts the clearing process within minutes, not days. Do not count on mailing delays to buy you time. Keep enough in the account to cover the check the day you hand it over.
Check 21 also gave check writers a specific protection. Say your bank returns a substitute check with your statement and you suspect it cost you money. The Federal Reserve says to contact your bank as soon as possible but no later than 40 days from when it mailed or delivered the statement. If the bank cannot settle the claim within 10 business days, it must refund your loss, up to the lesser of the check amount or $2,500, plus interest.
That right is tied to substitute checks, the paper copies. It applies only where one was created, so do not assume it covers every image deposit.
Taking a Clean Photo and Handling the Paper Check
Most rejected deposits fail on small, fixable details. Most reversals trace back to what happened to the paper afterward. The checklist graphic below summarizes the routine.
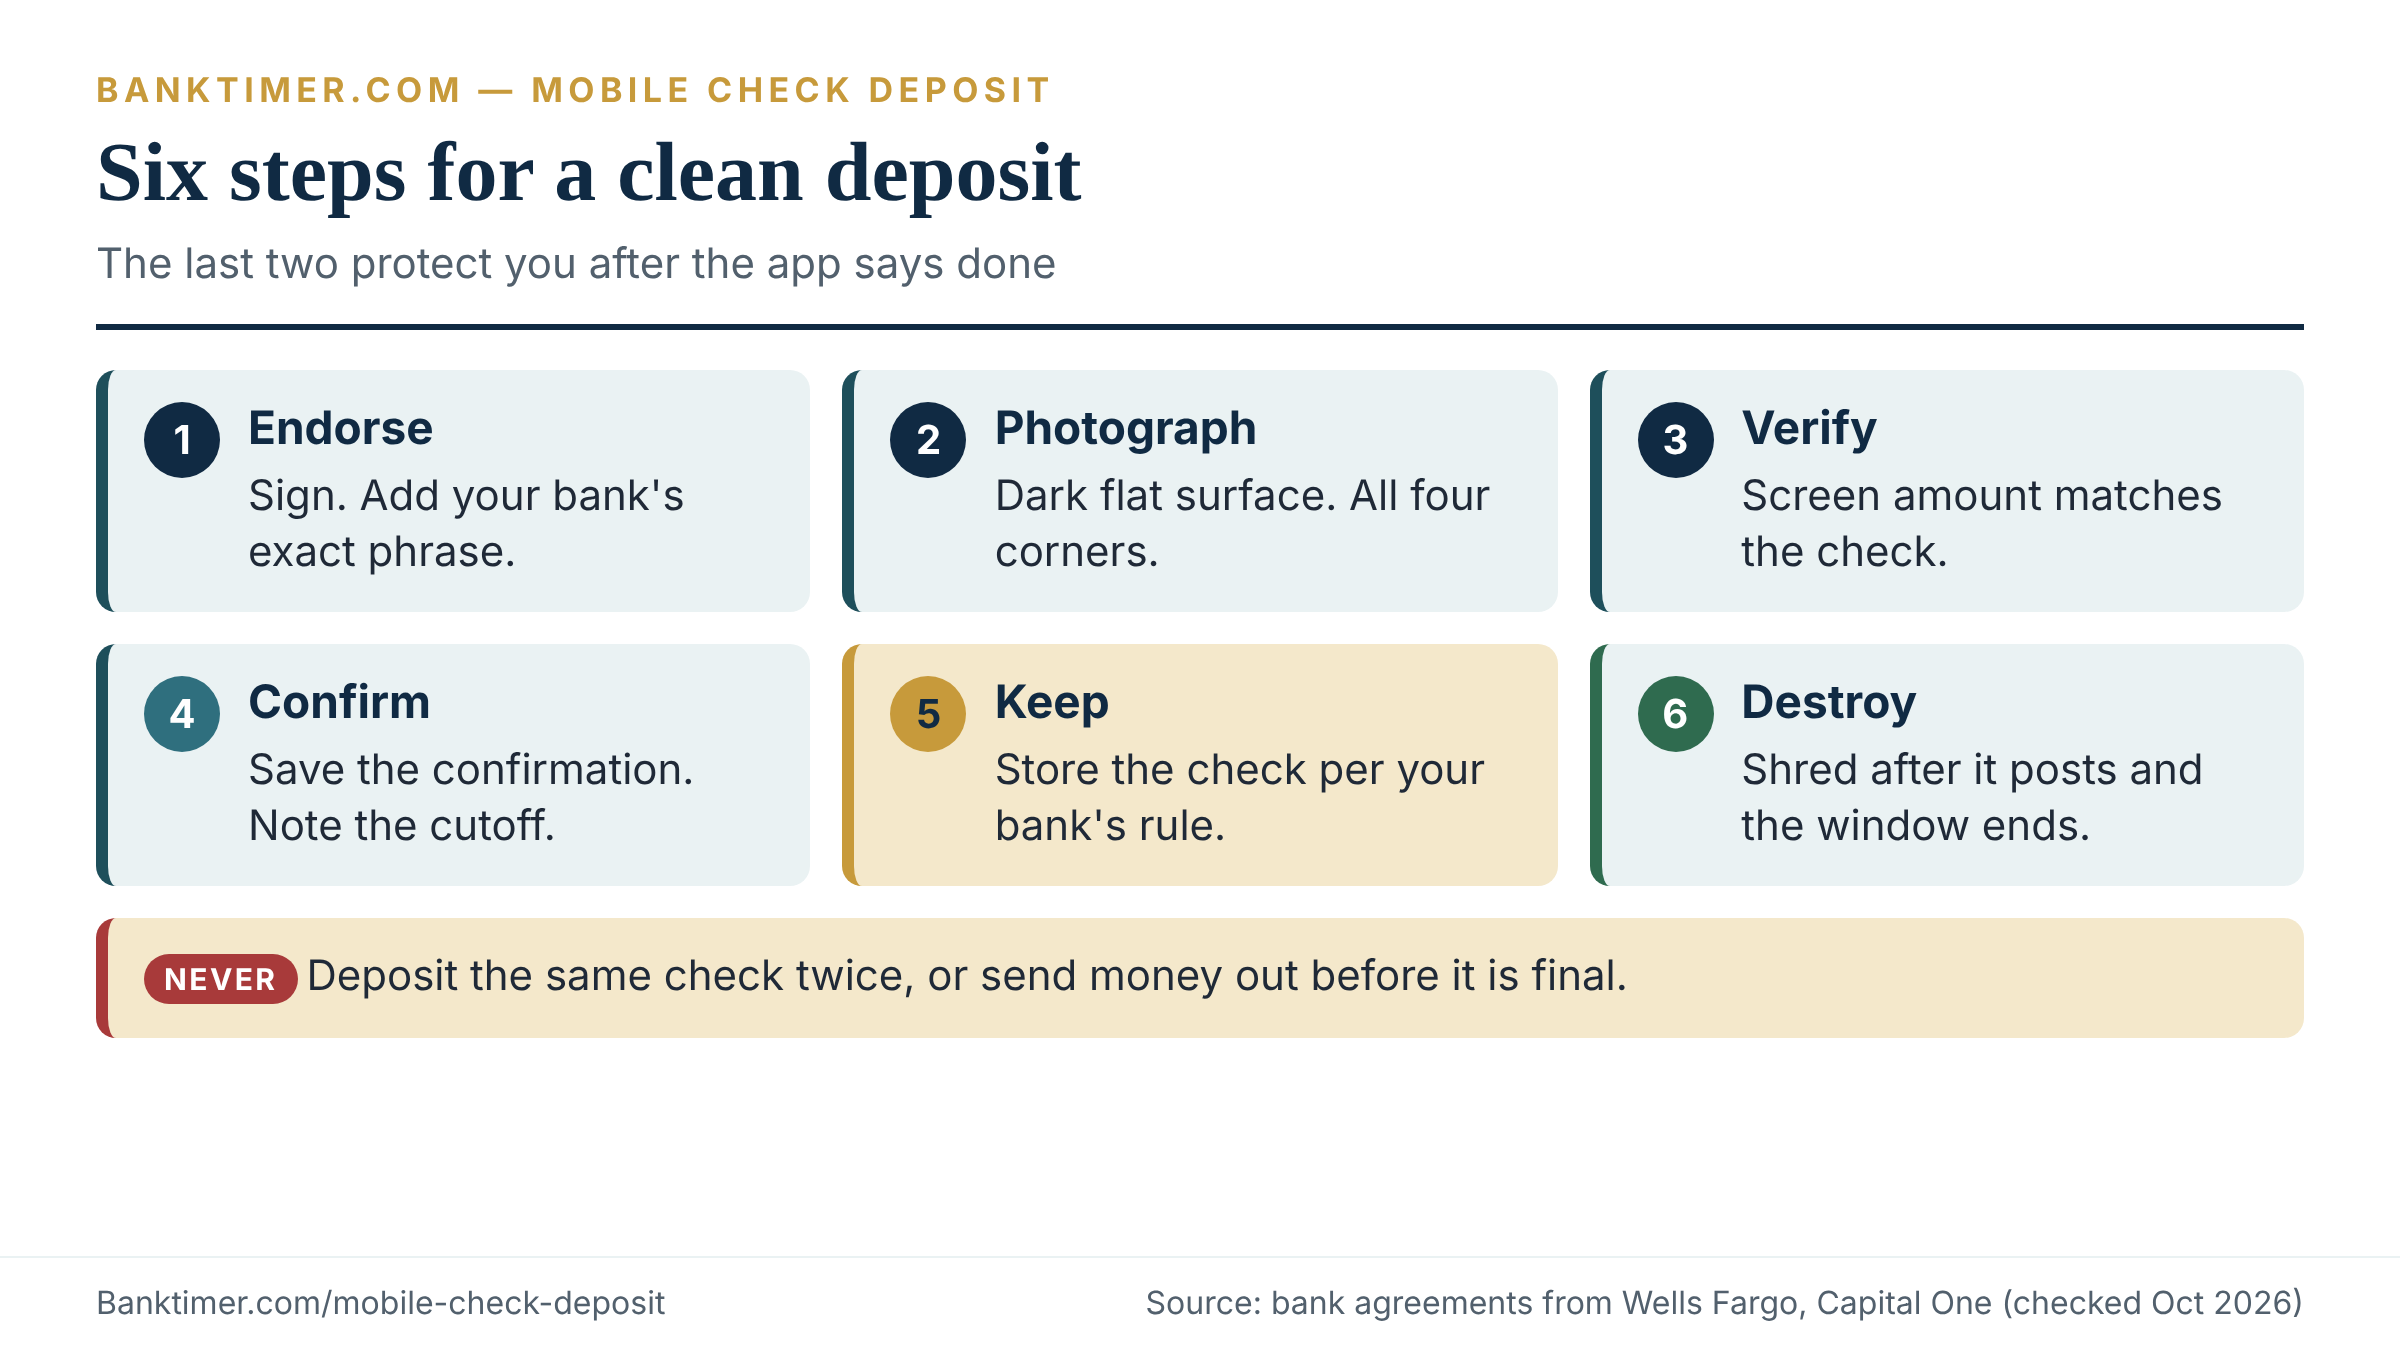
Photo habits that prevent rejections
Lay the check on a dark, flat, matte surface. Use even light and keep shadows from your hand off the paper. Fill the app’s frame guide and keep all four corners visible. Make sure the MICR line at the bottom is sharp.
Hold the phone parallel to the table. Do not zoom with your fingers. Photograph the back after you endorse it, with the restrictive phrase in view. Before you confirm, compare the amount on the screen to the check.
How long to keep the check
Your agreement sets the minimum. Wells Fargo says to store the check safely for five days and then destroy it. Capital One says to keep it until the deposit appears in your transactions, then shred or cut it up. Ally’s page does not say.
Where your bank is silent, a sensible rule is to keep the check until the full amount is available and posted correctly, unless your agreement sets an earlier deadline. For a large or unfamiliar check, waiting longer costs only a drawer. The paper is your evidence if the image fails or the amount posts wrong.
Destroying the check safely
A paper check carries your name and the payer’s account numbers. Destroy it once your agreement allows. Use a cross-cut shredder, or cut through the MICR line and the signature before you throw it out. Do not recycle it whole.
Keep the deposit confirmation and the matching line on your statement. Reconcile them once the deposit posts. If a dispute comes up later, those records matter more than the check you no longer have.
Which Deposit Method Should You Choose? A Decision Framework
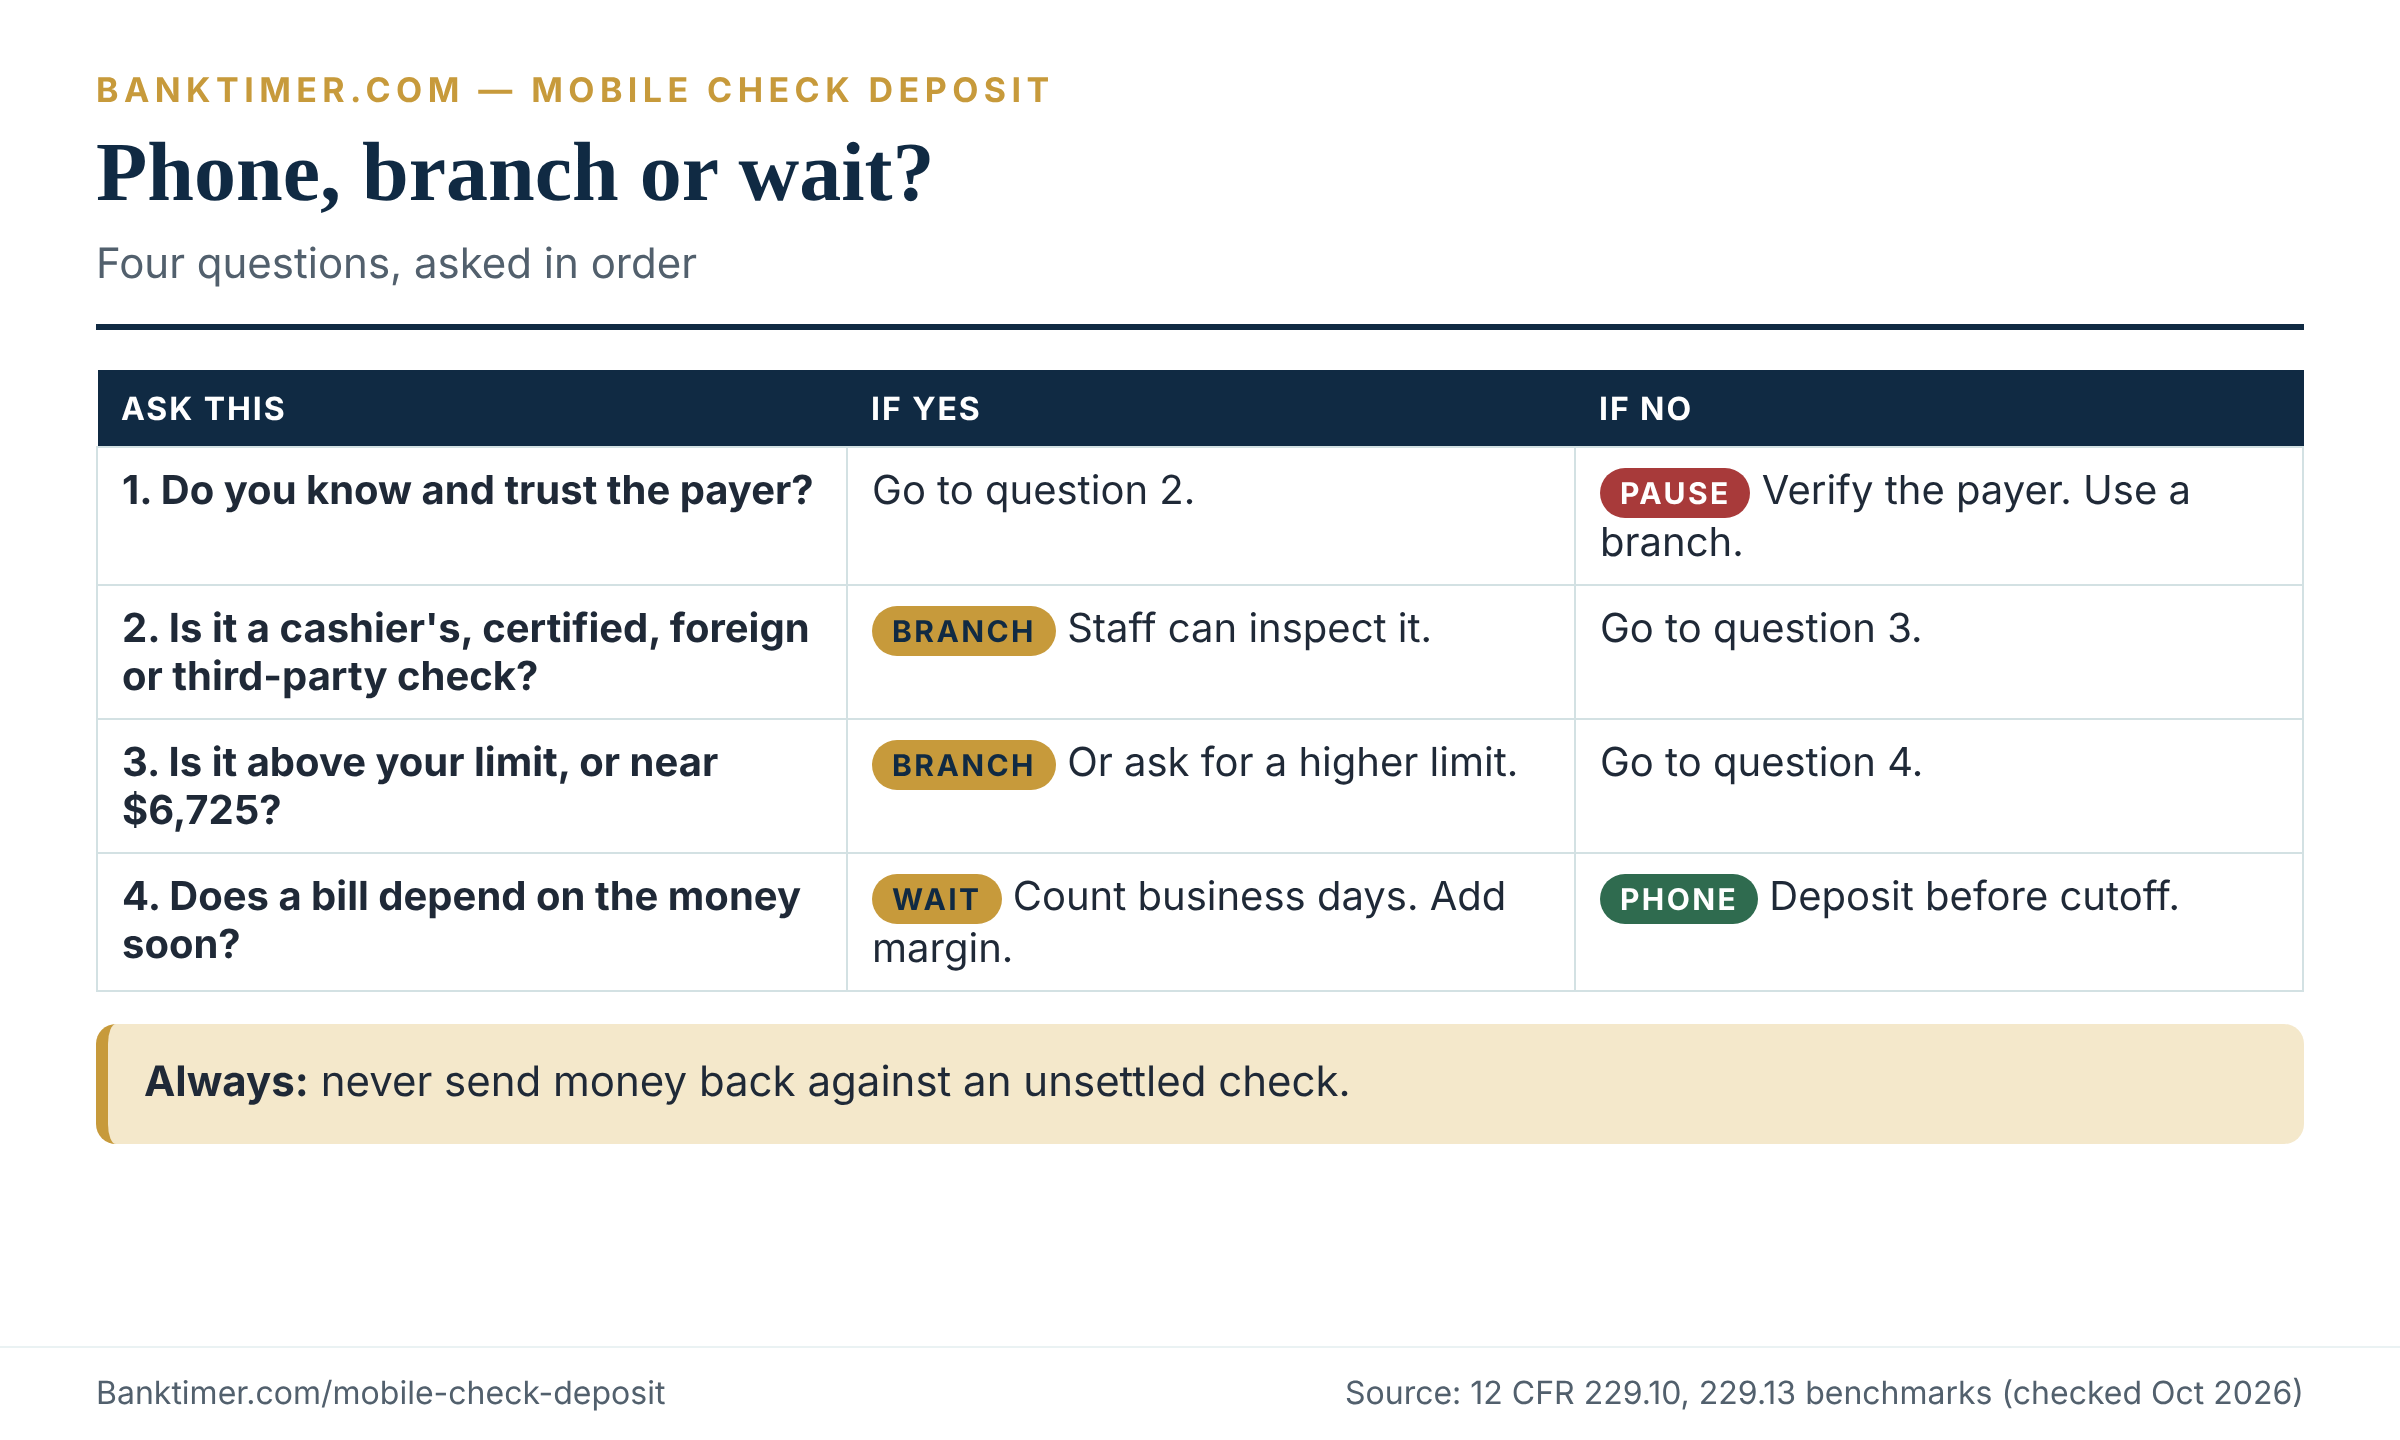
Phone, ATM, branch, mail and cash-it-now handle the same check differently. Pick by the check and your deadline, not by habit. The framework below uses five questions, a decision tree and a comparison table.
Five questions that pick the method
Answer these in order. Stop at the first answer that points away from the phone.
- Is the check larger than your mobile limit, or large enough to trigger extra review? Above your limit, or near the $6,725 benchmark, consider the branch.
- When do you need the money? Count business days from the cutoff, and add a margin for a possible hold.
- What kind of check is it? Payroll and personal checks from known payers suit the phone. Cashier’s, certified, foreign and third-party checks often do better in person.
- Do you know the payer? An unexpected or unverifiable check calls for verification before any deposit.
- What breaks if the check bounces? If rent, a closing or a wire depends on the money, wait for finality.
The table compares the options on the same criteria. No option wins every time.
| Option | Best for | Main upside | Main downside | What to verify |
|---|---|---|---|---|
| Mobile deposit | Routine checks from known payers, under your limit | No trip; evening deposits possible | Lower limits or longer holds on some accounts; no teller review | Your limit, cutoff and endorsement wording |
| Your bank’s ATM | Checks you want a receipt for | Printed receipt; no teller line | Deposits at nonproprietary ATMs can wait until the fifth business day | Whether the ATM is owned by your bank |
| Branch teller | Large, unusual, cashier’s, foreign or third-party checks | Staff can inspect the check; in-person treatment for some check types | Travel and hours | ID rules and a written hold timeline |
| Amounts above mobile limits | No device needed | Slowest; exposed to mail theft | Correct address and mailing instructions | |
| Cash it at the paying bank | Needing cash today | Immediate if the check is good | Fees for non-customers vary | Whether the bank cashes checks for non-customers |
| Check-cashing store or app | Speed over cost | Fast payout | Fees, ID requirements and possible recourse | Fee, finality and bounce policy |
When the branch is worth the trip
Under Regulation CC, cashier’s, certified and teller’s checks get next-business-day treatment when you deposit them in person. Deposited any other way, they fall on the second-business-day schedule. Banks trust a check more when staff can see it. Your bank’s practice may differ, but the logic holds.
Assumptions: You receive a $6,000 cashier’s check on Monday for a car purchase that closes Wednesday. Your bank follows the Regulation CC benchmark and releases funds at the start of business.
- In person Monday, before cutoff: available Tuesday.
- By phone Monday: available Wednesday, the closing day.
The branch buys one business day of margin and a teller’s eye on the check. Cashier’s checks are also counterfeited, so call the issuing bank at a number you find yourself. Our cashier’s check guide covers verification.
When the phone is the better tool
The phone wins on routine checks. Think payroll from a known employer, a rebate check, or a refund from a company you chose to deal with. You skip the trip, and you can deposit in the evening.
Better still, ask the payer for electronic payment. Direct deposit and an ACH transfer avoid image-quality problems and most check fraud. They have their own timing rules, so compare. For money from abroad, an international money transfer may avoid the slow collection that foreign checks face. Fees differ, so compare totals.
Is mobile check deposit worth using?
For most households, yes, with one condition. The service costs nothing at the banks cited here. It saves a trip. It lets you deposit at 8 p.m. on a Tuesday. If you receive only a few checks a year, the gap between the phone and an ATM is often too small to matter, at most one business day under the benchmark schedule.
The condition: treat the posted balance as provisional. Most of the harm described in this article comes from spending or sending money before a check is final, not from the app. Two groups should be more selective. Sellers who accept large checks from strangers face the highest fake-check exposure. People with thin balances face the highest cost from a reversal, because a negative balance can trigger fees. For both groups, waiting the extra day or two is cheap insurance.
Current Context as of October 2026
Only a few recent changes alter what you should do. They concern thresholds, government payments and fraud.
Regulation CC thresholds changed, but consumer pages lag
Since July 1, 2025, the next-business-day amount has been $275, up from $225. The large-deposit and new-account threshold rose from $5,525 to $6,725. The next scheduled reset is July 1, 2030.
At the time of our October 2026 review, the CFPB’s deposit-hold explainer, marked last reviewed August 28, 2026, still listed the older $225 and $5,525 figures. The regulation text controls. If a consumer page shows old numbers, trust the current rule and your bank’s own disclosure.
Federal paper checks are being phased out
Treasury announced that starting September 30, 2025, the federal government would stop issuing paper checks for most federal payments. Executive Order 14247, signed March 25, 2025, directed the change and allows exceptions for people without access to banking services.
Treasury’s page, last updated February 27, 2026, tells recipients to enroll in direct deposit through the paying agency, call 800-967-6857, visit GoDirect.gov or choose a Direct Express card. For you, that means fewer government checks to deposit. It does not touch checks from employers, landlords, insurers or individuals, which still move billions of dollars a year.
Check fraud pressure continues
FinCEN’s 2023 figures are the latest primary snapshot cited here, so check FinCEN’s site for newer analyses. Expect banks to keep using limits, reviews and holds on new accounts and unusual deposits. Fee schedules also keep shifting. Wells Fargo’s returned-deposit fee was $12 in the 2023 snapshot cited above and is none on its September 2026 page, so terms can move in either direction.
Questions to Ask Before You Deposit a Check by Phone
- ☐ What are my mobile check deposit limits for this account, per day and per month?
- ☐ What is the cutoff time, and in which time zone?
- ☐ When will the first dollar and the full amount be available?
- ☐ Does this deposit trigger a hold, and where will the notice appear?
- ☐ What exact endorsement wording does my bank require?
- ☐ How long should I keep the paper check, and how should I destroy it?
- ☐ Is this check type eligible, or should I take it to a branch?
- ☐ Who wrote the check, and can I verify the payer independently?
- ☐ If the check is returned, what happens to my balance and what fees apply?
- ☐ Am I about to send money out against a deposit that is not final?
Frequently Asked Questions
What is mobile check deposit, and how does it work?
Mobile check deposit is a bank-app feature that lets you photograph the front and back of a paper check and submit the images for credit. Your bank credits your account provisionally and sends the image to the bank that holds the writer’s account. That bank either pays the check or returns it.
The Check 21 Act, effective October 28, 2004, made image-based clearing possible. Your bank is not required to offer it, so terms vary.
Does mobile check deposit cost anything?
Usually not. Wells Fargo, Capital One and Bank of America each say they charge no additional fee for the service on the pages cited here. Carrier data rates may apply. The costs that matter come from returned items, overdrafts after a reversal, and any fee you pay to cash a check faster.
How long until mobile deposit funds are available?
It depends on your bank’s policy. Regulation CC offers a benchmark: the first $275 the next business day and most checks by the second business day. Banks that treat mobile deposits under their own terms may release money sooner or later. A hold, a cutoff miss or a weekend adds time. Read your funds availability disclosure.
What is the limit on mobile check deposits?
Limits vary by bank, account and history, and no federal rule sets one. Many banks show your limit in the app when you deposit. Ally publishes $50,000 per business day and $250,000 per 30 days for its eCheck Deposit. Other banks publish no amounts. Check your own app.
Why is my mobile deposit on hold?
Common triggers include a new account, a large amount, a history of overdrafts, an image problem or doubt about whether the check will be paid. Regulation CC lists specific exceptions, and bank agreements add discretion. You should receive a notice stating the reason and the release date. If you do not, ask in writing.
Can a mobile deposit be reversed after the funds are available?
Yes. Available funds are not final funds. If the paying bank returns the check, your bank can charge back the credit even if you already spent the money. The Uniform Commercial Code, a state law, says that right is not affected by your prior use of the funds. Fraud returns can take weeks.
Should I keep the check after a mobile deposit?
Follow your bank’s instruction. Wells Fargo says to keep it five days, then destroy it. Capital One says to keep it until the deposit shows in your transactions, then shred it. Where your bank is silent, keep the check until the full amount is available and posted correctly. Then destroy it securely.
Can I deposit a check made out to someone else?
Often not. Bank of America and Capital One list third-party checks among ineligible items. A check payable to another person involves an endorsement chain that banks view as risky. Ask the bank how it handles them. A branch visit with ID is the usual route.
What happens if I deposit the same check twice?
Both images reach the paying bank. One will be returned, and your bank reverses the matching credit. Your agreement may also make you responsible for losses from the duplicate. Look at your pending transactions before you retry, and redeposit only if the bank confirms the first attempt failed.
What are the pros and cons of mobile check deposit?
The advantages are convenience, evening access and no trip. Most banks charge nothing for it. The drawbacks are tighter limits on some accounts, holds with less teller context and exposure to fake-check scams. Duplicate-deposit risk also falls on you.
For routine checks from known payers, the pros usually outweigh the cons. For large, unfamiliar or urgent checks, the branch can be the better tool.
Is mobile check deposit safe?
The app is generally safe when you lock your phone, update the app and use the bank’s official download. The larger risks sit with the check: mail theft, check washing and fake-check scams. FinCEN reports that thieves favor ATM and remote deposits to avoid human contact. Verify unfamiliar payers and never send money against an unsettled deposit.
Can I deposit a check into a savings account by phone?
Often yes, but it depends on the bank and the account. Capital One says its mobile deposit works for eligible checking, savings and money market accounts. Other banks may limit the feature to certain accounts. Check the account picker in your app, then read the savings account’s own transaction rules.
Before your next deposit, open your bank’s mobile check deposit agreement or funds availability disclosure. Write down three numbers in your notes app: your limit, your cutoff time and the date the full amount becomes available. Check them against the confirmation screen the next time you deposit.
Mobile check deposit is convenient and generally safe for checks from payers you know. It is also provisional credit, not cash. The variable that matters most is whether anything depends on the money before the check is final. If rent, a closing or a wire does, count business days, assume a possible hold and wait. A deposit can be available and still be reversed, because availability and finality are separate clocks. If a stranger asks you to send money back, stop, because that pattern is the fake check scam. For a routine paycheck, take the photo and move on. Photograph the check on a dark, flat surface, confirm the amount, and keep the paper until the deposit posts. Your own deposit agreement, not a general rule, sets your limit, cutoff time and release date.
Methodology
This article was researched on October 6, 2026. Federal rules come from the Code of Federal Regulations, the Federal Register and Federal Reserve, CFPB, FinCEN, FTC and Treasury pages. State-law references use the Uniform Commercial Code text, which states adopt individually. Provider examples come from each provider’s own page, are dated and illustrate variation rather than describing your account.
Illustrative numbers carry the label “illustrative.” They were calculated with Python and rechecked. They are not current market quotes. Regulation CC’s reach over mobile deposits is debated, so the schedules shown are benchmarks, not promises. Third-party check-cashing fees were not verified and are described only generally.
Banktimer is independent of the providers named. This article is general information, not legal or financial advice. For a specific dispute, contact your bank, your state banking regulator or an attorney.
Sources
Primary official sources (accessed October 6, 2026)
- 12 CFR 229.10, next-day availability
- 12 CFR 229.12, availability schedule
- 12 CFR 229.13, exceptions to the schedule
- 12 CFR 229.19, deposit receipt and cutoff hours
- Federal Register, Availability of Funds and Collection of Checks, 89 FR 43737 (May 20, 2024)
- Federal Reserve, Check 21 Act consumer FAQ
- CFPB, How quickly can I get money after I deposit a check?
- FinCEN Alert FIN-2023-Alert003 on mail theft-related check fraud
- FinCEN Financial Trend Analysis on mail theft-related check fraud
- FTC, How to spot, avoid, and report fake check scams
- Treasury Fiscal Service, Paper checks going away
- Federal Reserve Payments Study, 2015 to 2024 key findings
- FDIC, Remote Deposit Capture: A Primer
Provider documents (dated examples, accessed October 6, 2026)
- Wells Fargo, Mobile Deposit FAQs
- Wells Fargo, Everyday Checking account fees summary (effective 7/28/2026)
- Wells Fargo, service fees (effective September 11, 2026)
- Capital One, Mobile Deposit disclosures
- Ally Bank, eCheck Deposit FAQ (January 20, 2026)
- Bank of America, Mobile Check Deposit
Legal text and secondary context
- UCC 4-214, right of charge-back or refund
- UCC 4-404, stale checks
- America’s Credit Unions, Expedited Funds Availability Act and Regulation CC, Part 2 (January 6, 2026)
- America’s Credit Unions, Remote Deposit Capture: Regulated by Contract or by Regulation CC? (March 13, 2017)
- MyBankTracker, Deposited Item Returned Fee Comparison at Top 10 U.S. Banks (September 10, 2023)
- Wikipedia, Remote deposit