By the Banktimer Editorial Team · Published
Banktimer is an independent U.S. consumer-finance publication. Our editors draw on primary and official sources first, such as the CFPB, FDIC, Federal Reserve, and FTC, along with statutes, regulations, and providers’ own agreements and fee schedules. Then we add worked examples and decision tools. Our goal is the most useful, best-supported explanation the sources available to us at the time of writing allow.
This article is general information, not legal, tax, investment, insurance, or financial advice, and reading it does not create a professional relationship with Banktimer. Rates, fees, limits, and rules change, and they vary by state, provider, and contract, so confirm current terms with your bank, lender, insurer, or the agency named in the article before you act. Examples are illustrative unless labeled otherwise. Banktimer is not a bank, lender, insurer, or financial advisor, and we are not responsible for decisions or losses that result from relying on this content. For advice about your own situation, talk to a licensed professional.
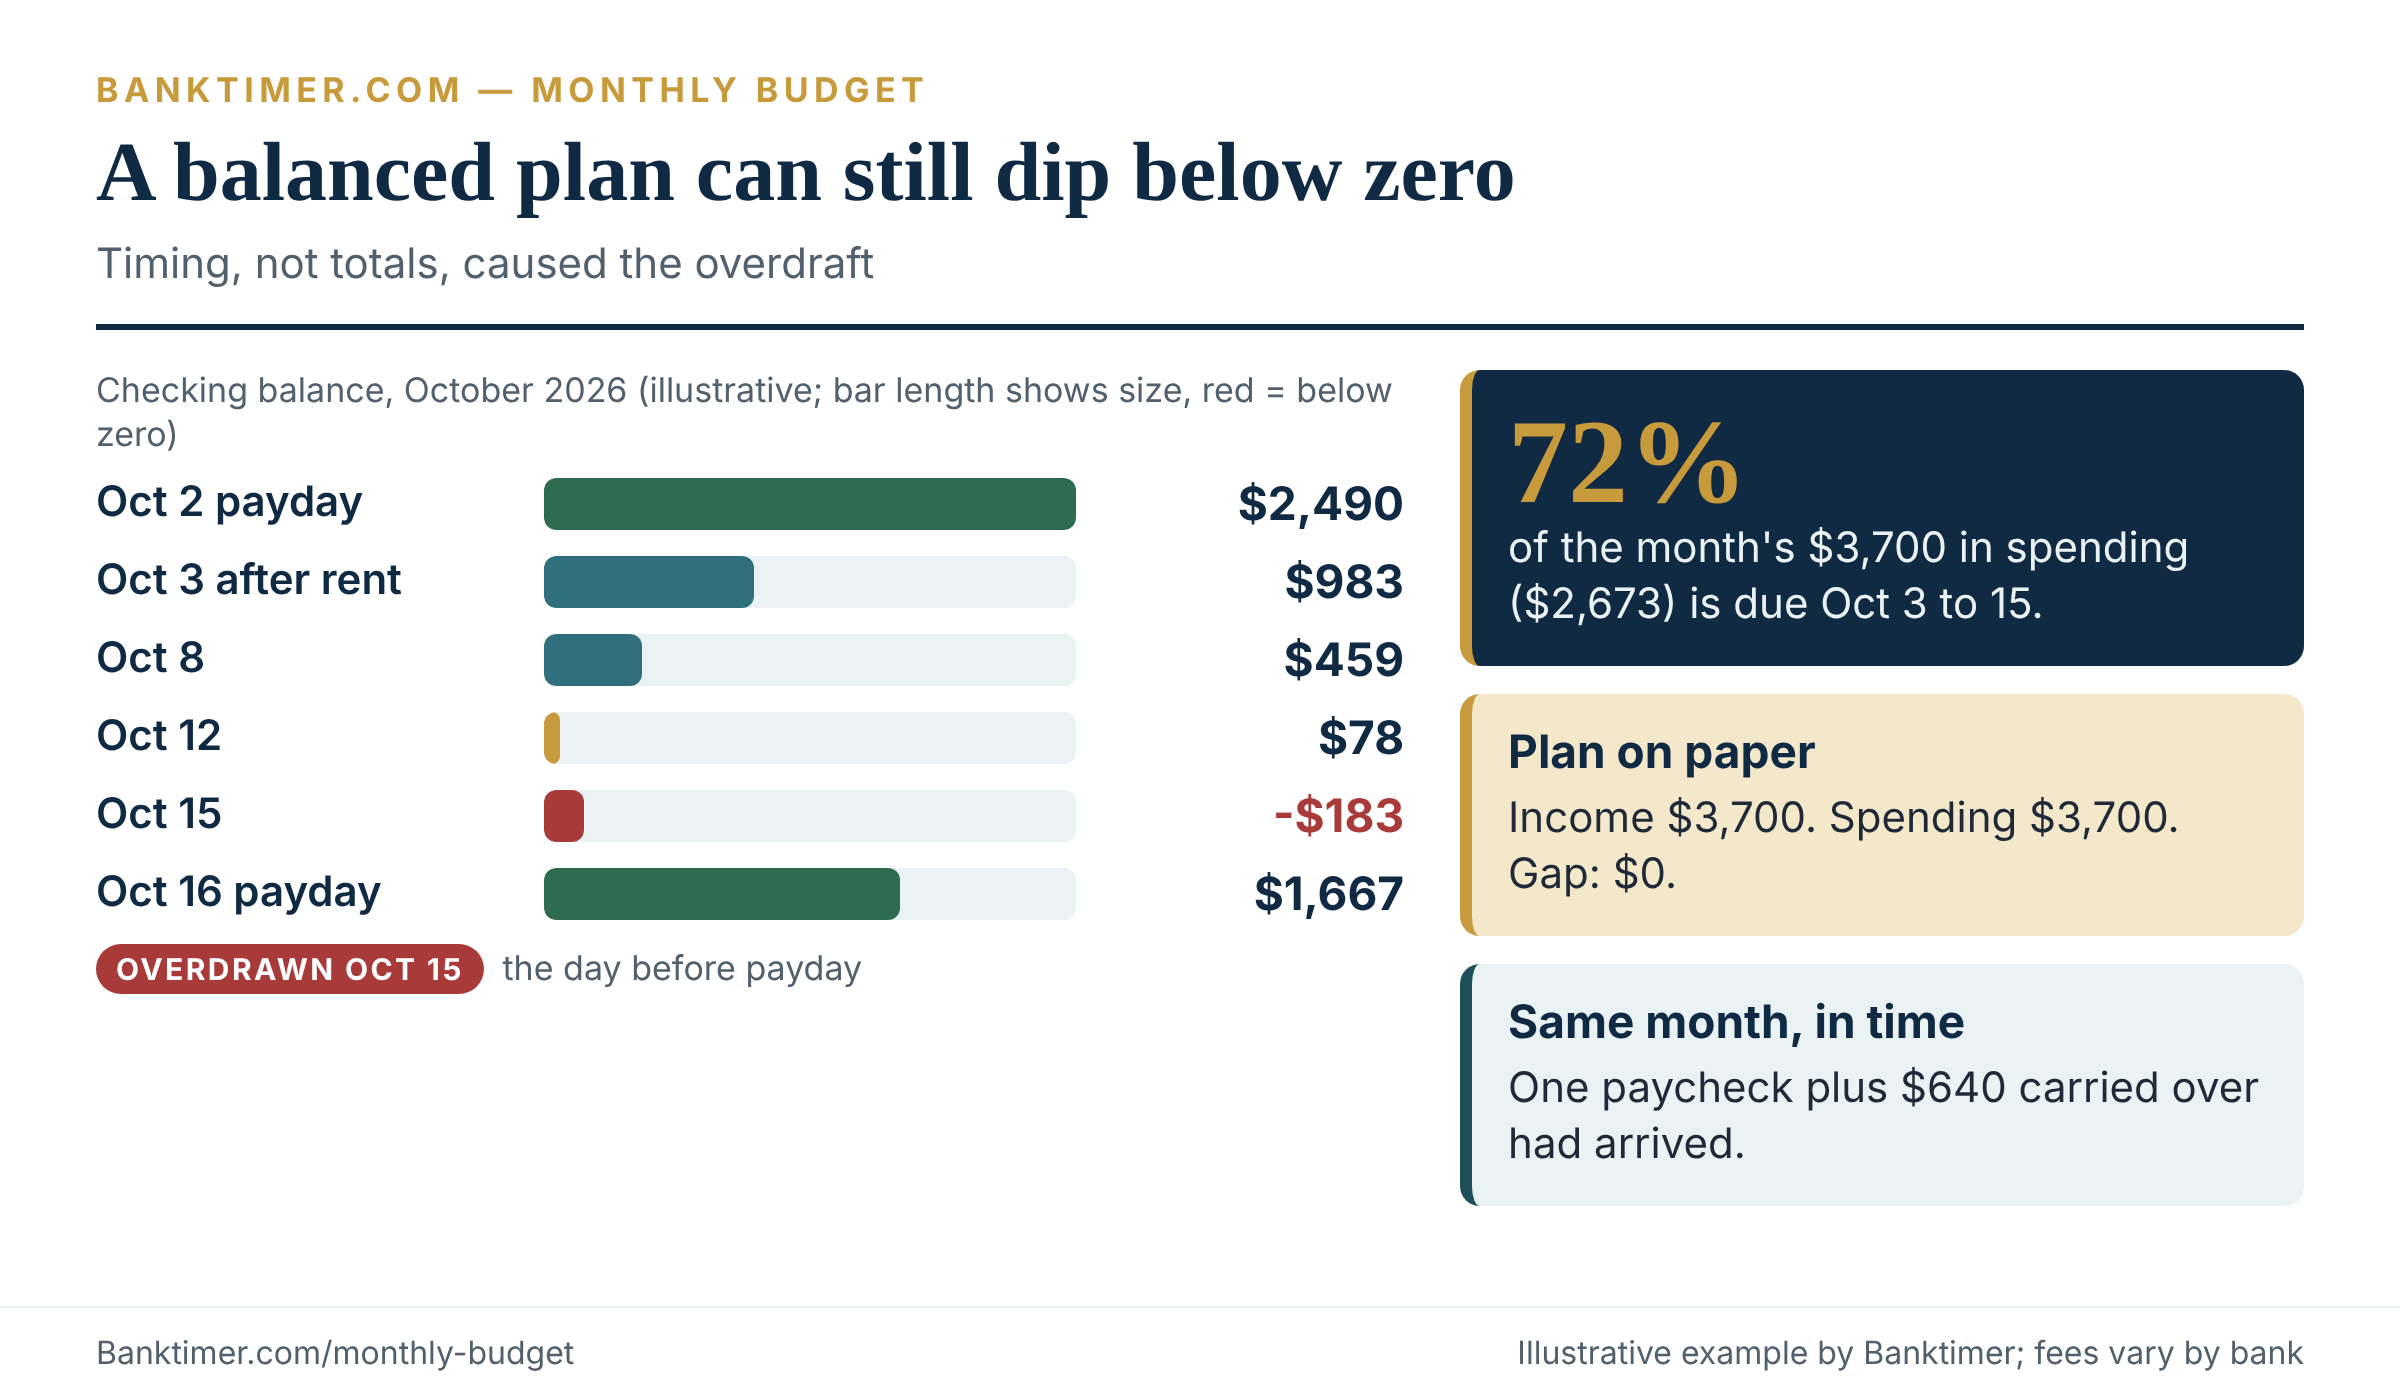
Picture an illustrative household we will call Sam and Jordan. They take home $1,850 every other Friday, so they built a monthly budget on $3,700 of income and $3,700 of planned spending. The spreadsheet balanced to the dollar. Then on Thursday, October 15, their checking account hit negative $183. Nothing strange had happened. About 72% of their bills came due in the first 15 days of the month, and payday was still a day away.
The fix was not a stricter budget. It was a $500 cushion, three moved due dates, and a plan built around paychecks instead of the calendar. This guide shows how to build that version, with computed examples, the rules of thumb that hold up, and the ones that break. (Sam and Jordan, and every household below, are Banktimer illustrations, not real customers.)
A monthly budget is a written plan that assigns your expected take-home pay to bills, everyday spending, debt payments, and savings for the month, then compares the plan with what happened. It works when it uses income you can count on, sorts costs by how predictable they are, matches due dates to paydays, and keeps a cash cushion. The biggest variable is timing, not totals. Check your pay calendar and your bill dates before you pick any method.
Key Takeaways at a Glance
Totals are not enough. A budget that balances for the month can still overdraw mid-month. Compare when money arrives with when each bill is due.
Sort costs before you cap them. Fixed costs get set once. Variable costs get an estimate from real statements. Irregular costs get a monthly set-aside so they stop feeling like emergencies.
The cushion does the heavy lifting. A checking floor, sinking funds, and an emergency fund have three different jobs. A monthly budget without them fails on the first surprise.
Match the method to your problem. Zero-based, 50/30/20, envelope, and pay-yourself-first solve different problems. Most lasting systems combine two.
Automate the transfers, review the spending. Automation protects savings and bill dates. It does not replace a short monthly look at what actually happened.
Some people can skip the detail. If automatic saving is in place and the cushion is solid, a line-by-line budget may cost more attention than it returns.
The Numbers That Shape a Monthly Budget in Late 2026
Start with the context, because it changes how much cushion a monthly budget needs. The figures below are national measurements, not targets. Use them to sanity-check your own plan, not to grade yourself.
| Measure | Latest figure | Source and date | What it means for your plan |
|---|---|---|---|
| Adults who could cover a $400 expense with cash or equivalent | 63% (same as 2024; 68% in 2021) | Federal Reserve SHED, survey fielded October 2025, issued May 13, 2026 | A cushion is the weak spot for about 1 in 3 adults |
| Adults with a major unexpected expense in the past year | 59% (vehicle 30%, home or appliance 22%, medical 21%) | Federal Reserve SHED, same report | Irregular costs are normal, so plan for them |
| Average household spending, 2024 | $78,535 a year, about $6,545 a month | BLS Consumer Expenditure Survey, released December 19, 2025 | A benchmark for scale, not a target |
| Housing share of average spending, 2024 | 33.4% ($26,266 a year, about $2,189 a month) | BLS Consumer Expenditure Survey | Housing alone can use a third of the budget |
| Personal saving rate, August 2026 | 4.1% of disposable income | BEA, released September 30, 2026 | A national average, not a goal |
| Consumer prices, August 2026 | +3.4% over 12 months (food at home +2.2%, shelter +3.0%, gasoline +27.4%) | BLS CPI, released September 11, 2026 | Rebuild variable lines from recent statements |
| Card interest rate, second quarter 2026 | 22.15% on accounts assessed interest | Federal Reserve G.19, released September 8, 2026 | Carrying a balance can outweigh most savings |
Why the cushion number matters most
The Federal Reserve’s household survey found that 63% of adults could cover a $400 emergency expense using cash, savings, or a card paid off at the next statement. That share was unchanged from 2024 and below the 68% of 2021. The other 37% could not cover it that way. Fifty-nine percent of adults had at least one major unexpected expense in the prior 12 months.
Those two numbers explain why budgets fail. People rarely overspend on a line item by much. They hit a $600 car repair with no buffer, and the plan collapses around it.
Averages are scale checks, not rules
Federal consumer spending data show households spent an average of $78,535 in 2024 against average pre-tax income of $104,207. Housing took $26,266, or 33.4% of spending. By Banktimer’s arithmetic, that is roughly 25% of average pre-tax income. The averages blend renters, owners, and every income level, so your numbers will differ. BLS has signaled a 2025 release for late October 2026, so these benchmarks will update soon.
Prices matter too. The August CPI report showed all items up 3.4% over 12 months, with gasoline up 27.4% and food at home up 2.2%. If gas is a line in your plan, rebuild it from the last three months of statements, not last year’s habit. Savings are thin nationally too: BEA reported a personal saving rate of 4.1% for August 2026. That figure averages all households and says nothing about the one you should aim for.
How a Monthly Budget Works
The mechanics are simple. The discipline is in choosing honest inputs. A budget has three parts: expected income, assigned spending, and a comparison step at the end of the month.
A cash-flow plan, not a diary
You list the take-home pay you expect, meaning what lands in your account after taxes and payroll deductions. You assign every dollar to a job: bills, food, transportation, debt payments, savings, and personal spending. At month’s end you compare plan with reality and adjust.
The Consumer Financial Protection Bureau’s budgeting guide uses four steps: an income tracker, a spending tracker, a bill calendar, and a budget worksheet. Notice that the bill calendar sits in the middle. Timing is part of the plan from the start, not a late fix.
The three jobs a budget does
First, it shows you where money goes. Most people underestimate small, frequent purchases and overestimate how much slack they have. Second, it assigns money before you spend it, which turns “I hope there is enough” into “this dollar already has a job.” Third, it gives early warning. A grocery line at 80% on the 18th tells you something while you can still act.
A monthly budget that does only the first job is a spending log. Logs are useful. They are not plans.
Why “monthly” is a convenient fiction
Rent, insurance, and most utilities bill monthly. Many paychecks do not. Biweekly pay arrives 26 times a year, semi-monthly pay 24 times, and weekly pay 52 times. The month is a reporting unit that your landlord and lender chose. Your paycheck is the real unit of cash.
That mismatch drives most mid-month shortfalls, and it gets its own section below. A good monthly budget keeps the monthly view for planning and adds a pay-period view for cash.
What a budget is not
It is not a prediction. Real months include a flat tire or a birthday. It is not a moral report card either. If a category runs over plan three months in a row, the estimate was wrong, not you. Change the number.
And it is not a diet. A plan with zero room for choice tends to get abandoned in week two. Build in spending money on purpose, and treat it as a feature.
Fixed, Variable, and Irregular Costs: Sorting Your Money
Before you pick a method, sort every cost by how it behaves. The sort tells you which lines to set once, which to estimate, and which to turn into monthly set-asides.
| Cost type | Typical examples | How it behaves | How to budget it | How often to review |
|---|---|---|---|---|
| Fixed | Rent or mortgage, car payment, childcare, loan minimums | Same amount, same date | Enter exactly; put due date on the bill calendar | When a contract or rate changes |
| Variable essentials | Groceries, gas, utilities, phone data | Needed, but the amount moves | Start from a three-month average; check mid-month | Monthly |
| Choice spending | Dining out, hobbies, shopping, subscriptions | Flexible, often emotional | Give it a fixed amount; consider a separate card or account | Monthly |
| Irregular but predictable | Insurance premiums, registration, holiday gifts, annual fees | Lumpy, known in advance | Divide by 12 (or 26) and move the money monthly | Quarterly |
| Irregular and unpredictable | Car repair, medical bill, appliance failure | Random timing and size | Hold a cash buffer; refill after use | After each use |
| Debt and taxes | Card payments, estimated tax | Fixed minimum, flexible extra | Minimum is fixed; extra is a decision | Monthly |
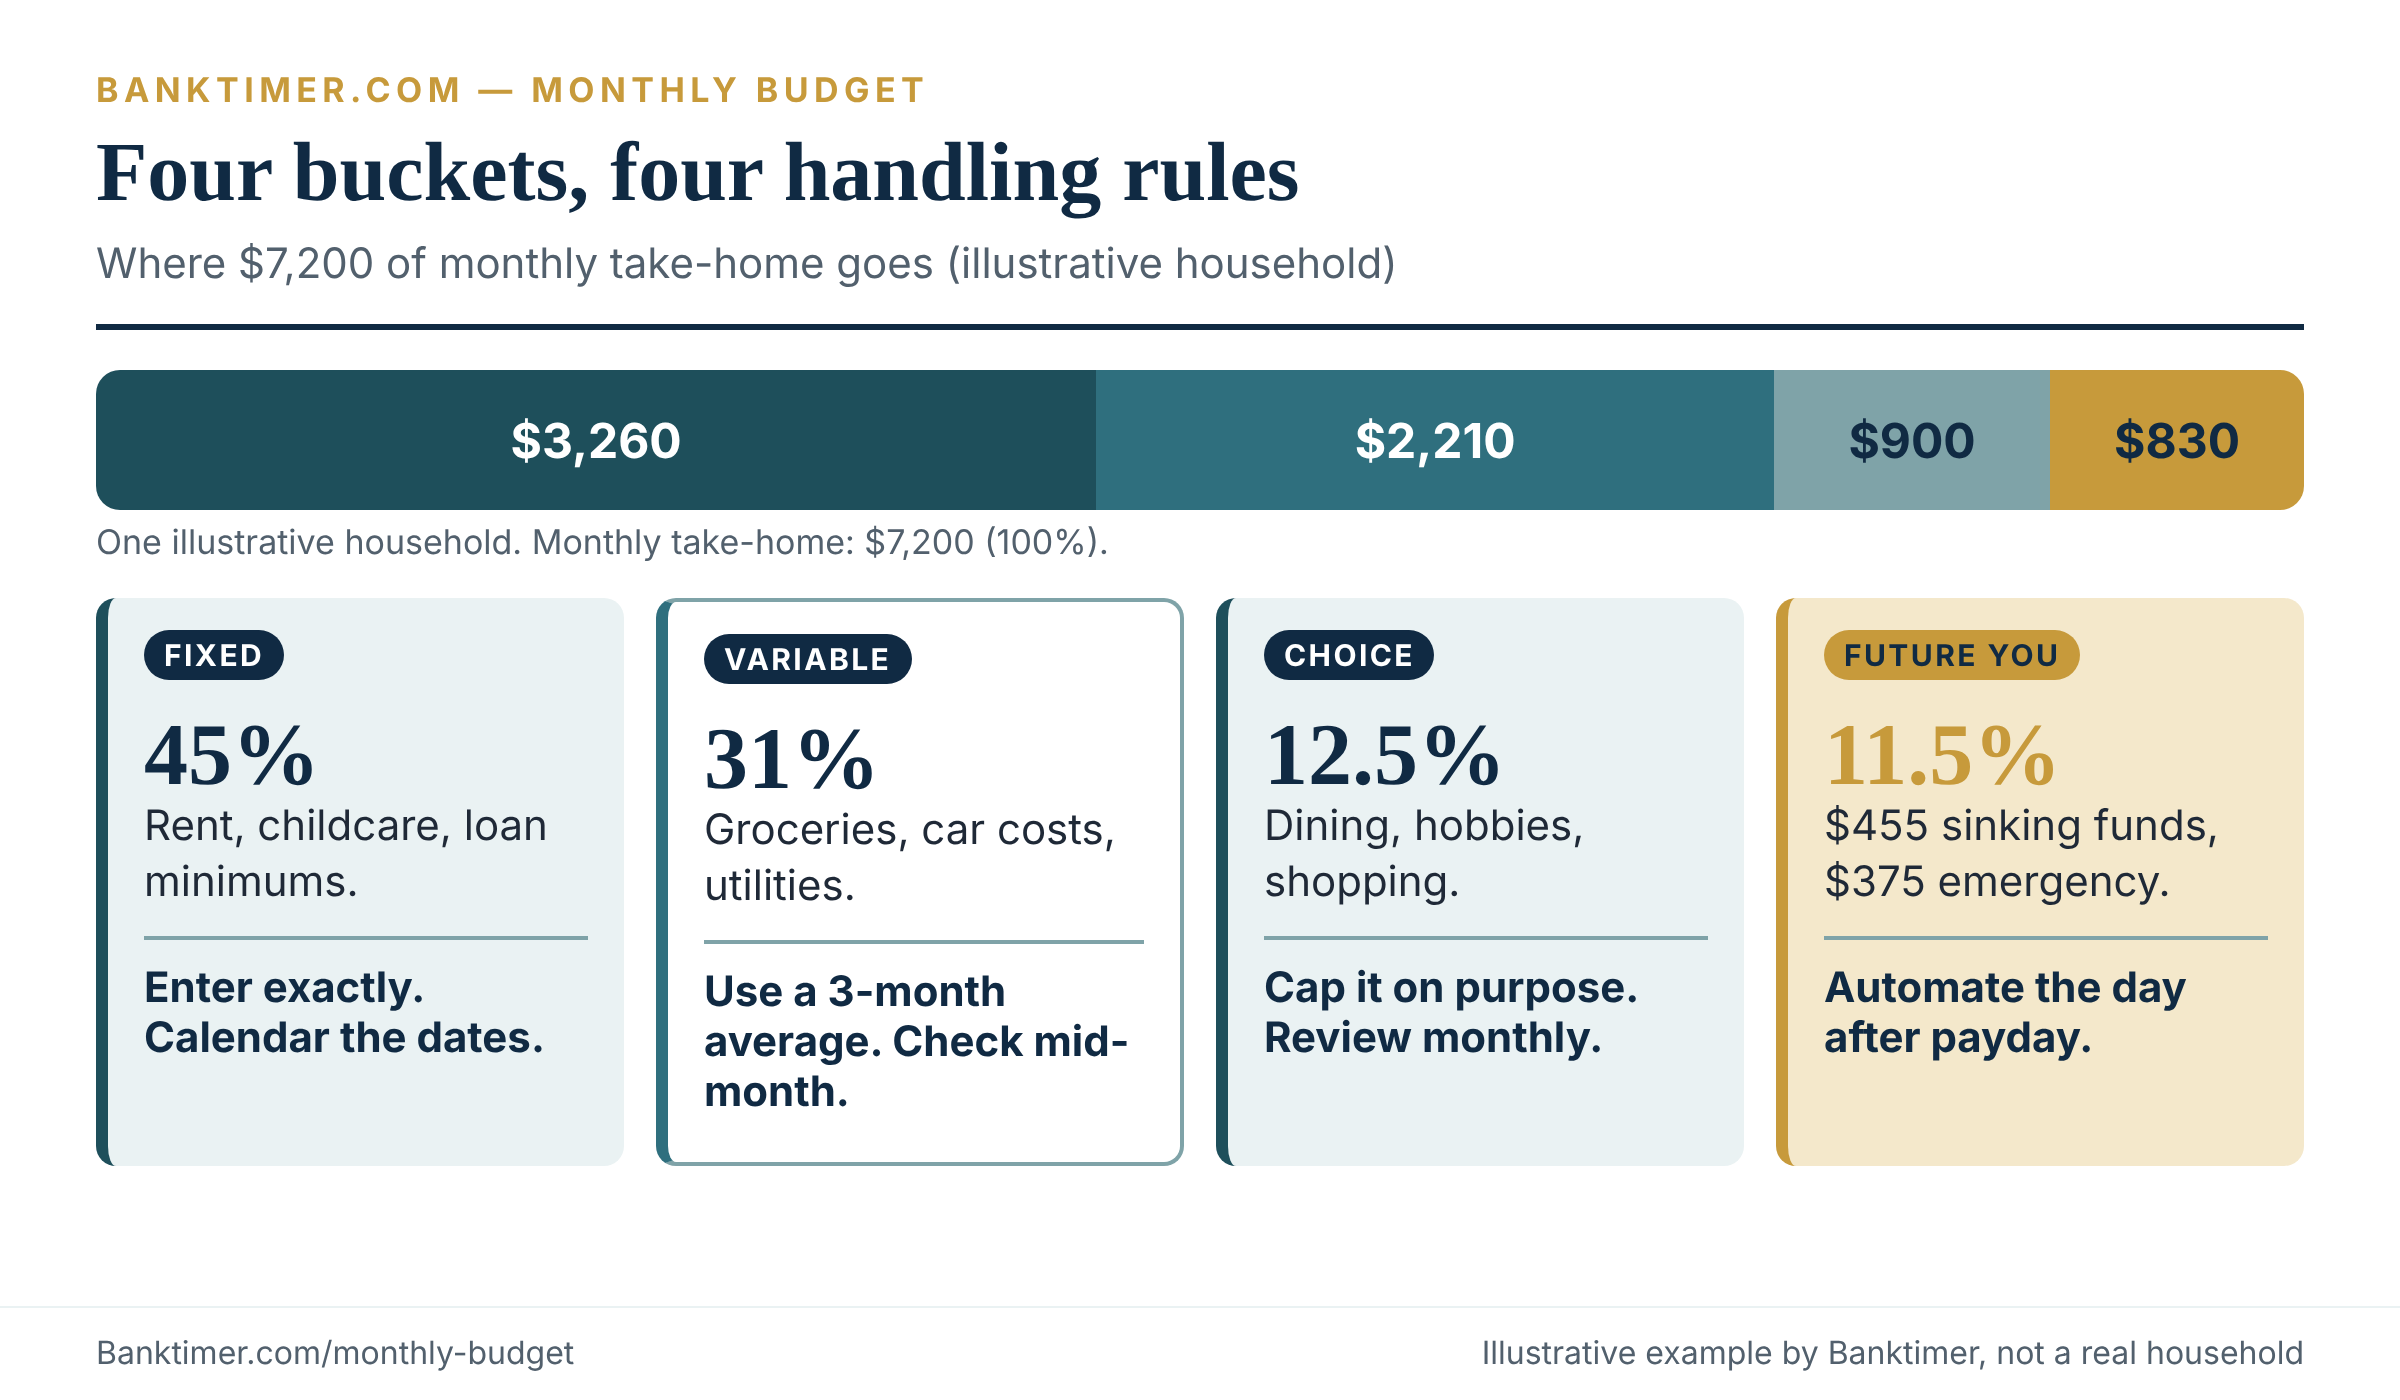
Fixed costs: set once, calendar always
A fixed cost has the same amount on the same date. You do not budget it so much as place it. The planning work is on the calendar. Write down the due date of every fixed bill, because a fixed amount with a bad date still causes an overdraft.
The infographic above uses an illustrative dual-income household. Its fixed costs are $2,050 rent, $900 childcare, and $310 in loan minimums, or $3,260 of $7,200. That is 45% of take-home, and none of it responds to willpower.
Variable costs: where budgets live or die
Groceries, gas, and utilities move month to month. They are needs, so cutting them has limits. Estimate them from the last three months of statements, not from memory. Memory is generous.
Then check the number once mid-month. If you are at 70% of the grocery line by the 12th, you have time to adjust. At 100% on the 25th you do not. In the same household, variable needs total $2,210: $980 groceries, $640 car costs, $330 utilities and internet, and $260 medical.
Irregular costs: the ones that ambush a monthly budget
Some costs are not monthly but are perfectly predictable: a six-month car insurance premium, registration, a holiday season, an annual subscription. A monthly budget that ignores them looks fine for ten months and fails in the eleventh. Divide each by 12, or by 26 if you budget by paycheck, and move that amount into a separate savings pot every pay period. That is the core idea behind a sinking fund.
Holidays are the classic case. A plan for the season built in October is already late, which is why a holiday budget works better as a monthly set-aside starting in January. Then there are the truly random costs. The Federal Reserve survey found 30% of adults paid for major vehicle repair or replacement in a year, 22% for home or appliance repairs, and 21% for a major medical bill. You cannot predict which one hits you. You can predict that something will.
Debt and taxes as their own class
Minimum debt payments are fixed costs, but any amount above the minimum is a choice, so it deserves its own line. A later section runs the numbers on payoff order. If you earn self-employment income, income tax is a cost the paycheck never withheld. Treat it as a monthly set-aside, as shown in the irregular income example below.
Pay-Period Versus Calendar-Month Budgeting
A calendar-month plan answers one question: does the month add up? A pay-period plan answers a harder one: is there enough in the account on each date a bill leaves? You need both answers, and only the second one prevents overdrafts.
Why the calendar misleads
Rent is due on the 1st through the 5th for many households. Car payments, insurance, and credit card minimums often cluster in the first half of the month too. Paychecks follow their own rhythm. The result is a lumpy line: heavy outflows early, light ones late, income arriving on a different pattern again.
The Consumer Financial Protection Bureau has flagged this directly. Its research found that one reason people fell behind on bills was that due dates and income streams were not aligned. That is a timing problem, not a spending problem.
Biweekly pay is not “twice a month.” An employee paid every other Friday receives 26 checks a year. Planning on 24 checks means real income runs 8.3% above what the plan shows. For a $1,850 check, that is $3,700 a year that never appears in a two-checks-a-month plan. With Sam and Jordan’s schedule, the three-payday months are May and October in 2026, and April and October in 2027.
How pay frequency changes the math
Your pay schedule decides how many paychecks land in a given month. The conversion matters because a monthly budget needs one number for monthly income, and the wrong conversion quietly shifts every other line.
| Pay schedule | Paychecks a year | Months with an extra check | Monthly equivalent of a $1,000 check | Planning note |
|---|---|---|---|---|
| Weekly | 52 | Four months have five | $4,333.33 | Budget on four checks, treat the fifth as extra |
| Biweekly | 26 | Two months have three | $2,166.67 | Do not budget as if it were twice a month |
| Semi-monthly | 24 | None | $2,000.00 | Dates are fixed, so bills can match them |
| Monthly | 12 | None | $1,000.00 | One check must stretch across every bill date |
The monthly equivalent is the paycheck times the checks per year, divided by 12. For a biweekly $1,000 check, that is $26,000 divided by 12, or $2,166.67. Use it for annual planning, such as how much a sinking fund can take. Use the conservative two-check figure for the monthly plan itself. The difference is your cushion for the year.
Illustrative example: Sam and Jordan, day by day
Here is the full month behind the opening paragraph. The assumptions are Banktimer’s, chosen to be realistic, not drawn from any real account. Paydays fall on October 2, 16, and 30 at $1,850 each. The account holds $640 on October 1, left over from the September 18 paycheck. Planned spending is $3,700: $1,375 rent, $362 car payment, $92 phone, $214 electric and gas, $85 card minimum, $176 car insurance, $240 student loan, $75 internet, $38 streaming, $660 groceries and gas, $140 dining out, $143 kids and household, and $100 savings.
Planned income is two paychecks, $3,700. Planned spending is $3,700. On paper the gap is zero. The account tells a different story, because $2,673 of the month’s spending, or 72%, falls due between October 3 and October 15.
| Date (October 2026) | What happens | Amount | Running balance |
|---|---|---|---|
| Oct 1 | Starting balance | n/a | $640 |
| Oct 2 | Payday | +$1,850 | $2,490 |
| Oct 3 | Rent and weekly groceries and gas | -$1,507 | $983 |
| Oct 4 to 6 | Car payment and kids and household | -$432 | $551 |
| Oct 8 | Phone | -$92 | $459 |
| Oct 9 to 10 | Dining out and weekly groceries and gas | -$167 | $292 |
| Oct 12 | Electric and gas | -$214 | $78 |
| Oct 14 | Credit card minimum | -$85 | -$7 |
| Oct 15 | Car insurance | -$176 | -$183 |
| Oct 16 | Payday | +$1,850 | $1,667 |
| Oct 17 to 29 | Student loan, internet, streaming, groceries, and other spending | -$895 | $772 |
| Oct 30 | Payday (third of the month) | +$1,850 | $2,622 |
| Oct 31 | Last weekly groceries and gas | -$132 | $2,490 |
The table shows the problem in one line: the account ends the month $1,850 richer than it started, yet it was negative for part of the third week. Overdraft and insufficient-funds fees vary by bank, so check your own fee schedule. The account would also pay the price in stress, not just in fees.
Three-payday months hide the pattern
The October 30 paycheck is why Sam and Jordan ended the month with $2,490. It is also why the problem is easy to miss. A month with an extra check feels fine at the end. The same bill pattern in a two-payday month, with no extra check to pad the balance, would leave the account at zero or below after the first week.
Treat the two extra checks as planned windfalls. Budget on the two-checks-a-month figure, then assign the third check in advance to a named job such as a sinking fund, a debt payment, or the emergency fund. Otherwise it drifts into everyday spending.
Three fixes, in order of effort
Fix one: a checking cushion. The worst point was negative $183. Starting the month with $500 more would have kept the low point at positive $317. A cushion is the fastest fix and the easiest to remember.
Fix two: move the due dates. Electric, the card minimum, and car insurance moved to the 17th, the day after payday. In this example the lowest balance becomes $292 and the account never goes negative. The CFPB notes that some billers will change due dates on request, though not all will. Ask what else changes. For a credit card, ask whether the statement closing date moves, and read how your grace period works first.
Fix three: assign each bill to a paycheck. Paycheck one covers everything due from the 3rd through the 15th. Paycheck two covers the 16th through the 2nd. The approach is covered in detail in budget by paycheck. If you track cash week by week, a cash flow budget works on the same logic. The CFPB’s own cash-flow worksheet records a starting balance, adds income, subtracts expenses, and carries the ending balance to the next week.
A Decision Framework: Which Budget Method Should You Choose?
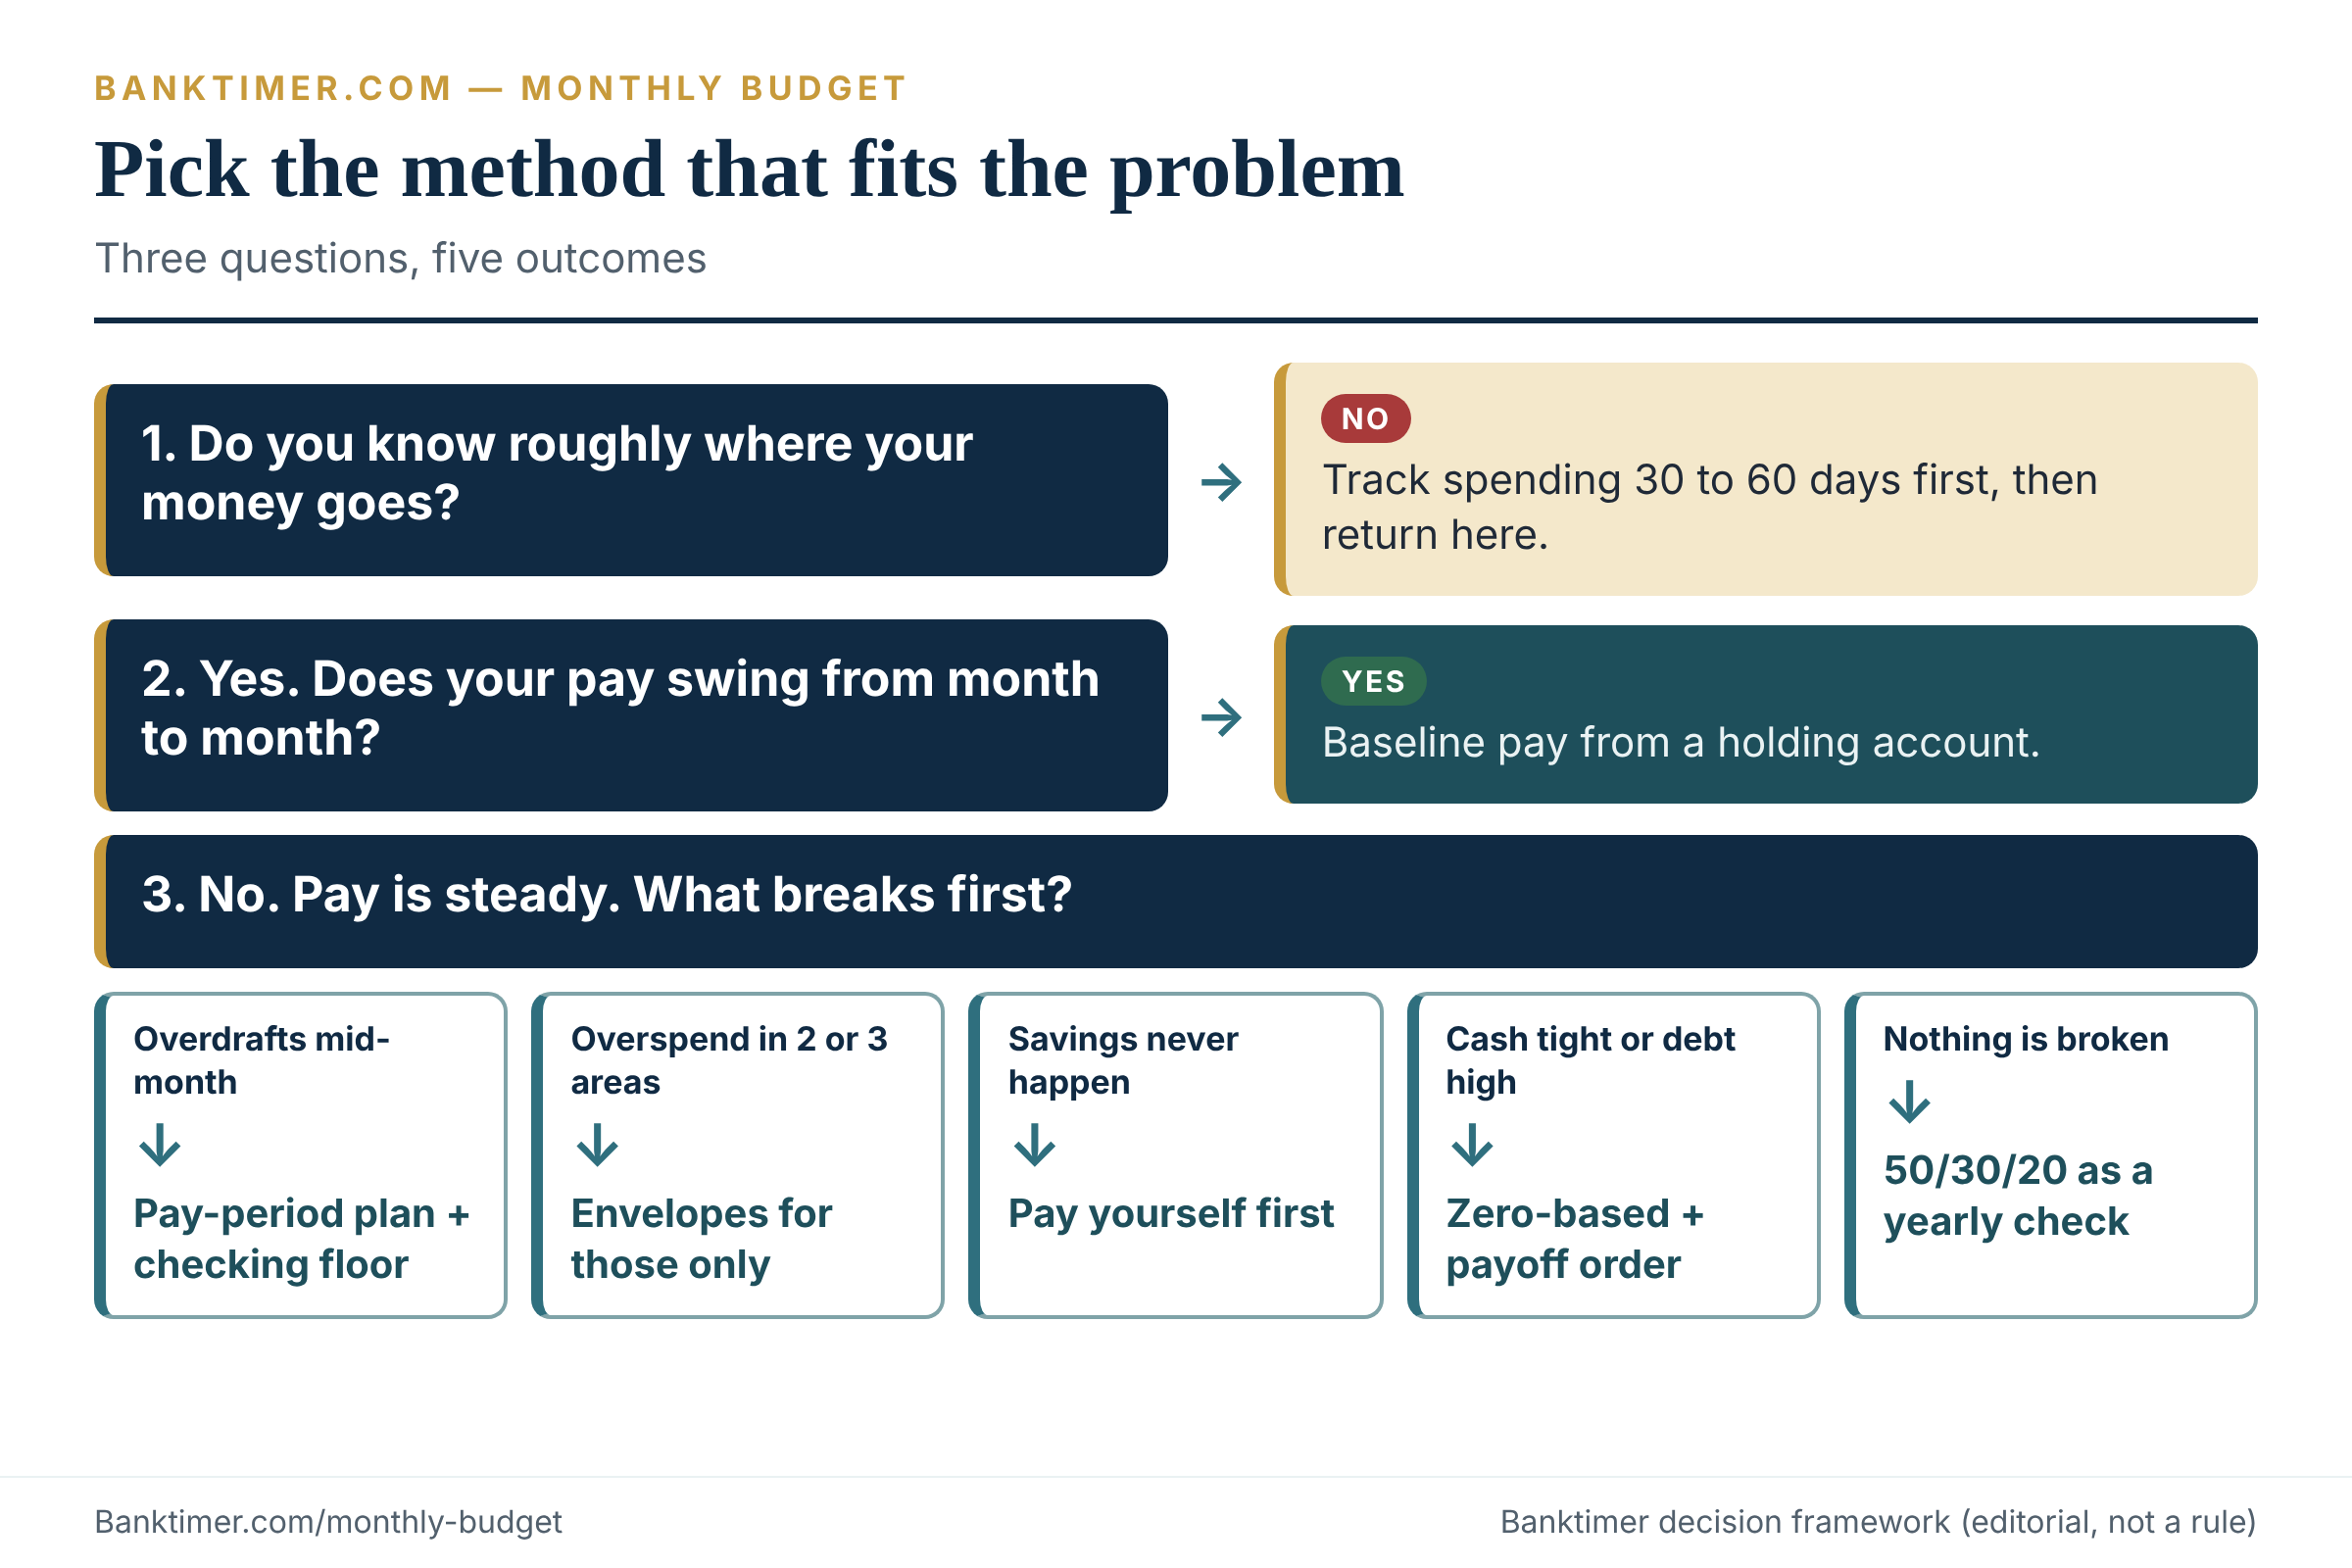
Methods differ in what problem they solve. Zero-based budgeting allocates. The 50/30/20 split sets guardrails. The envelope method caps variable spending. Pay-yourself-first protects saving. Pick the one that targets your failure point, not the one with the most followers.
| Method | Best for | Main upside | Main downside | What to verify |
|---|---|---|---|---|
| Zero-based | Tight cash flow, debt payoff, irregular needs | Every dollar has a job, so leaks show up | Takes time to set up and maintain | Do income and expense totals match your pay calendar? |
| 50/30/20 | A quick sanity check or a first plan | Three categories, easy to remember | Needs often exceed 50% in high-cost areas | Does your housing cost already break the 50% line? |
| Envelope (cash or digital) | Overspending in groceries, dining, or shopping | Hard stop when the envelope empties | Awkward for bills and card spending | Is the cash or sub-account actually separate? |
| Pay yourself first | People whose savings never happen | Savings leave before spending starts | Does not control the rest of the money | Will the transfer date clear after payday? |
| Pay-period (by paycheck) | Mid-month shortfalls, mismatched due dates | Fixes timing directly | More bookkeeping than a monthly view | Do bills fall on dates you can change? |
Zero-based budgeting: every dollar gets a job
In a zero-based plan, income minus assigned spending, debt, and savings equals zero. The point is not to spend everything. A dollar assigned to savings still has a job. The method forces you to decide before the money moves, which is why it suits tight budgets and debt payoff. See the dedicated guide to a zero-based budget for the full process.
The cost is attention. You rebuild the plan each month, and each pay period if income is lumpy. Skip it if you have a large surplus and no confusion about where money goes.
The 50/30/20 split and where it breaks
The rule assigns 50% of after-tax income to needs, 30% to wants, and 20% to savings and debt payoff. It is a rule of thumb, not a regulation or a standard. As a quick check it is useful. As a rigid target it can mislead.
The 50/30/20 split is usually credited to Elizabeth Warren and Amelia Warren Tyagi’s 2005 book All Your Worth. It was aimed at middle-class readers as a simple frame, not as a cap that fits every city or family size.
Housing alone averaged 33.4% of household spending in the BLS 2024 data. That leaves only 16.6 points of the 50% for everything else a household needs. In the illustrative dual-income household with two children, needs total $5,470 of $7,200, or 76%. Wants are $900 (12.5%) and savings are $830 (11.5%). The split fails the 50/30/20 test, and nobody did anything wrong. The target simply does not fit a family with childcare costs. A fuller treatment is in the guide to the 50/30/20 budget.
Envelope method: hard stops for the leaky categories
You put a fixed amount into an envelope for a category, often cash, and stop spending when it is empty. Digital versions use separate sub-accounts or a prepaid card. It works well for groceries, dining, and shopping because the limit is visible and immediate.
It fits poorly with bills and card payments, which do not run through envelopes. Many people use it for two or three leaky categories only. That keeps the system small enough to survive.
Pay yourself first: protect the transfer
You move savings out on payday, before you can spend it, and live on what remains. The Consumer Financial Protection Bureau describes automatic transfers to savings as a way to save regularly without thinking about it, including recurring bank transfers and splitting direct deposit. The method protects saving. It says nothing about the rest, so a household with credit card debt still needs a plan for the other 90% of the paycheck.
Rules for choosing a method
Use these rules in order. They are a Banktimer framework, not a regulation.
- If you do not know where the money goes, track spending for 30 to 60 days before choosing anything.
- If your pay varies, use a baseline method with a holding account, shown in the irregular income example below.
- If you overdraft mid-month, use pay-period budgeting and a checking floor first.
- If you overspend in two or three categories, add envelopes for those only.
- If savings never happen, automate a transfer on payday before anything else.
- If cash is tight or debt is high, go zero-based and pick a payoff order.
- If none of this applies, use 50/30/20 as an annual check and skip the rest.
Rules of Thumb for a Monthly Budget: What Holds Up and What Breaks
People often ask for the rules of a monthly budget as if a regulator had written them. Almost none are law. Some are federal requirements, some are popular rules of thumb, and some are Banktimer’s own editorial suggestions. The table separates them, because treating a rule of thumb as a legal limit leads to bad decisions.
| Rule | Where it comes from | Holds up when | Breaks when | Type |
|---|---|---|---|---|
| 50/30/20 split | Warren and Tyagi, All Your Worth (2005) | Housing and fixed costs are moderate | Rent, childcare, or debt push needs past 50% | Popular rule of thumb |
| Budget on take-home pay | Basic cash-flow logic | Always for employees | Self-employed income, where taxes are not withheld | Editorial standard |
| Keep a checking floor | Banktimer suggestion | Pay and due dates are misaligned | Never harmful, but the size varies | Editorial suggestion |
| Three to six months of essentials saved | Common planner guideline | Stable income, few dependents | One income, variable pay, or high fixed costs | Industry rule of thumb |
| Stop a preauthorized payment three business days ahead | Regulation E, 12 CFR 1005.10(c) | Recurring electronic payments from a consumer account | Other payment types, where your agreement controls | Federal regulation |
| Estimated tax if you expect to owe $1,000 or more | IRS rules for individuals | Income without enough withholding | Withholding already covers your tax | Federal tax rule |
Read the last column first. Only two rows are legal requirements, and each applies in specific conditions. Everything else is a guideline that you can adjust without penalty.
The practical rule for any monthly budget is this: use a guideline to ask a question, not to settle an answer. If your needs run 76% of take-home, the 50/30/20 rule is telling you to look at housing and childcare costs. It is not telling you that you failed.
Three Illustrative Households, Computed
Abstract rules only go so far. These three households show how the same tools behave under different pressure. All numbers are Banktimer illustrations, chosen to be realistic, with the arithmetic checked in Python. None is a live market quote or a real family.
| Line | A: dual income, two children | B: single earner with card debt | C: irregular self-employed income |
|---|---|---|---|
| Monthly take-home | $7,200 | $3,650 | $2,137.50 baseline pay |
| Needs (housing, food, transport, childcare, minimums) | $5,470 (76.0%) | $2,470 (67.7%) | $1,500 (70.2%) |
| Choice spending | $900 (12.5%) | $560 (15.3%) | $300 (14.0%) |
| Debt payments beyond minimums | $0 | $350 (9.6%) | $0 |
| Savings and sinking set-asides | $830 (11.5%) | $270 (7.4%) | $337.50 (15.8%) |
| Main timing issue | Two pay schedules | 26 biweekly paychecks | Uneven monthly deposits |
| Method that fits | Zero-based plus pay-by-paycheck | Zero-based plus a payoff order | Baseline pay plus holding account |
The table shows why one rule cannot fit everyone. Needs run from 68% to 76% of take-home in these households, well above the 50% in the popular split. The differences that matter are in the bottom two rows, not the percentages.
Household A: two incomes, two pay schedules
The first earner takes home $1,938.46 every other Friday, which is $4,200 a month on average. The second takes home $1,500 on the 1st and 15th, or $3,000 a month. Together that is $7,200. The first earner’s schedule produces two three-check months a year. The second never does.
Needs total $5,470: rent $2,050, groceries $980, car payments and gas $640, childcare $900, utilities and internet $330, medical $260, and loan minimums $310. Savings and set-asides are $830, made up of $455 for sinking funds and $375 for the emergency fund. The sinking funds cover items such as insurance premiums, which a strict 50/30/20 reading would count as needs. Count them that way and needs rise to $5,925, or 82.3%.
The plan works because childcare and rent are placed on the calendar first, and the 1st-and-15th paycheck covers the early-month bills. The biweekly check handles the rest. Extra checks go to the emergency fund.
How couples can split shared costs
Take the same household. The shared pool is $6,300: needs of $5,470 plus $830 of savings and set-asides. An even split would assign $3,150 to each person. The second earner takes home only $3,000, so that split is impossible. A proportional split works instead. The first earner brings in 58.3% of take-home and the second 41.7%, so they contribute $3,675 and $2,625. Each is left with 12.5% of take-home, or $525 and $375 for personal spending.
Proportional splits mean both partners keep the same share of their own pay. If you hold accounts jointly, a joint bank account can hold the shared pool while each person keeps a small personal account. Banktimer does not recommend one structure for every couple. The right one depends on income gaps, trust, and whether either person carries debt the other did not take on.
Household B: one income, three cards
Household B takes home $3,650 a month, paid biweekly at $1,684.62. Needs are $2,470: rent $1,180, utilities $160, groceries $380, phone $55, gas and insurance $260, health $60, and card minimums $375. Choice spending is $560. The remaining $620 goes to an extra $350 toward debt, a $120 sinking fund, and $150 toward a checking cushion.
Three illustrative cards carry $14,100 in total. Their weighted interest rate is about 24.2%, and month-one interest is about $284. The next section runs the payoff order. The budget’s job is simple: protect the $350 extra payment from the first surprise. Without a cushion, one car repair puts that payment back on a card.
Household C: irregular income, built from a baseline
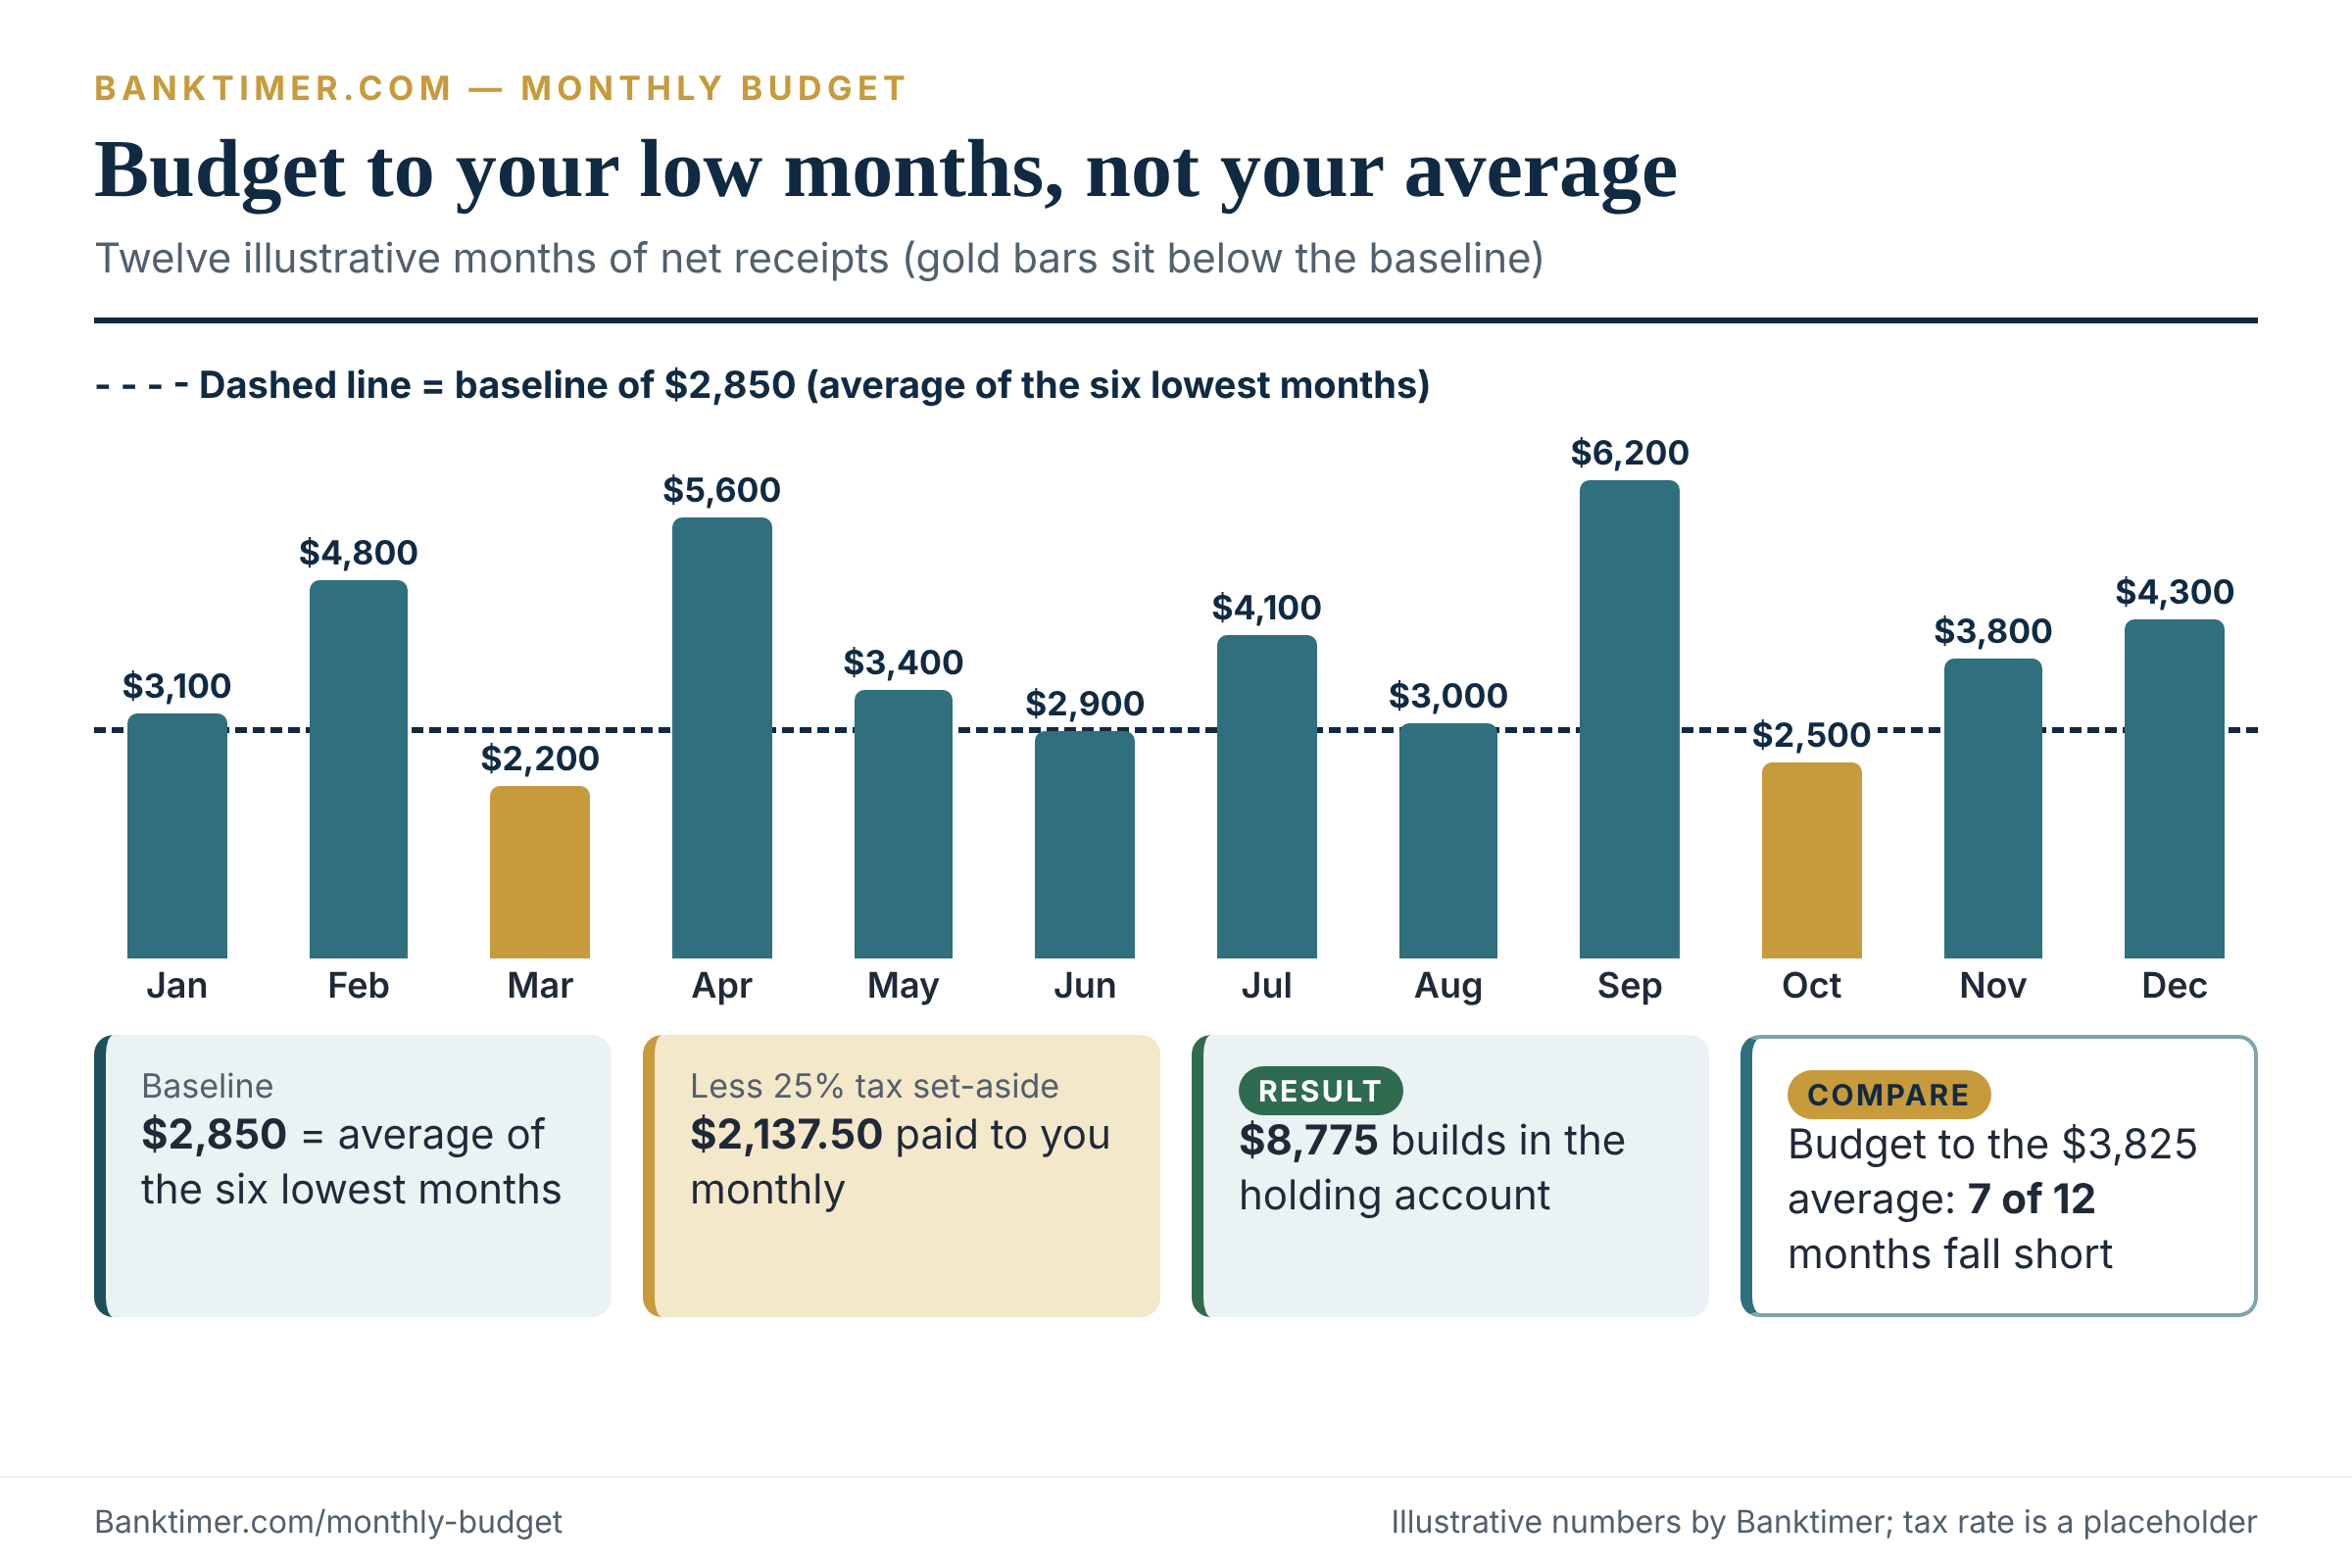
Household C is self-employed. Net receipts after business expenses ranged from $2,200 to $6,200 a month. The twelve months below are illustrative, and the order matters. The plan sets a baseline pay equal to the average of the six lowest months, $2,850, minus an illustrative 25% tax set-aside. That is $2,137.50 a month paid from a holding account to checking.
| Month | Net receipts | 25% tax set-aside | After set-aside | Baseline pay | Holding balance |
|---|---|---|---|---|---|
| Jan | $3,100 | $775 | $2,325 | $2,137.50 | $187.50 |
| Feb | $4,800 | $1,200 | $3,600 | $2,137.50 | $1,650.00 |
| Mar | $2,200 | $550 | $1,650 | $2,137.50 | $1,162.50 |
| Apr | $5,600 | $1,400 | $4,200 | $2,137.50 | $3,225.00 |
| May | $3,400 | $850 | $2,550 | $2,137.50 | $3,637.50 |
| Jun | $2,900 | $725 | $2,175 | $2,137.50 | $3,675.00 |
| Jul | $4,100 | $1,025 | $3,075 | $2,137.50 | $4,612.50 |
| Aug | $3,000 | $750 | $2,250 | $2,137.50 | $4,725.00 |
| Sep | $6,200 | $1,550 | $4,650 | $2,137.50 | $7,237.50 |
| Oct | $2,500 | $625 | $1,875 | $2,137.50 | $6,975.00 |
| Nov | $3,800 | $950 | $2,850 | $2,137.50 | $7,687.50 |
| Dec | $4,300 | $1,075 | $3,225 | $2,137.50 | $8,775.00 |
Average receipts are $3,825 a month. Budgeting to that average would leave seven of the twelve months short, because only five months beat it. The baseline instead falls short in just two, March and October, and the holding account absorbs both. By December it holds $8,775 beyond the baseline pay.
What to do with the surplus and the tax money
First fill a buffer. Three months of baseline pay is $6,412.50. After that, raise the baseline pay or fund goals. That rule is Banktimer’s editorial suggestion, not a standard. Review the baseline once a year, or sooner if your income pattern changes.
The 25% set-aside is a placeholder. Your real tax need depends on income, deductions, filing status, and your state. The IRS says individuals generally must pay estimated tax if they expect to owe at least $1,000 for the year after withholding and credits. The 2026 payment dates are April 15, June 15, September 15, and January 15, 2027. To avoid an underpayment penalty, a payment plan generally must cover the smaller of 90% of this year’s tax or 100% of last year’s (110% if prior-year adjusted gross income exceeded $150,000). Confirm the details with the IRS or a tax professional. A fuller treatment is in the guide to budgeting with irregular income.
Buffers and Sinking Funds: The Layer That Keeps the Plan Alive
A monthly budget handles the known. Buffers handle the rest. Three pots do three different jobs, and mixing them is how plans fail quietly.
Three pots, three jobs
The checking floor is a minimum balance you never plan to spend. It absorbs timing gaps like Sam and Jordan’s. Sinking funds hold money for costs you know are coming, such as a $912 insurance premium in January and July. The emergency fund covers the unpredictable: a job gap, a surprise medical bill, a transmission.
The CFPB’s emergency savings research compared consumers by savings level in a 2022 report. Among those with no emergency savings, 39% had not paid all their bills in the prior month, against 11% of those with some savings and 1% of those with at least a month of income saved. The report shows an association, not proof of cause, and the data are older. The gap is large enough to take seriously.
Turning irregular costs into monthly set-asides
Start with the annual cost, divide by 12, and automate the transfer. If you budget by paycheck, divide by 26. These costs are illustrative.
| Irregular cost (illustrative) | Annual amount | Typical due | Monthly set-aside | Per biweekly paycheck |
|---|---|---|---|---|
| Car insurance, two six-month premiums | $1,824 | January and July | $152.00 | $70.15 |
| Vehicle registration and inspection | $140 | Spring | $11.67 | $5.38 |
| Car maintenance and tires | $720 | Varies | $60.00 | $27.69 |
| Holiday gifts and travel | $900 | November to December | $75.00 | $34.62 |
| Annual subscriptions | $119 | Varies | $9.92 | $4.58 |
| Medical deductible and copay buffer | $600 | Varies | $50.00 | $23.08 |
| Renters insurance | $156 | August | $13.00 | $6.00 |
| Back-to-school and kids | $400 | August | $33.33 | $15.38 |
| Home or appliance repair | $600 | Varies | $50.00 | $23.08 |
| Total | $5,459 | $454.92 | $209.96 |
The total is the point. Nine small items add up to $455 a month, about 6% of Household A’s $7,200. None of them feels like a big expense on its own, so none gets a line in a casual plan. Together they explain why a budget that looks fine in March fails in July. If you drive, put your car insurance deductible in this fund too, so a claim does not land on your checking balance.
How big each pot should be
For the checking floor, find your largest cumulative shortfall in a pay cycle and add a margin. Sam and Jordan’s was $183, so a $500 floor covers it with room to spare. For an emergency fund, the CFPB’s emergency fund guide asks you to think about the most common unexpected expense you have had and what it cost, rather than naming a number. Many planners cite three to six months of essential costs. That is an industry rule of thumb, not a legal standard. See the full emergency fund guide for how to size one.
Where to keep each pot
Keep buffers somewhere you cannot spend them by accident, but can reach in a day. A separate savings account at an FDIC-insured bank or an NCUA-insured credit union fits. Deposit insurance has limits and rules, so check the current ones before you hold large balances. A high-yield savings account is one common home. An emergency fund savings account works the same way and keeps the money visibly separate. Compare fees, transfer times, and minimums, not just the interest rate.
Automation: What to Automate and What to Keep Reviewing
Automation helps most where decisions repeat. A monthly transfer to savings is one decision made twelve times. A grocery purchase is a new decision every time, so it does not automate well.
| Item | Automate? | Why | Risk to watch | Check how often |
|---|---|---|---|---|
| Transfer to emergency fund | Yes | Same amount, same date | Transfer fails if balance is low | Quarterly |
| Sinking fund transfers | Yes | Fixed math from annual costs | Costs rise and set-asides do not | Twice a year |
| Rent or mortgage payment | Yes, with a floor | Avoids late fees | Overdraft if balance dips | Monthly |
| Utilities and phone | Yes, if you keep a floor | Amounts vary a little | A spike can overdraw | Monthly |
| Credit card payment | Yes, for at least the minimum | Protects against missed due dates | Auto-minimum lets interest build | Monthly |
| Subscriptions | Audit, do not automate | Easy to forget | Renewals at higher prices | Quarterly |
| Groceries and dining | No | Variable by nature | Cap alone does not stop spending | Mid-month |
Automate the moves, not the decisions
Set the savings and sinking fund transfers for the day after payday. Do it that way so the money leaves before a purchase drifts in. The CFPB suggests recurring transfers, and employer direct-deposit splits where available. A split keeps the money out of your checking account entirely.
Know your autopay rights
Under Regulation E, you can stop a preauthorized electronic payment by telling your bank orally or in writing at least three business days before the scheduled date. The bank may require written confirmation within 14 days of an oral request. If an amount will vary, the payee must send notice at least 10 days before the transfer, though you can opt for a range. Review the Regulation E rule for the exact wording. These protections apply to payments from consumer deposit accounts, not to every kind of bill payment, so read your agreement.
Autopay also creates risk. The CFPB warns that both a bank and a company can charge fees if the account lacks funds. Pair autopay with a checking floor and learn how overdraft protection is set up on your checking account.
What to keep manual
Review variable categories mid-month and subscriptions every quarter. Check the first autopay after any price change. Autopay is a convenience, not a monitor, so a silent increase will pass without comment.
Debt Inside a Monthly Budget: Minimums, Avalanche, and Snowball
Debt changes a monthly budget in two ways. Minimum payments are fixed costs that cannot slip. Any extra payment is a choice that competes with savings. Here is how the choice plays out with Household B’s three illustrative cards.
Minimums are a floor, not a plan
Household B’s cards carry $2,100 at 17.99%, $4,600 at 28.99%, and $7,400 at 22.99%. These rates are illustrative, not market quotes. For context, the Federal Reserve’s consumer credit release reported an average of 22.15% on card accounts assessed interest in the second quarter of 2026. The minimums are $55, $130, and $190, or $375 together.
Paying only $375 a month, held fixed, would take 73 months and cost about $13,000 in interest on $14,100 of debt. The real schedule differs, because issuers’ minimums usually shrink as balances fall. The direction does not change. A minimum covers interest and little else. See credit card APR for how the rate is applied.
Avalanche versus snowball, with the numbers
The avalanche pays the highest-rate card first. The snowball pays the smallest balance first. Both pay minimums on everything else, and both use an extra $350 a month on top of the $375 in minimums.
| Strategy | Payoff order | Months to debt-free | Total interest | First card closed |
|---|---|---|---|---|
| Avalanche | 28.99%, then 22.99%, then 17.99% | 25 | $3,690.86 | Month 12 |
| Snowball | $2,100, then $4,600, then $7,400 | 25 | $4,018.42 | Month 6 |
| Minimums only (fixed $375) | n/a | 73 | $13,000.24 | Month 58 |
| Avalanche with only $100 extra | 28.99%, then 22.99%, then 17.99% | 45 | $7,203.46 | Month 28 |
Both strategies finish in 25 months. The avalanche costs $327.56 less in interest, because the high-rate balance shrinks first. The snowball closes an account at month 6 instead of month 12. The bigger lever is the extra payment itself: cutting it from $350 to $100 adds 20 months and about $3,500 in interest.
Assumptions: interest is added monthly at one-twelfth of the annual rate, minimums are fixed dollar amounts, and no new purchases or fees occur.
A 2012 study of about 6,000 consumers who paid off credit card debt, by Kellogg School of Management researchers David Gal and Blakeley McShane, found that paying off small balances first was associated with a greater chance of eliminating the debt. The data came from a debt settlement company and were observational. They suggest motivation matters, not that the snowball always wins on cost.
For many people the right answer is the order they will actually follow. If $328 over two years is worth a faster first win, take the snowball. If a quick win does not motivate you, the avalanche is cheaper.
What a surprise does to the payoff plan
Debt plans rarely run on schedule. Take the same three cards and add a $600 car repair in month one. This is where the checking cushion earns its keep.
Paid from a $500 cushion plus $100 of choice spending, the plan does not move: 25 months and $3,690.86 in interest. Put on the 28.99% card with the $350 extra payment unchanged, it takes 26 months and costs $4,120.07, or $429.21 more. Put on the same card while the extra payment pauses for two months, it takes 28 months and costs $4,626.76, or $935.90 more.
The repair itself cost $600 either way. The card version costs up to $936 extra because the balance grows at 28.99% while the extra payment stalls. A small buffer in a monthly budget is not idle money. It is a hedge against exactly this chain reaction.
When a different structure changes the math
A balance transfer credit card or a debt consolidation loan can lower the rate, but both carry fees and terms that vary by offer. Run the same math with the fee included before you move a balance. Also watch your credit utilization as balances move, since closing or opening accounts can change it.
When the plan does not close
If minimums plus essentials exceed take-home pay, no budgeting method fixes the gap. The FTC advises telling creditors what is going on early and trying to work out a payment plan you can manage. The CFPB describes credit counseling through nonprofit organizations that help with budgets and debt management plans. It also advises getting a price quote in writing and warns that some organizations offering debt management plans have defrauded people.
Setting Up Your First Monthly Budget, Step by Step
Do the steps in this order. The first four are research. The last three turn research into a working system.
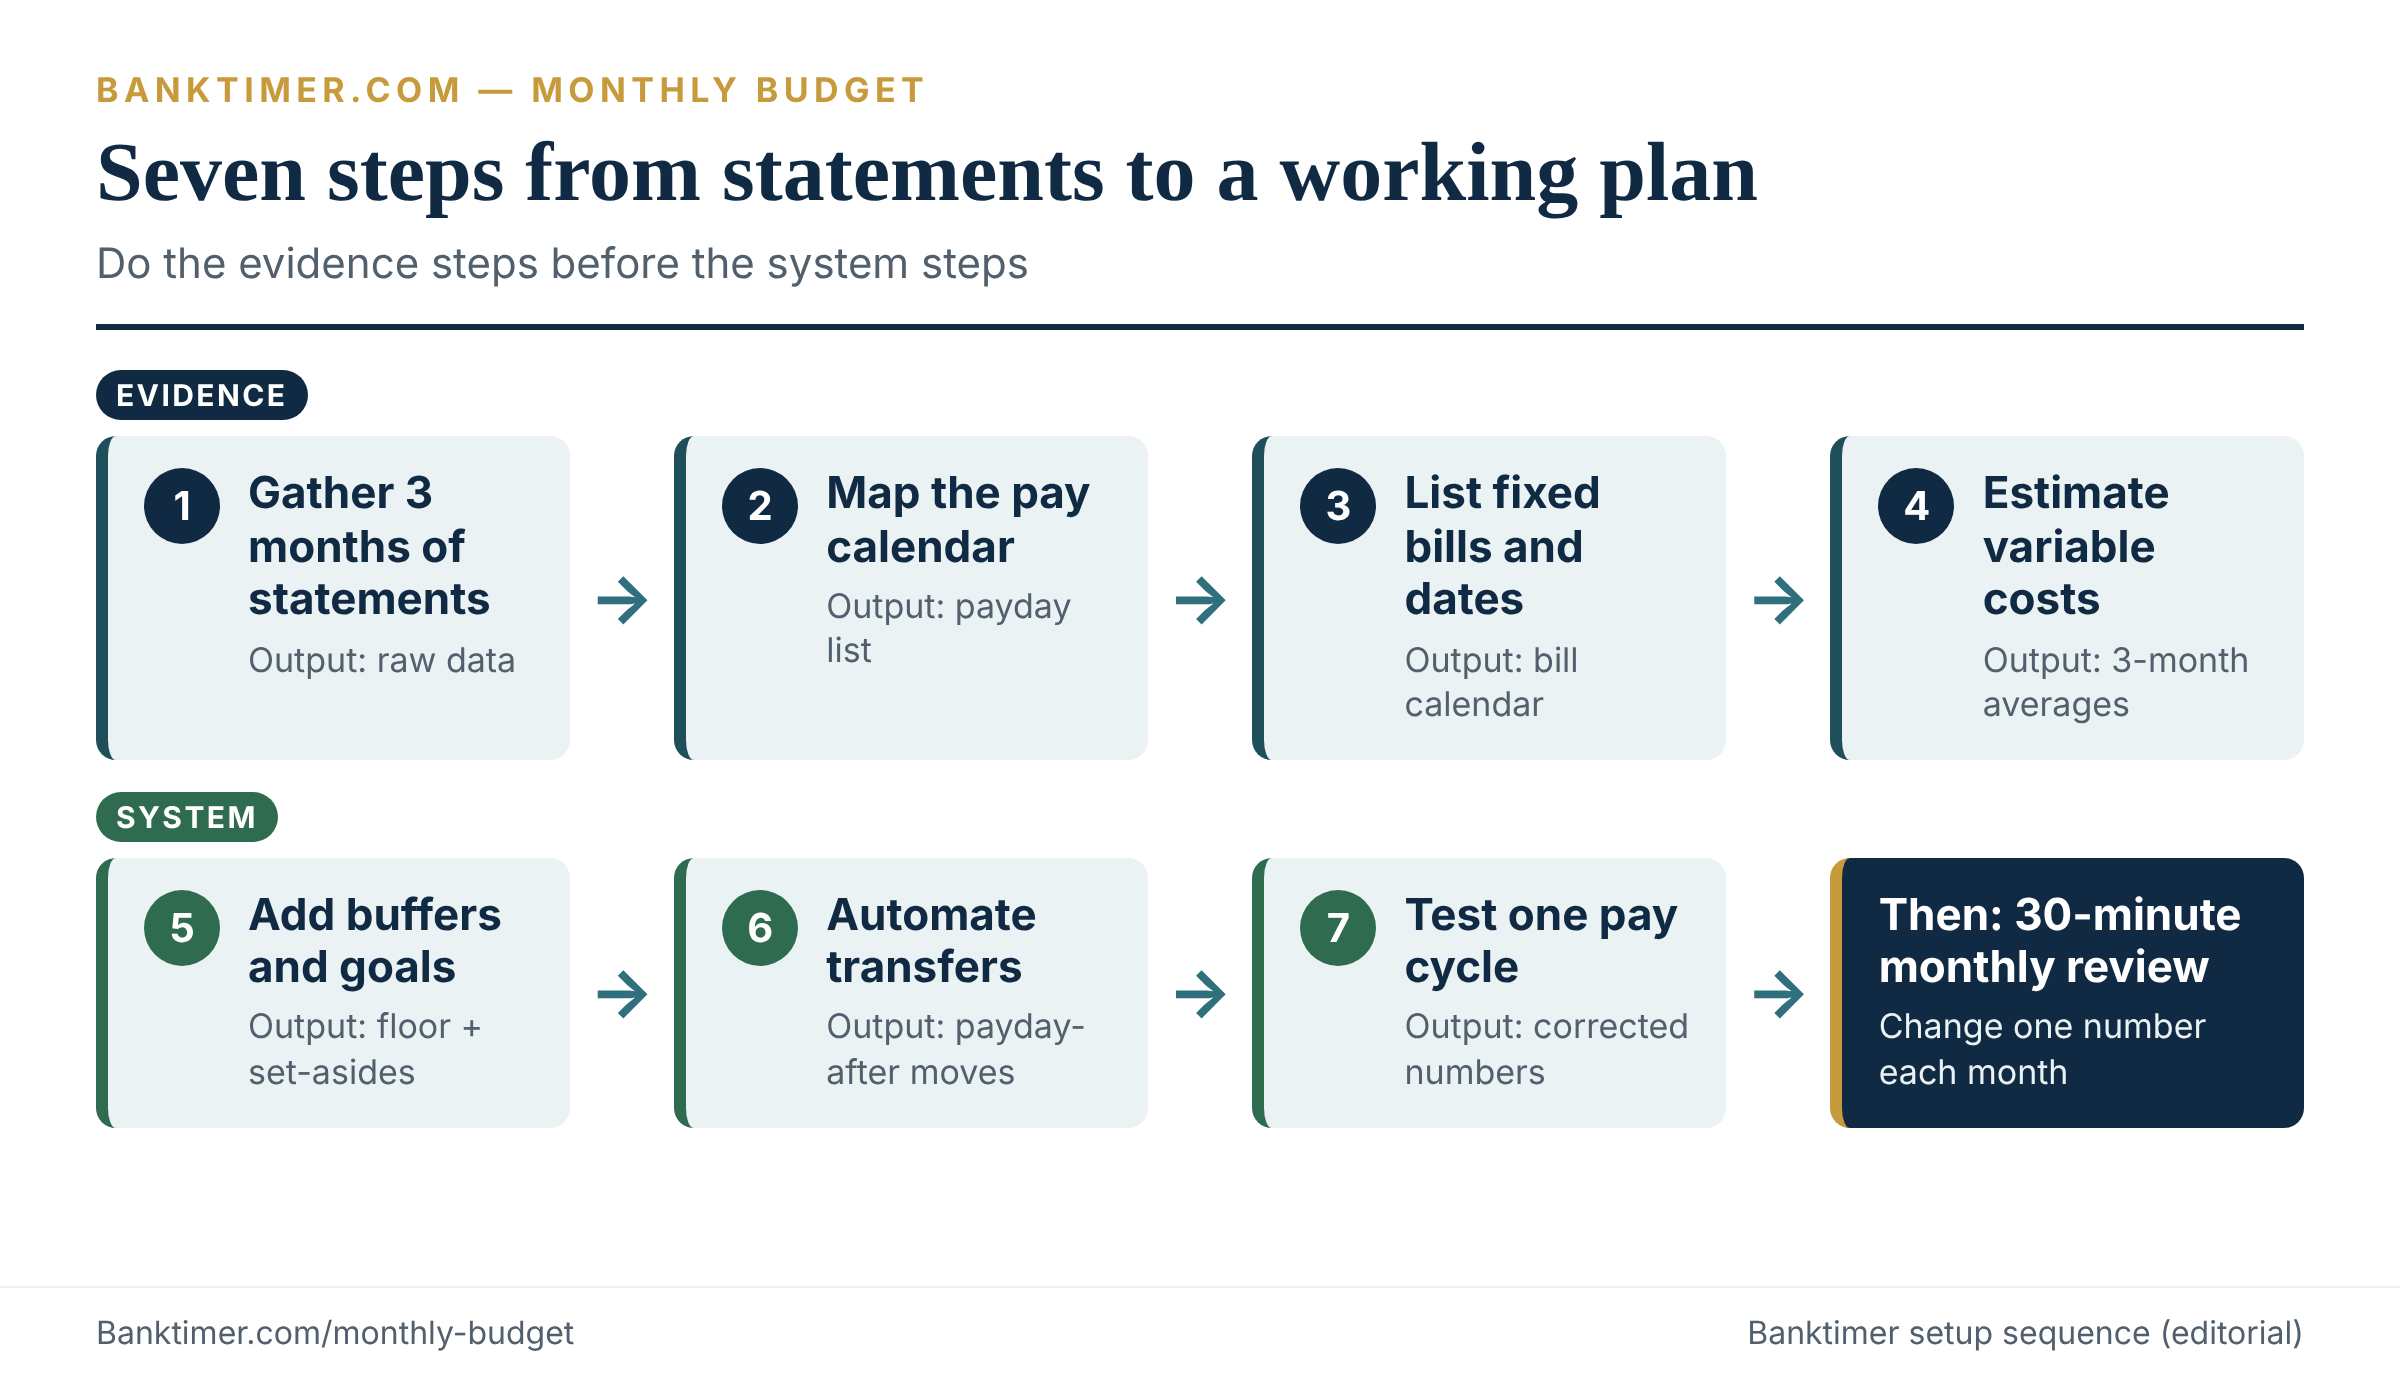
Step 1: Gather three months of statements
Download or pull the last three months of checking and card statements. Three months smooths one-off spikes without hiding trends. Include any account that pays bills. Skip categories for now and just collect the evidence.
Step 2: Map your pay calendar
List every paycheck date for the next 90 days, with the take-home amount. Mark any month with three paychecks. If you have two earners, put both on one calendar. This is the step most people skip, and it is the one that would have saved Sam and Jordan.
Step 3: List fixed costs and their due dates
Write each fixed bill with its amount and due date. Then draw a line at your paydays and see which paycheck pays for what. Anything due before the paycheck that should cover it is a candidate for a moved due date or a cushion.
Step 4: Estimate variable costs from real data
Total each variable category over the three months and divide by three. Use that as the starting estimate. Do not cut anything yet. A plan built on aspiration rather than evidence tends to break by week two.
Step 5: Add buffers and goals
Set the checking floor, the sinking fund transfers, and the emergency fund amount. Add any extra debt payment. Then see whether the plan balances. If it does not, adjust choice spending first and variable needs second, and check whether income or a fixed cost is the real problem.
Step 6: Automate the transfers
Schedule savings and sinking fund transfers for the day after payday, and autopay for fixed bills with a floor in place. Confirm each date against your calendar. Keep manual control of variable categories.
Step 7: Run one pay cycle as a test
Treat the first cycle as a trial. At the end, compare plan with actual and fix the numbers that were wrong. Do not judge yourself on the first month.
- ☐ Three months of statements for every account that pays bills
- ☐ Your last two pay stubs, or three months of business deposits
- ☐ A list of due dates and amounts for every fixed bill
- ☐ Annual and semiannual bills, such as insurance, registration, and tax estimates
- ☐ Current balances, rates, and minimum payments for any debt
- ☐ Your pay calendar for the next 90 days
The 30-Minute Monthly Review
A budget stays useful only if you look at it. Thirty minutes at a set time each month is enough. The goal is to learn something and change one number, not to audit your life.
| Minutes | Task | What you produce | Escalate if |
|---|---|---|---|
| 0 to 5 | Reconcile accounts and balances | Confirmed starting numbers | A transaction looks unfamiliar |
| 5 to 12 | Compare actual to plan by category | A short list of lines over or under | One category is over by a large share three months running |
| 12 to 18 | Check the next 30 days of bills and paydays | Updated bill calendar | A bill falls before the paycheck that covers it |
| 18 to 24 | Move dollars between categories | A revised plan | Total plan no longer balances |
| 24 to 28 | Sweep surplus or cover shortfalls | Transfers made | The cushion fell below your floor |
| 28 to 30 | Note one change | One sentence for next month | You skipped the review twice |
Change the plan, not yourself
If one category runs over for three months, raise the number and take the money from another category. A repeated miss means the estimate was wrong. Cut only when the new number leaves less room for choices than you can live with.
When to rebuild the whole plan
Monthly tweaks handle drift. Some events call for a rebuild within about 30 days: a job change or a new pay schedule, a move or lease renewal, a new child or childcare cost, a raise, a large change in a loan or insurance premium, or a change in household members. Each of these changes at least one fixed cost or your pay calendar, which are the two inputs everything else depends on.
Rebuilding is faster the second time. You already have a template, so you only update income, fixed costs and due dates, then recheck the first 15 days of the month for timing gaps. If a life event shrinks your income, rebuild the monthly budget before the first short month, not after.
A quick weekly check, if you want one
Some people add a five-minute weekly glance at balances and upcoming bills. It is optional. It helps most in the first three months and in months with irregular income.
Budgeting Apps and Your Bank Data
Apps can save time by pulling transactions in automatically. They also ask for access to your accounts. Know what you are granting before you click.
What linking an account means
Most budgeting apps connect through a data aggregator, which logs in to your bank or accesses your data through an interface your bank provides. The CFPB’s guidance on sharing financial data says to confirm that only the data you want shared is being shared, to find out how long it is kept, and to learn how to stop access. It also says deleting an app from your phone does not stop the sharing.
Where the open banking rule stands in October 2026
The CFPB’s Personal Financial Data Rights rule, codified at 12 CFR Part 1033, was written to give consumers a right to authorize outside providers such as budgeting apps to access their account data. According to the Bureau’s compliance page, a court stayed the rule’s compliance dates on October 29, 2025. The Bureau has said it is reconsidering the rule and plans to propose extending the dates. Check the CFPB’s page for the current status before relying on any timeline.
For you, the practical point is simple. A finalized federal open-banking framework is not yet in force. Your protections depend on the app’s terms, your bank’s terms, and other laws that vary. Read both sets of terms.
Spreadsheet, bank tool, or app
A spreadsheet gives full control and keeps data on your machine, but you enter transactions by hand. A bank’s built-in tools stay inside the institution you already trust, with fewer features. An app saves time and widens the data you share. None of these is best for everyone. Match the tool to the effort you will actually spend.
- ☐ What exact data does the app collect, and can I limit it?
- ☐ Does it use my bank login, or an interface my bank provides?
- ☐ How long does it keep my data after I stop using it?
- ☐ Can it move money, or only read balances?
- ☐ How do I revoke access, and how do I confirm that it worked?
- ☐ Does it sell or share my data with third parties?
- ☐ What does it cost after any free period ends?
- ☐ What happens to my history if I cancel?
Pros, Cons, and Who Can Skip the Detail
A monthly budget is a tool. Like any tool, it pays off in some situations and wastes effort in others. Here is an honest accounting.
What a monthly budget does well
It shows leaks before they compound. It assigns money to goals before spending starts. It catches timing gaps, as the Sam and Jordan example shows. And it lowers the odds that a single surprise turns into a card balance. The cost of a miss is smaller when a cushion and a plan already exist.
What it costs you
Time is the main cost. Setup takes a few hours and review takes about 30 minutes a month. There is also false precision, where a tidy spreadsheet creates confidence the numbers do not support. Over-tight plans fail by week two and leave people feeling worse than before. And a detailed plan can hide a simple truth. If income is too low for essentials, no spreadsheet changes that.
Who can skip the line-by-line detail
Some households get most of the benefit from a lighter system. If you already automate savings, hold a solid cushion, carry no high-rate debt, and rarely overdraw, a quarterly check of fixed costs may be enough. A high surplus lowers the stakes of each category. In that case, pay-yourself-first plus an annual 50/30/20 sanity check is a rational choice. Skipping the detail is not a failure. It is a trade of attention for risk, and it works only while the cushion holds.
When budgeting is not the problem
If essentials and minimums already exceed your income, the issue is the gap, not the tracking. Contact creditors early, ask about hardship options, and consider nonprofit credit counseling. Look for income and benefit options too. A budget can show the gap clearly, which is useful, but it cannot close it.
Common Failure Modes and How to Fix Them
Most budgets fail for a short list of reasons. Spot yours and fix that one thing.
| Failure | Why it happens | What you see | Fix |
|---|---|---|---|
| Built on gross pay | Taxes and deductions are forgotten | Plan always short | Use take-home pay only |
| Variable lines from memory | Memory underestimates small purchases | Groceries over every month | Use three months of statements |
| No irregular costs | They are not monthly | Surprise in July and December | Add sinking fund transfers |
| Zero room for choice | The plan is too strict | Burnout by week two | Fund a spending line on purpose |
| Due dates ignored | Totals look fine | Mid-month overdrafts | Align dates or add a cushion |
| Abandon after one miss | One bad week feels like failure | Plan stops being updated | Adjust numbers and keep going |
A budgeting service that asks for your bank password and promises to cut your bills should be checked first. Ask what data it keeps, who else gets it, and how you revoke access. The CFPB’s guidance on sharing financial data is a good checklist.
Frequently Asked Questions
What is a monthly budget?
A monthly budget is a plan that assigns your expected take-home pay to bills, spending, debt payments, and savings for one month. You compare the plan with actual spending at month’s end. It works best when it also matches due dates to paydays.
How do I make a monthly budget if I am paid every two weeks?
List your take-home pay and due dates, then assign each bill to the paycheck that will cover it. Biweekly pay arrives 26 times a year, so two months have three paychecks. Plan on two a month and assign the extras in advance to a named goal.
How much should I save each month?
There is no official number. The 50/30/20 rule suggests 20% for savings and debt payoff, which fits some households and not others. The national saving rate was 4.1% in August 2026, but that is an average, not a target. Start with an amount you can automate and keep, then raise it.
Does the 50/30/20 rule work?
It works as a quick check and fails as a rigid target. Housing alone averaged 33.4% of spending in 2024 BLS data. In high-cost areas or with childcare, needs can pass 50% without any overspending. Use it to spot imbalances, not to judge yourself.
How often should I review my monthly budget?
Review it for about 30 minutes once a month, with an optional five-minute weekly glance. Check variable categories mid-month so you can still adjust. Review fixed costs and sinking fund amounts quarterly, or whenever a bill or rate changes.
Should I budget with gross or take-home income?
Use take-home pay, which is what actually lands in your account. Gross pay ignores taxes and deductions, so a plan built on it is always short. If you are self-employed, treat estimated taxes as a monthly set-aside.
How do I budget with irregular income?
Base the plan on a conservative baseline, such as the average of your lowest months, and pay yourself that amount from a holding account. Set aside money for taxes first. High months build the holding account that covers low months. See the Household C example above.
Is a budgeting app safe to use?
It depends on the app. Check what data it collects, how long it keeps it, who it shares it with, and how you revoke access. Deleting the app from your phone does not stop data sharing. A spreadsheet avoids the question at the cost of manual entry.
How should I handle a month with three paychecks?
Budget as if the month has two, then assign the third in advance. Good targets are a sinking fund, an emergency fund, or extra debt payments. Without a plan, the extra check tends to blend into everyday spending.
What if my monthly budget never balances?
First find out whether spending or income is the gap. If spending, trim choice spending and renegotiate fixed costs. If income, no cut will close it. Contact creditors early, consider nonprofit credit counseling, and get fee quotes in writing before signing.
Pull your last three statements and write each bill’s due date beside your next two paydays. Circle any bill due before the paycheck meant to cover it. Those circled lines are where your monthly budget will break first.
A monthly budget works when it matches the way money moves, not just the total. The variable that matters most is the gap between when income arrives and when bills leave. In the illustrative household, a balanced $3,700 plan still dipped to negative $183 because most bills landed before payday. Fix timing first, with a cushion and aligned due dates. Then pick the lightest method that targets your real failure point, such as zero-based planning, envelopes or a pay-yourself-first transfer. Review the plan for 30 minutes a month, and adjust it instead of blaming yourself. A budget is worth the effort when it changes a decision before the money moves. It does not replace emergency savings or a debt payoff plan, so build both into the same page.
Methodology
This article was researched on October 6, 2026. National figures come from the Federal Reserve, the Bureau of Labor Statistics, the Bureau of Economic Analysis, and the CFPB, as listed in the Sources section, and each carries its release date in the text. Rules and thresholds from the CFPB and IRS were checked on their official pages on that date.
Every household, bill, balance, rate, and payoff figure is a Banktimer illustration, labeled as such, and is not a real customer or a current market quote. Calculations were run in Python and rechecked. Assumptions are stated next to each example. Rules of thumb, such as the three-month buffer and the lowest-six-months baseline, are editorial suggestions, not regulations.
Rates, laws, and federal data change. The 2025 Consumer Expenditure Survey release and the status of the open banking rule are the likeliest to move soon. Banktimer is not a law firm, tax preparer, or financial advisor, and this article is general education, not personal advice. For tax questions, talk to a qualified tax professional. For decisions about debt, a nonprofit credit counselor can review your full situation.
Sources
- Federal Reserve Board, Economic Well-Being of U.S. Households in 2025, executive summary, issued May 13, 2026; checked October 6, 2026.
- Bureau of Labor Statistics, Consumer Expenditures in 2024, released December 19, 2025; checked October 6, 2026.
- Bureau of Economic Analysis, Personal Income and Outlays, August 2026, released September 30, 2026; checked October 6, 2026.
- Bureau of Labor Statistics, Consumer Price Index, August 2026, released September 11, 2026; checked October 6, 2026.
- Federal Reserve Board, G.19 Consumer Credit, released September 8, 2026; checked October 6, 2026.
- CFPB, Personal financial data rights compliance page; checked October 6, 2026.
- CFPB, What to consider when sharing your financial data, July 24, 2020.
- CFPB, Budgeting: How to create a budget and stick with it, June 5, 2019.
- CFPB, Adjusting your bill due dates, November 28, 2018.
- CFPB, Emergency savings and financial security report, March 2022.
- CFPB, Regulation E, 12 CFR 1005.10, preauthorized transfers; checked October 6, 2026.
- IRS, Estimated tax FAQ; checked October 6, 2026.
- Kellogg School of Management, The snowball approach to debt, August 2012 (secondary summary of Gal and McShane, Journal of Marketing Research).
- FTC, How to get out of debt; checked October 6, 2026.
- CFPB, What is credit counseling?; checked October 6, 2026.